Is the massive and growing investment in AI infrastructure worth it?
It’s a loaded question that yields different answers — depending on who you ask.
One of the sloppier answers I often hear goes something like this: “Every quarter, mega-cap tech companies announce new huge investments in AI. But even after spending all that money, they’ve been reporting huge quarterly profits.”
This view isn’t technically wrong, but it obfuscates how companies account for the investments in their financial statements. While it is true that companies are spending massive amounts of cash on AI (as reported on cash flow statements), the bulk of these investments have yet to appear as accrued expenses on future income statements.
And it’s the income statement that gives us the quarterly earnings we hear about in the news every three months. It’s how we get a better sense of a company’s ongoing profitability.
This is a wonkier topic than what I usually write about. But I suspect it’ll become increasingly important to understand as these expenses become a bigger part of quarterly earnings announcements.
From capex to depreciation expense 🧮
For the past few years, mega-cap tech companies have committed increasing amounts of capital toward buying hardware and building the massive facilities needed to support booming demand for AI. These capital expenditures (capex) are already in the high nine figures and are expected to cross the $1 trillion mark soon. The size and speed of the investment are why these companies — including Amazon, Meta, Alphabet, Microsoft, and Oracle — are called hyperscalers.
The companies selling the products and services to support this buildout have seen an immediate earnings boom, which has helped bolster the stock market this year.
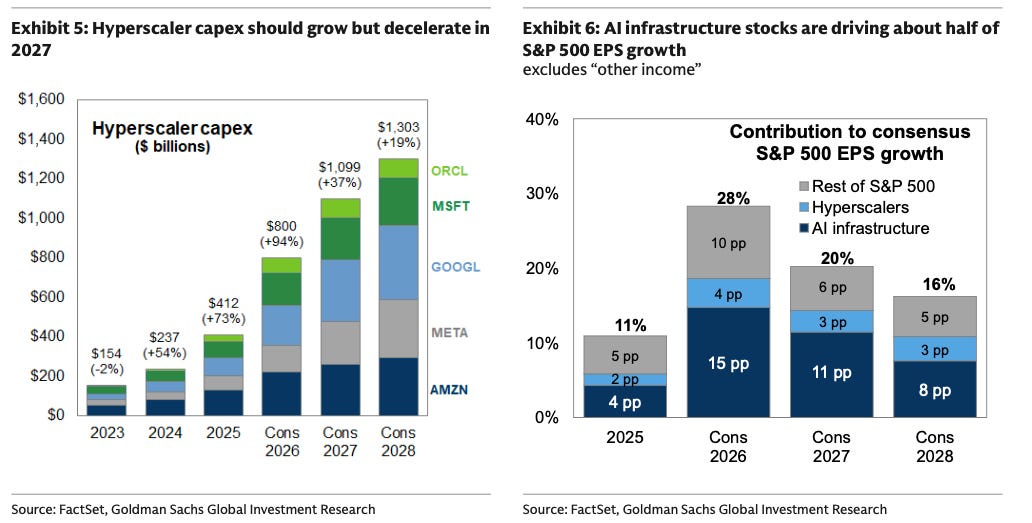
“The mega-cap U.S. hyperscalers are on track to spend $800 billion on capex this year, an increase of 94% vs. 2025,” Goldman Sachs’ Ben Snider wrote in a Sept. 18 note. “That spending is flowing through to the earnings of the AI infrastructure complex including semiconductor, tech hardware, industrials, and utilities companies, which are collectively accounting for roughly half of consensus S&P 500 earnings growth this year.”
For the hyperscalers themselves, however, much of the recent attention has focused on the size of the investment and how these companies are financing it. And while mountains of cash have been flying out of these companies’ windows, most of this investment has yet to show up as expenses on income statements.
Remember: Big investments don’t hit income statements all at once during a single reporting period. Instead, companies depreciate them over the investment’s estimated useful life, which usually lasts years. For more on this, read this.
In other words, the hundreds of billions of dollars spent on AI infrastructure will effectively be chopped up and spread out over years. And that means we’ll see much more of it show up in the form of ballooning depreciation expenses in future quarterly earnings reports.
For investors, the size of the investments doesn’t really matter. What matters is whether these companies will generate enough revenue and operate efficiently enough to stay profitable as they work off those depreciation expenses.
Don’t expect a definitive answer today about whether this bet on AI will be profitable. It’s hard enough to predict the next quarter. It’s much more difficult to predict what’ll happen over the next five to 10 years.
But the coming depreciation expense is at least a bit more certain because it is a function of measurable capex. And Goldman’s Snider ran the numbers and cautions that the coming depreciation expense will be a major hurdle for earnings growth.
“Hyperscaler depreciation expenses will continue to increase as capex growth decelerates, further dampening the boost of AI investment spending to S&P 500 earnings growth,” Snider wrote. “We estimate a drag from hyperscaler depreciation expenses on S&P 500 earnings growth of 5pp in 2027, offsetting nearly half of the 11pp boost to earnings from capex spending. By 2028, the drag from depreciation should offset the S&P 500 earnings uplift from continued capex spending.” (Emphasis added.)
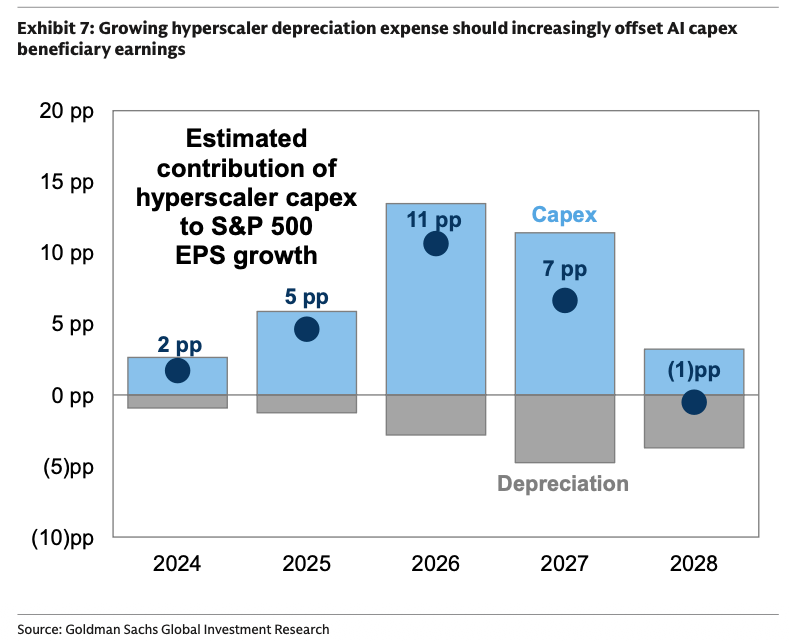
In other words, Snider expects the AI earnings tailwind to fade by 2028 as depreciation expense becomes a bigger headwind. (This is similar to what Morgan Stanley analysts cautioned in January.)
Whether these companies overcome this depreciation headwind will largely depend on the revenue they generate from the AI goods and services they sell. (The revenue matter is a whole other can of worms, which we’ll have to discuss later.)
Zooming out 🔭
Depreciation and accrual accounting are pretty advanced topics, and I’m sure many investors will continue to struggle to wrap their heads around it all.
For what it’s worth, this is basic stuff for top business executives and the analysts covering the companies. That is to say, it’s not some secret that this earnings headwind is looming. In fact, analysts are already forecasting earnings growth to decelerate in 2027 and 2028, which in turn may help explain why stock market valuations have been cooling over the past year.
Some investors may be able to get away with not understanding how it all works. Under normal conditions, accounting ignorance can be bliss.
But if you’re someone who watches a lot of financial news and reads a lot of financial commentary, it would suit you well to have a basic understanding of how depreciation works.
Because eventually, headlines about the AI capex earnings tailwind will fade, and we’ll hear a lot more about the AI depreciation earnings headwind.
-
Related from TKer:
Struggling to make sense of Big Tech’s $600 billion bet on AI? Here’s a metric to watch 📋
The stock market may already be adjusting to a future with slower earnings growth 🤔
A sneak preview of Wall Street’s outlook for stocks in 2027 🔭
Review of the macro crosscurrents 🔀
📈The stock market climbed last week, with the S&P 500 rising 1.2% to end at 7,743.41. The index is now down 0.7% from its August 13 closing high of 7,798.99 and up 13.1% year-to-date. For market insights, check out the Stock Market tab at TKer. »
There were several notable data points and macroeconomic developments since our last review:
🏭 Business investment activity rose. Orders for nondefense capital goods excluding aircraft — a.k.a. core capex or business investment — increased 1.6% in August to a record $87.6 billion.
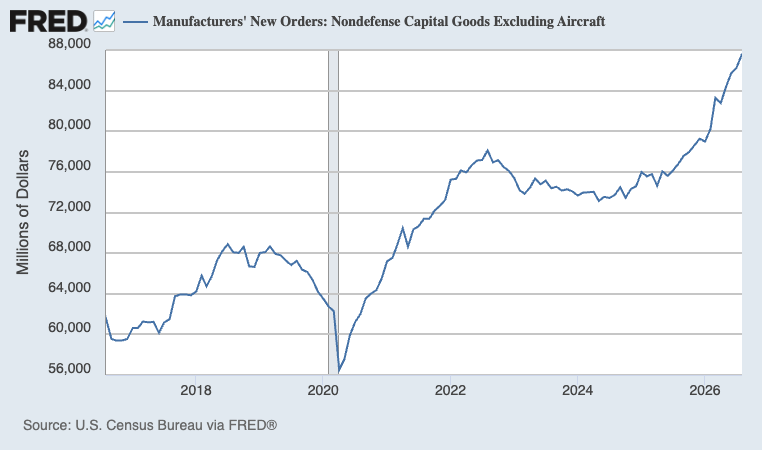
Core capex orders are a leading indicator, meaning they foretell economic activity down the road.
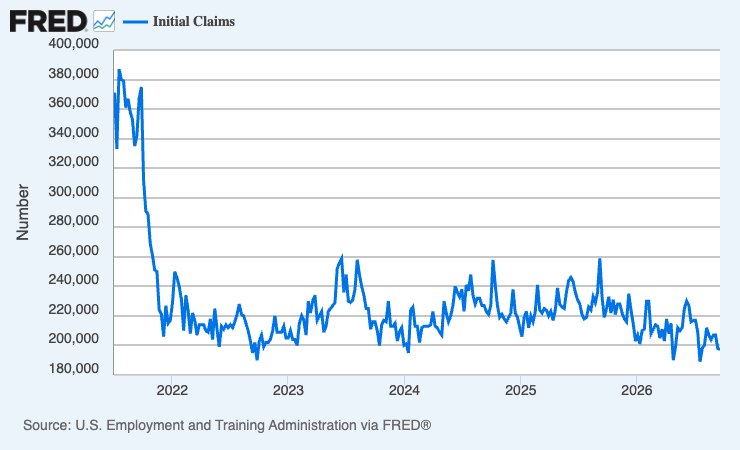
💼 New unemployment insurance claims, total ongoing claims remain low. Initial claims for unemployment benefits ticked down to 197,000 during the week ending Sept. 19, down from 198,000 the week prior. This metric remains at levels historically associated with economic growth.
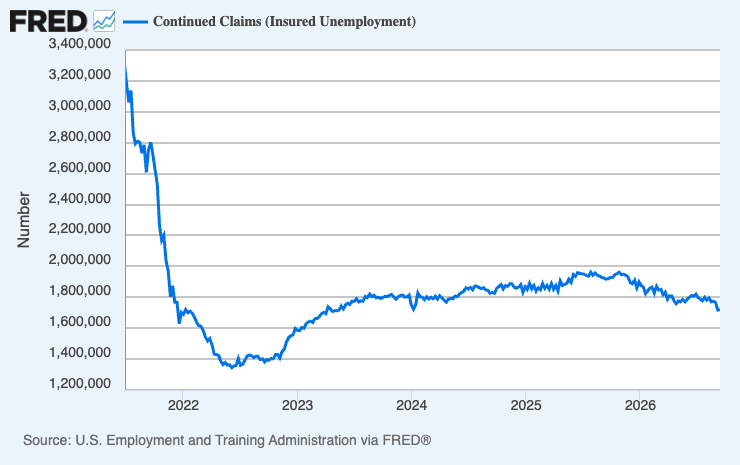
Insured unemployment, which captures those who continue to claim unemployment benefits, ticked up to 1.72 million during the week ending Sept. 12.
For more on the labor market, read: Why mass tech layoffs have little effect on total employment 💾
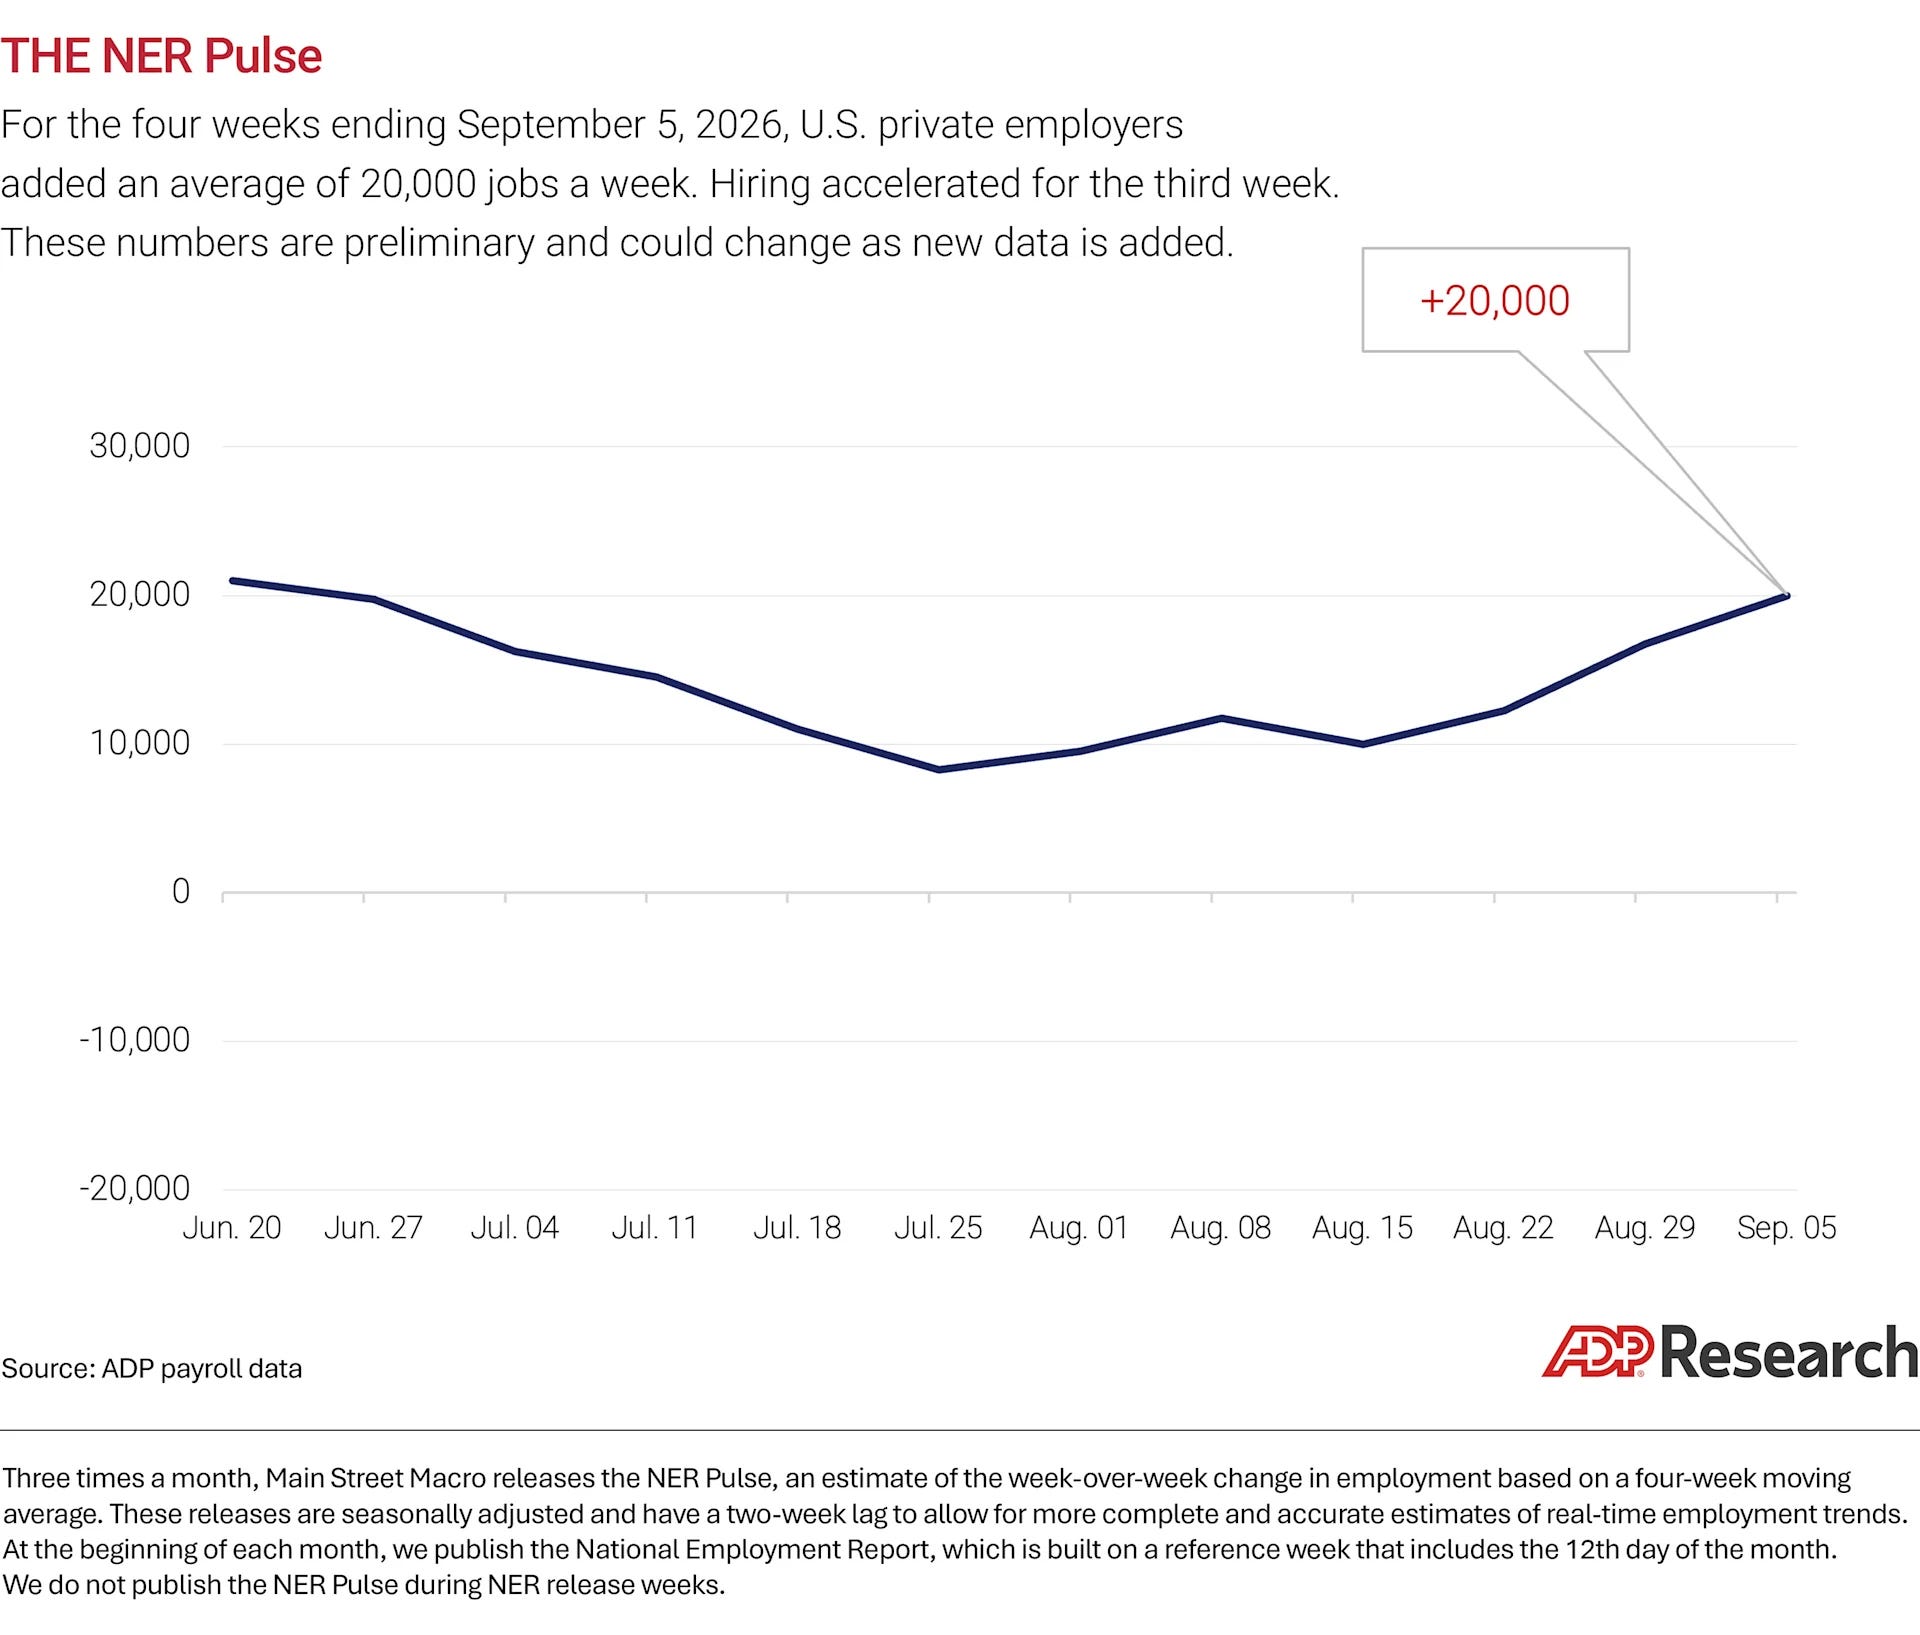
🤔 Recent private job growth is picking up. According to payroll processor ADP, private U.S. employers added 20,000 jobs in the four weeks ending Sept. 5.
For more on the labor market, read: Things are looking up in the labor market 👍
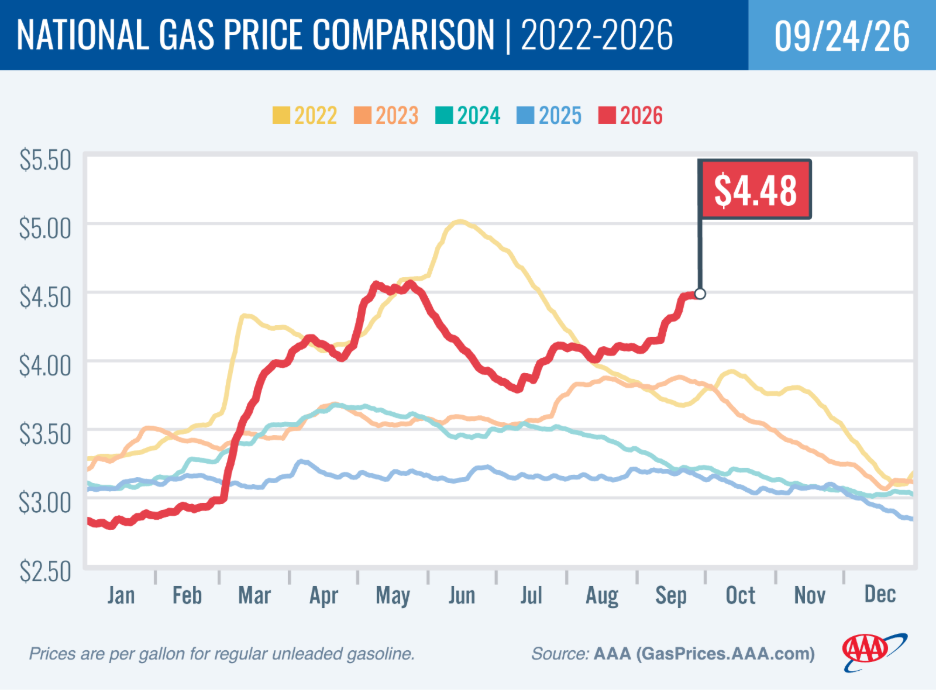
⛽️ Gas prices rise. From AAA: “The national average for a gallon of regular gasoline continues to climb, up nearly 5 cents from last week. At $4.48 per gallon, this is the highest the national average has ever been for this time of year. Typically, the start of autumn brings lower gas prices, but lingering volatility in the Strait of Hormuz and the high cost of crude oil are driving up pump prices. This month is on track to set a new September record. So far, the average for this month is $4.30, higher than the previous September record of $3.83 set in 2023.“
Here’s a longer-term look at the trajectory of gas and diesel prices, as tracked by the EIA.
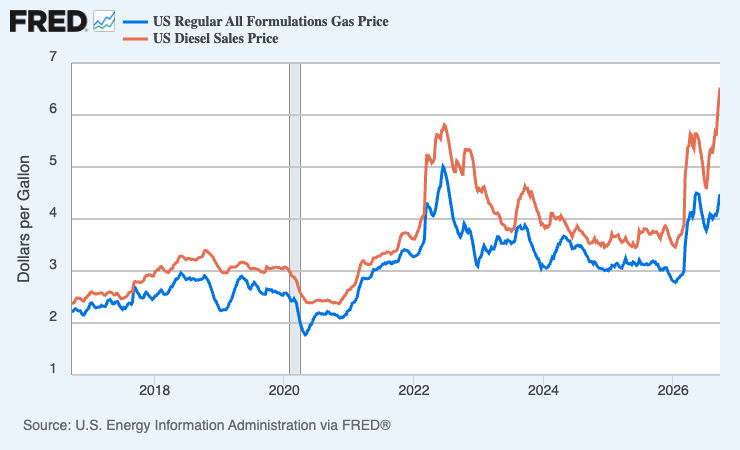
For more on energy prices, read: Our love-hate relationship with rising oil prices in charts 💔🛢️📊
💳 Card spending data is holding up. From BofA: “Total card spending per HH was up 6.9% y/y in the week ending Sep 19, according to BAC aggregated credit & debit card data. Earlier retail availability than last year of new electronics releases likely contributed to the strength in y/y spending. Surging gas prices have once again opened up a gap in ex-gas spending between higher- and lower-income HHs.”
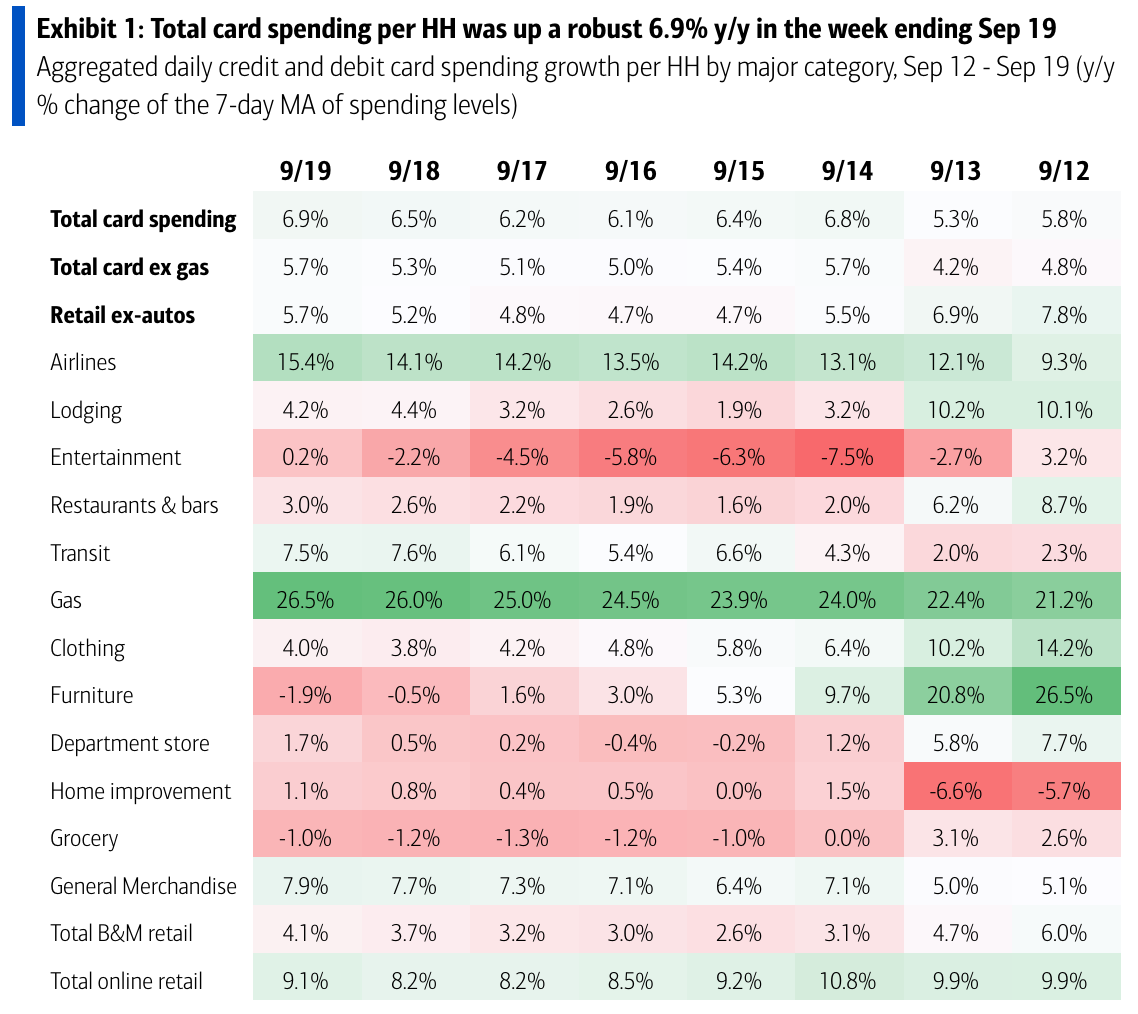
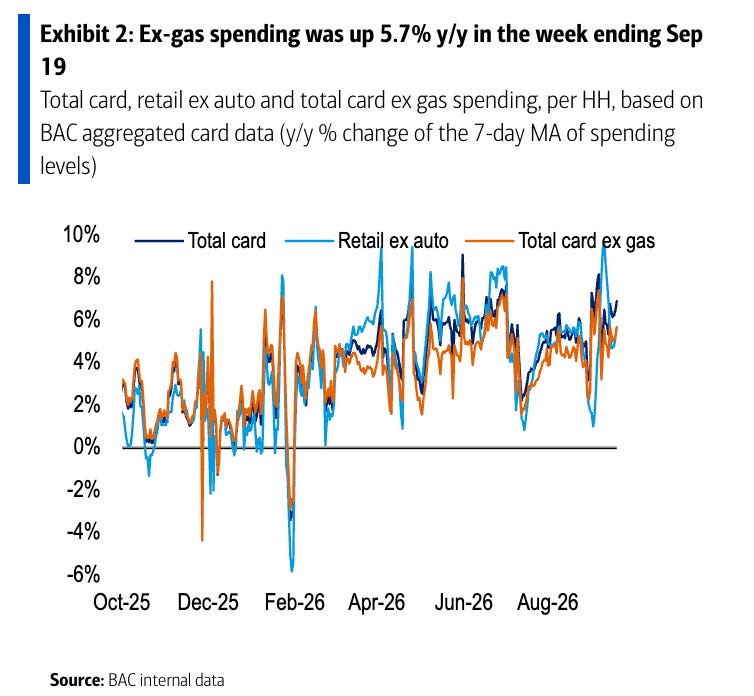
Consumer spending data has looked a lot better than consumer sentiment readings. For more on this contradiction, read: We’re taking that vacation whether we like it or not 🛫 and Household finances are both ‘worse’ and ‘good’ 🌦️
👎 Consumer vibes are in the dumps. From the University of Michigan’s September Surveys of Consumers: “Consumer sentiment ticked down less than four index points in September, reaching the lowest reading in four months and down 15% from January 2026. Views of current and year-ahead expected personal finances both weakened about 10% this month, with concerns over high prices continuing to climb. Buying conditions for durables improved a bit, in part due to a perception that completing such purchases now would help consumers avoid higher prices in the future. The short-run outlook for business conditions plunged amid renewed worries that elevated fuel prices and re-escalating trade disputes could pass through to the economy as a whole.”
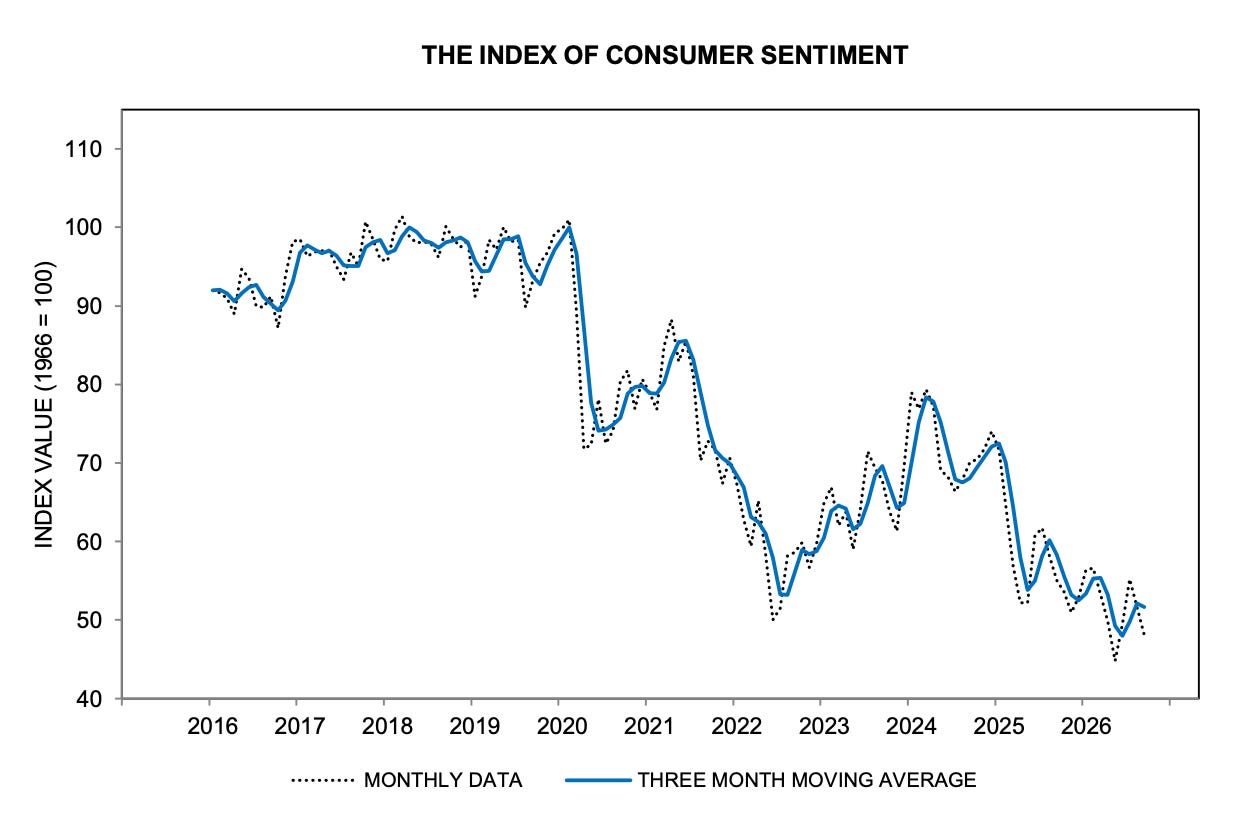
More: “Overall, interviews reveal broad agreement across the political spectrum that the outlook for the economy has weakened since the beginning of the year. After particularly large declines in sentiment this month, Republican sentiment is now 20% lower than January 2026; Democrats are down 13% over the same period.“
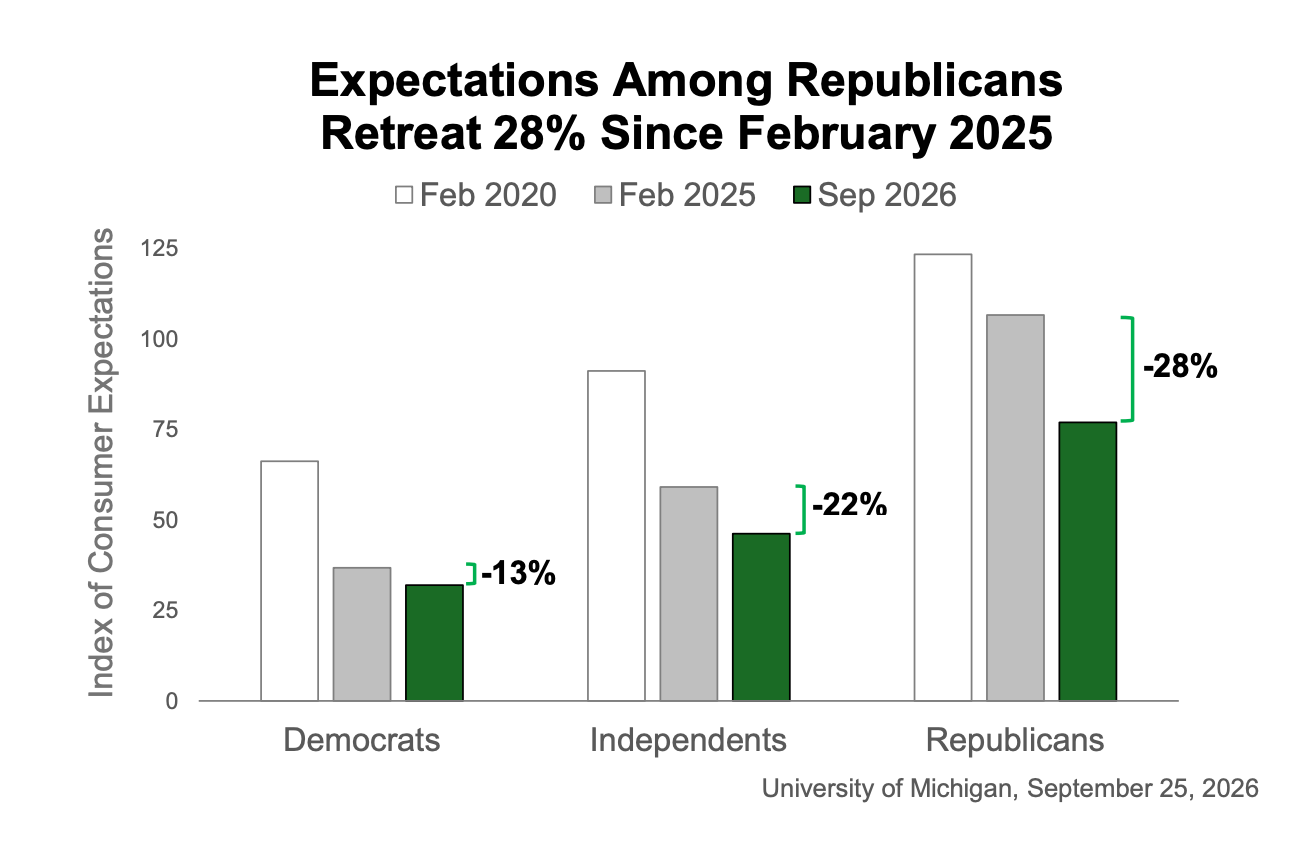
For more on consumer sentiment, read: What consumers do > what consumers say 🙊
🏠 Mortgage rates rise. According to Freddie Mac, the average 30-year fixed-rate mortgage rose to 7.03%, up from 6.95% last week.
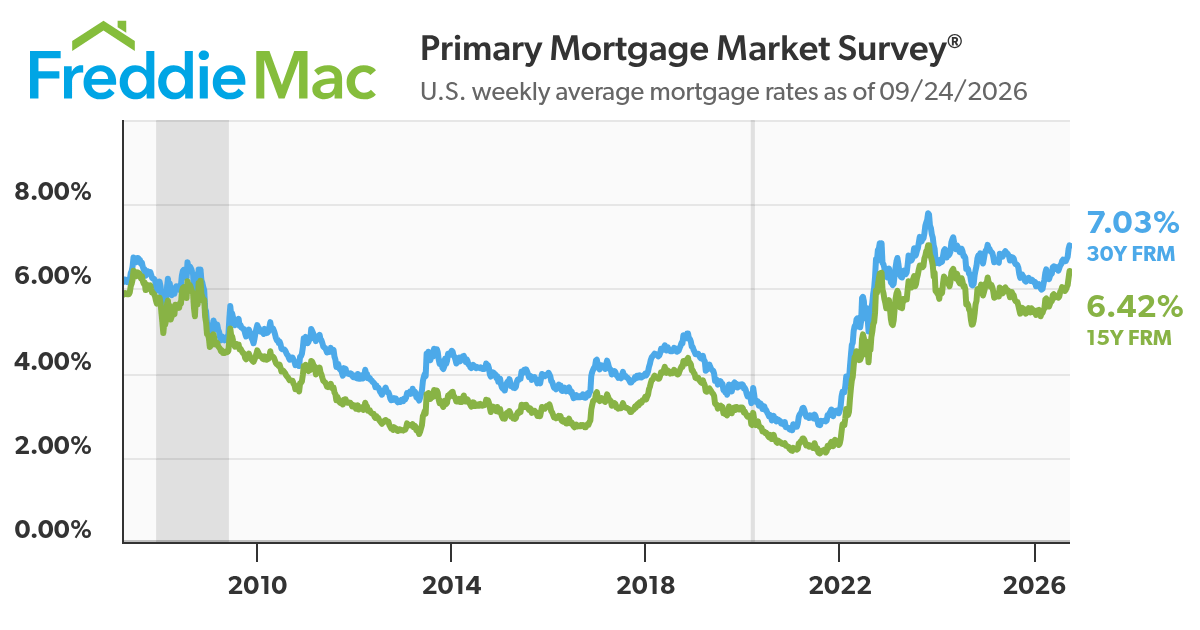
As of Q2, there were 149.5 million housing units in the U.S., of which 87.0 million were owner-occupied and about 40% were mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the weekly movements in home prices or mortgage rates.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
🏘️ New home sales rose. Sales of newly built homes increased 6.4% in August to an annualized rate of 684,000 units.
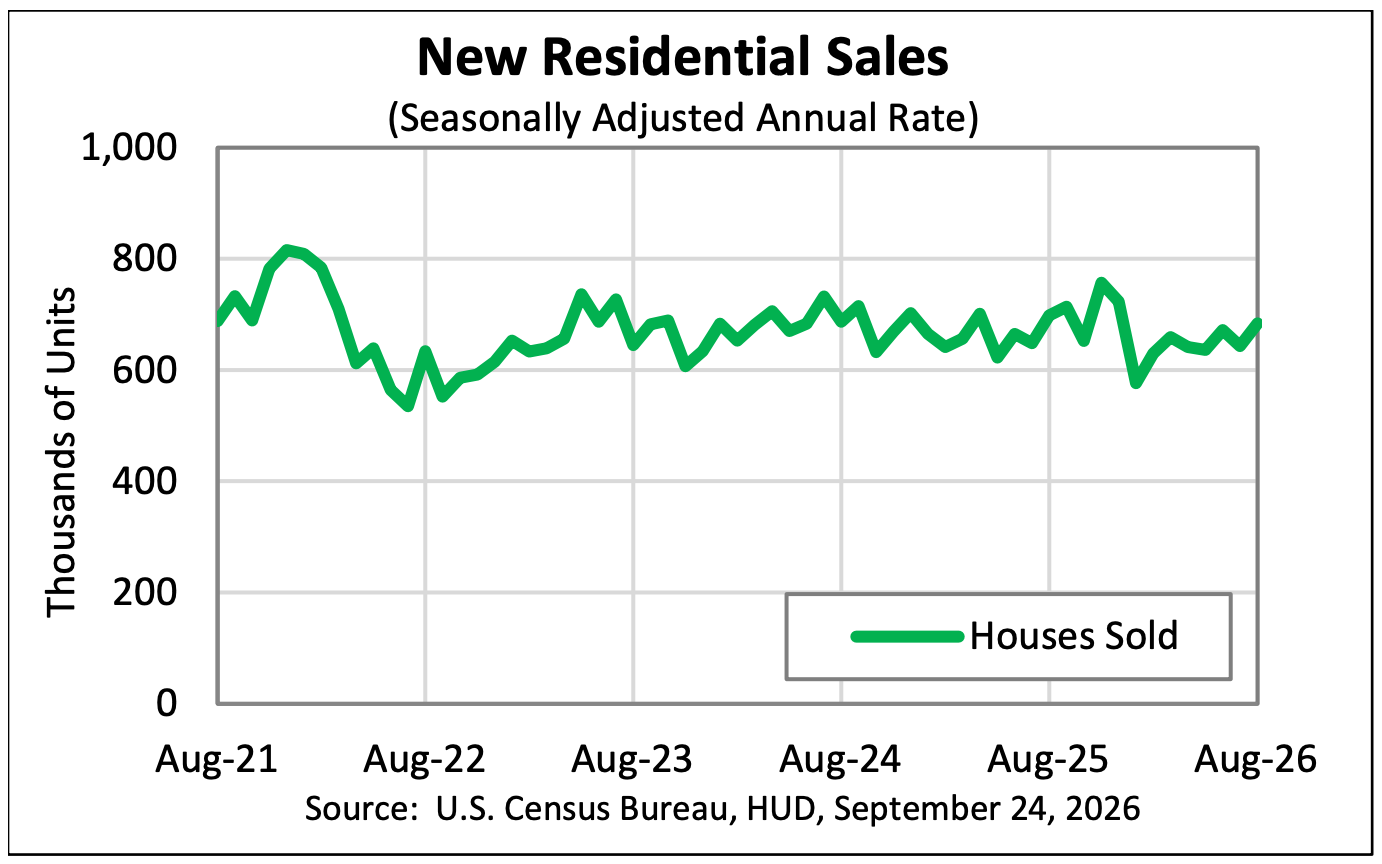
New home sales figures come with a large margin of error. For more on this, read: Mathematical context can totally change the story 🧮
🤔 Economic activity survey signals a pickup in growth. From S&P Global’s September U.S. Flash PMI: “U.S. business continues to boom, with output growing at the fastest rate for over five years in September. Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole.
“To put the growth surge in context, barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015. Business is clearly booming now in both manufacturing and services.
“However, this growth is being accompanied by some of the most severe supply chain bottlenecks seen in the near-two-decade survey history if the pandemic is excluded, with companies also reporting increasing problems finding suitable staff. Backlogs of work are consequently rising sharply. While this accumulation of uncompleted orders bodes well for the further expansion of output and capacity in the coming months, it also indicates that companies are developing more pricing power, and hence is a worry for the inflation outlook.
“Firms’ input costs have meanwhile jumped in September at the steepest rate for four years, with fuel and transport costs spiking higher thanks to the rise in oil prices seen during the month, which will add further to the upward pressure on selling prices and inflation in the coming months.”
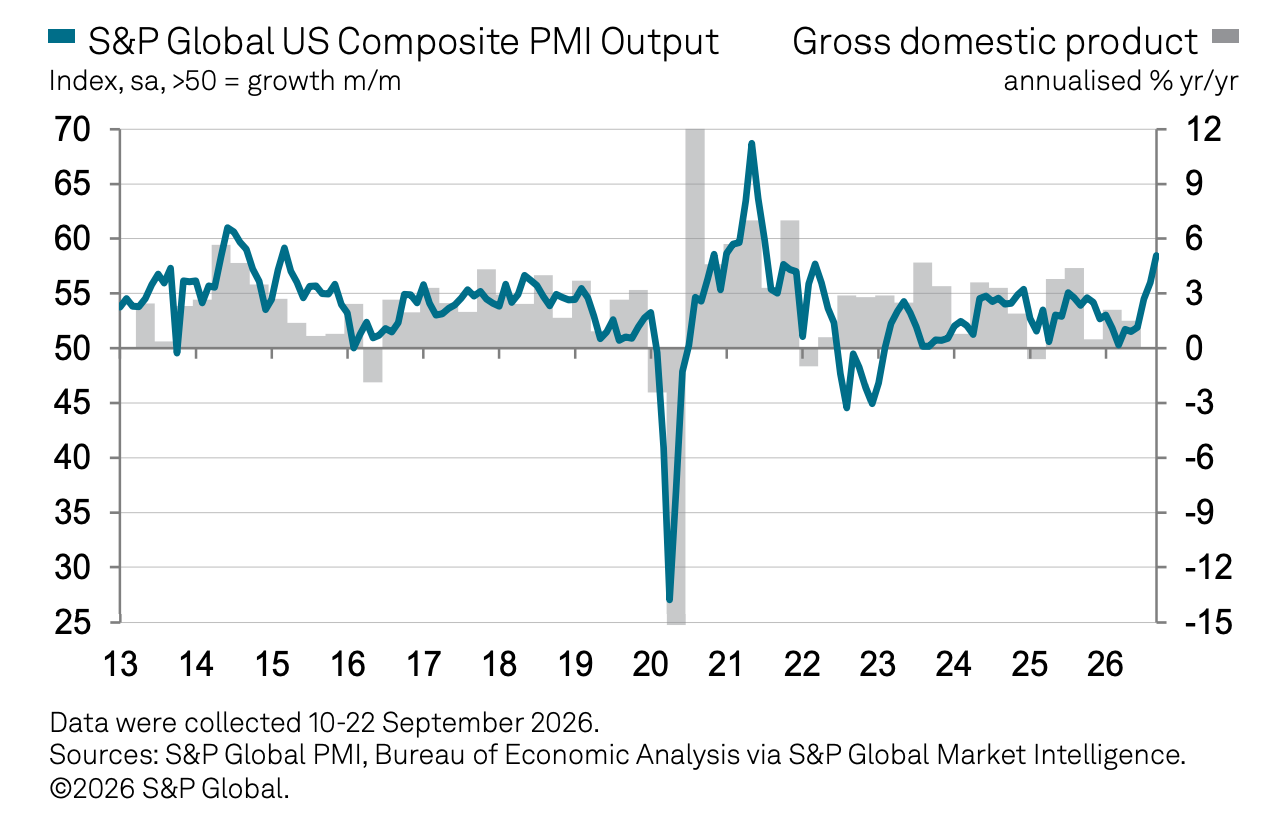
Keep in mind that during times of perceived stress, soft survey data tends to be more exaggerated than actual hard data.
For more on this, read: What businesses do > what businesses say 🙊 and 4 sometimes-conflicting ways I’m thinking about the economy 😬😞😎🙃
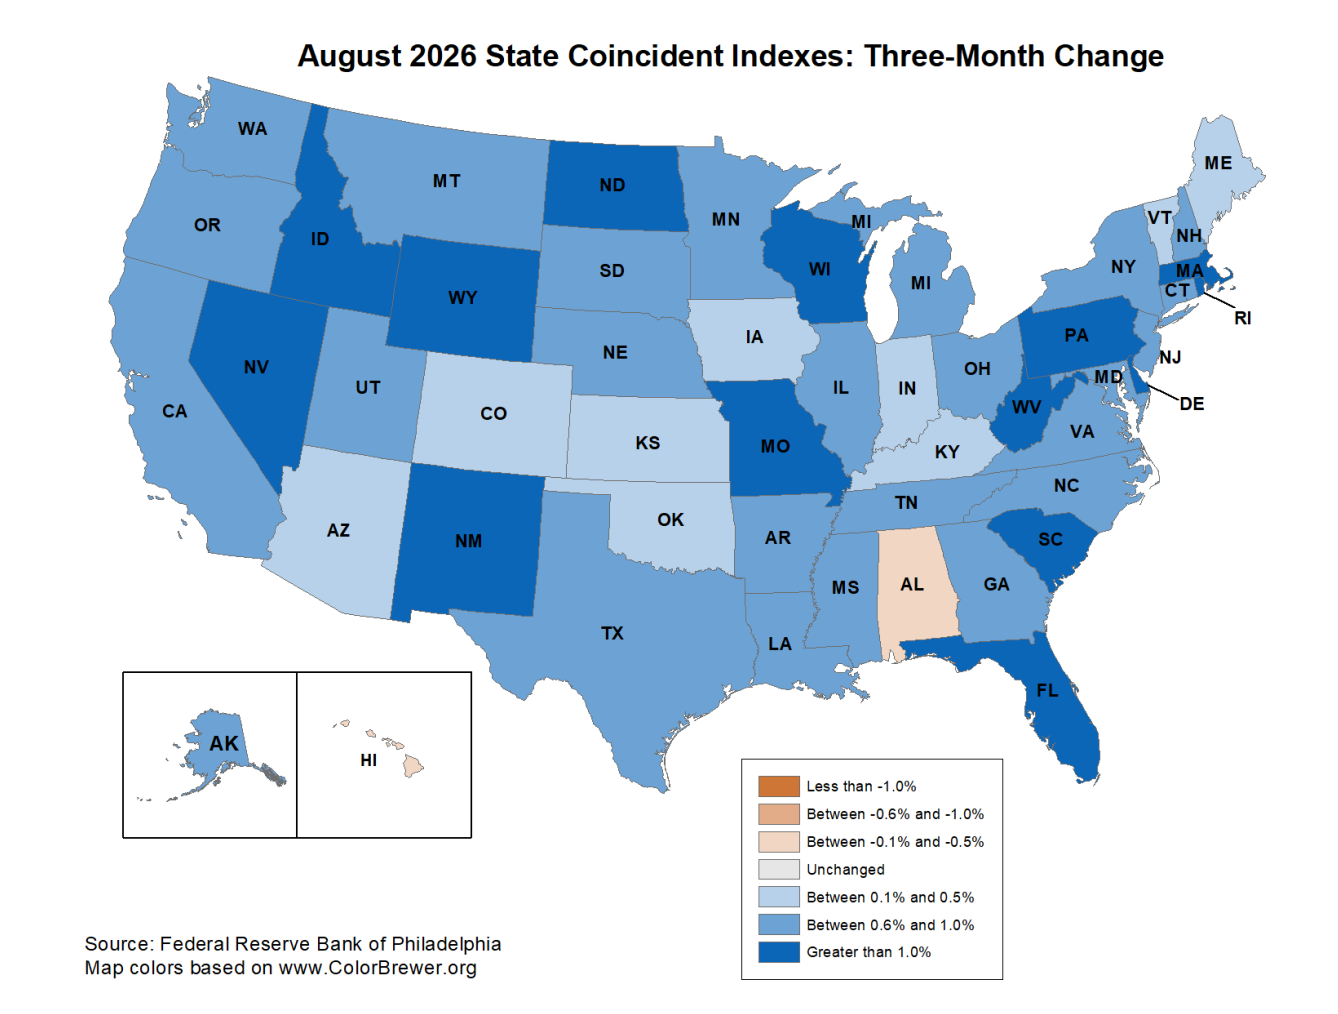
🇺🇸 Most U.S. states are still growing. From the Philly Fed’s August State Coincident Indexes report: “Over the past three months, the indexes increased in 48 states and decreased in two states, for a three-month diffusion index of 92. Additionally, in the past month, the indexes increased in 46 states, decreased in two states, and remained stable in two, for a one-month diffusion index of 88.”
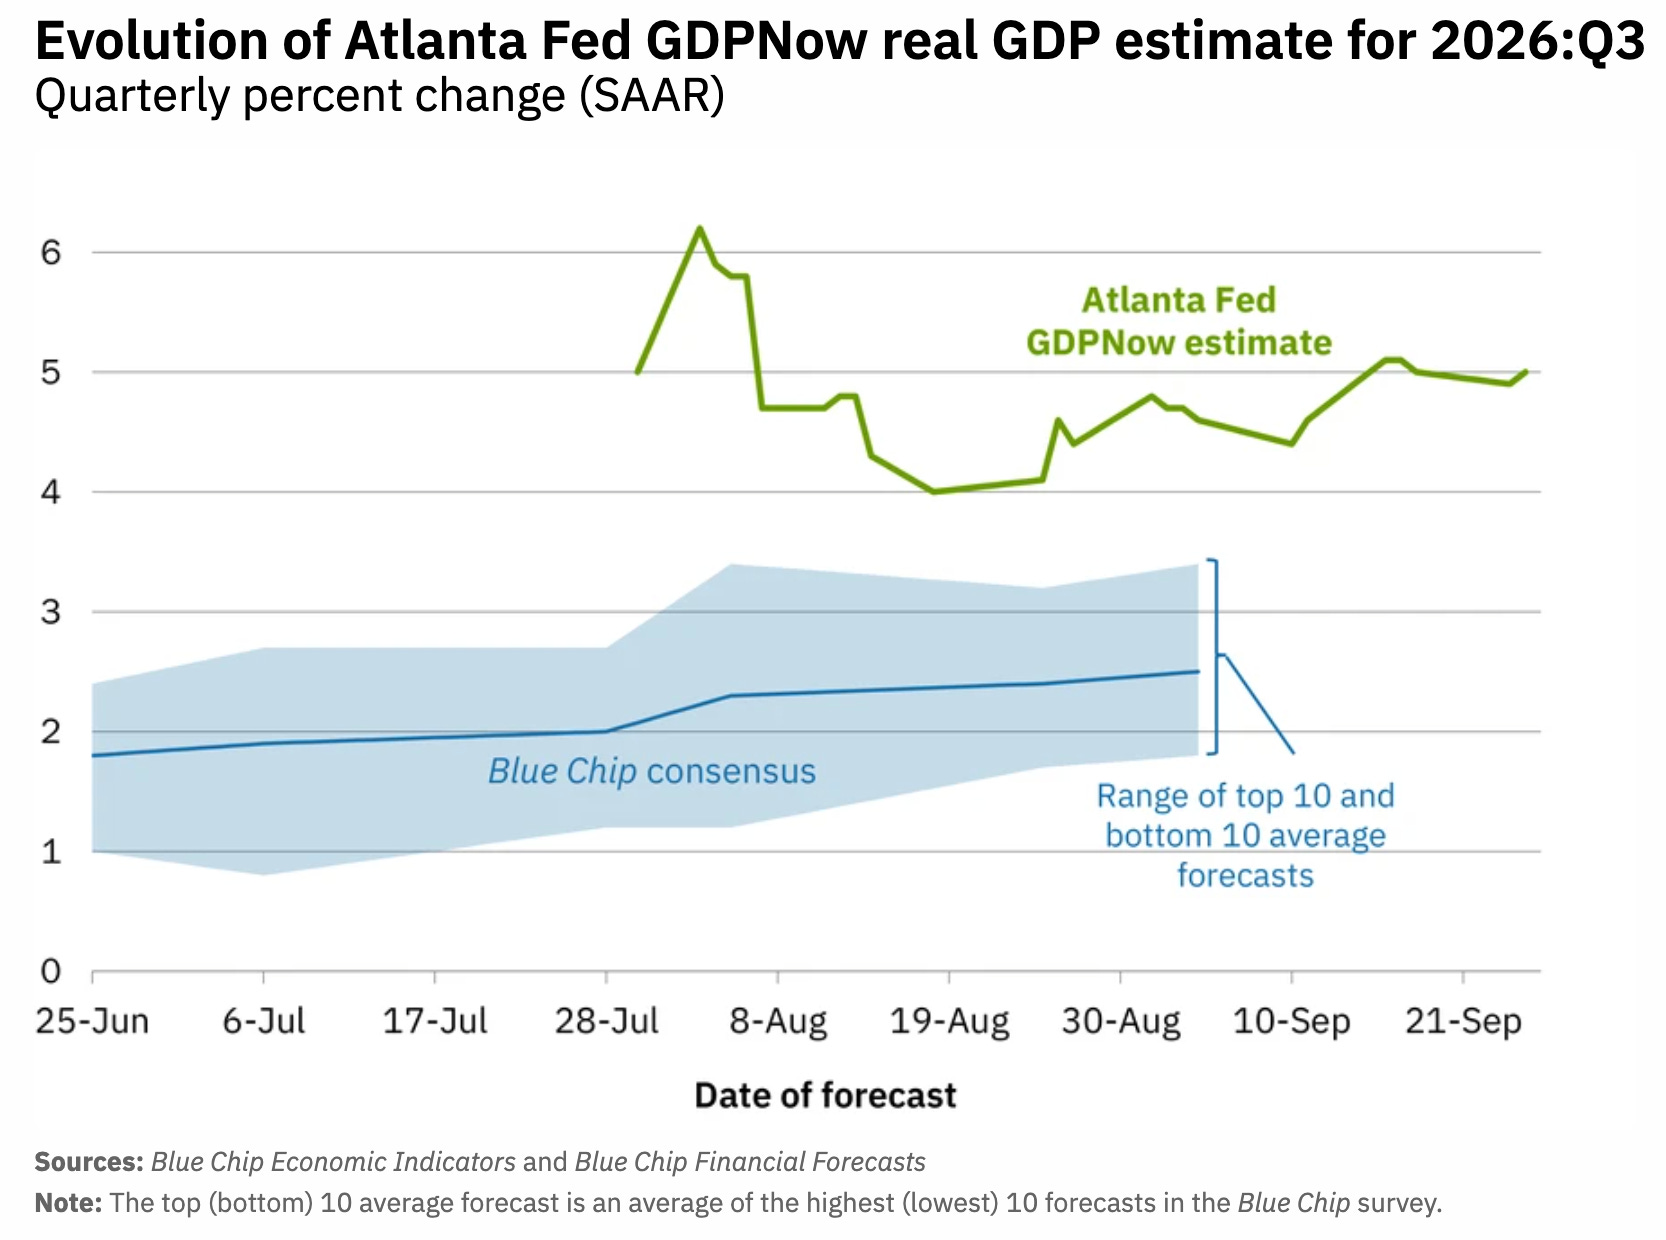
📈 Near-term GDP growth estimates are tracking positively. The Atlanta Fed’s GDPNow model sees real GDP growth rising at a 5.0% rate in Q3.
For more on GDP and the economy, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and Economic data can often be both ‘worse’ and ‘good’ 🌦️
Putting it all together 📋
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Personal spending activity remains at record levels. Core capex orders, which are a leading indicator of business spending, have been trending higher.
Growth rates have cooled: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like job openings and excess savings have faded. Job creation, while positive, is not as hot as it used to be. It has become harder to argue that growth is destiny.
Actions speak louder than words: We are in an odd period, given that the hard economic data decoupled from the soft sentiment-oriented data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data continues to hold up.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This came with strategic layoffs and investment in new equipment, including hardware powered by AI. These moves are resulting in positive operating leverage, which means a modest amount of sales growth — in the cooling economy — is translating to robust earnings growth.
Mind the ever-present risks: Of course, we should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyber attacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term volatility in the markets.
Investing is never a smooth ride: There’s also the harsh reality that economic recessions and bear markets are developments that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
Think long-term: For now, there’s no reason to believe there’ll be a challenge that the economy and the markets won’t overcome. The long game remains undefeated, and it’s a streak that long-term investors can expect to continue.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
Key insights about the stock market 📈
Here’s a roundup of some of TKer’s most talked-about paid and free newsletters about the stock market. All of the headlines are hyperlinked to the archived pieces.
10 truths about the stock market 📈
The stock market can be an intimidating place: It’s real money on the line, there’s an overwhelming amount of information, and people have lost fortunes in it very quickly. But it’s also a place where thoughtful investors have long accumulated a lot of wealth. The primary difference between those two outlooks is related to misconceptions about the stock market that can lead people to make poor investment decisions.
The makeup of the S&P 500 is constantly changing 🔀
Passive investing is a concept usually associated with buying and holding a fund that tracks an index. And no passive investment strategy has attracted as much attention as buying an S&P 500 index fund. However, the S&P 500 — an index of 500 of the largest U.S. companies — is anything but a static set of 500 stocks.

The key driver of stock prices: Earnings💰
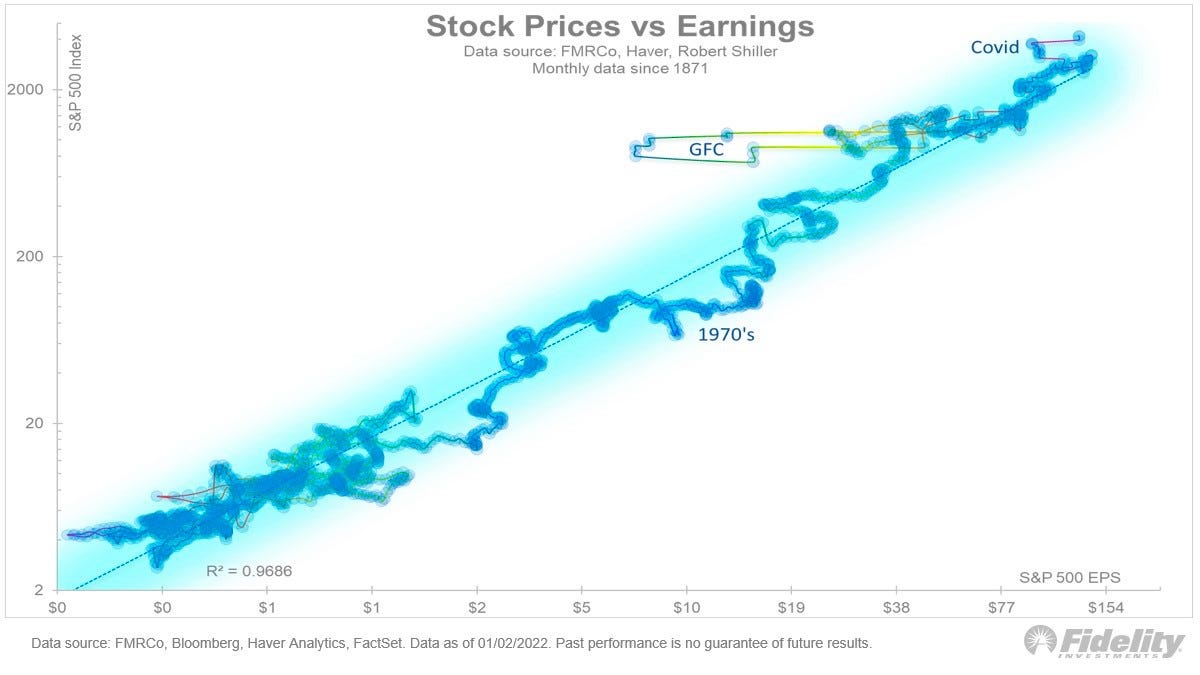
For investors, anything you can ever learn about a company matters only if it also tells you something about earnings. That’s because long-term moves in a stock can ultimately be explained by the underlying company’s earnings, expectations for earnings, and uncertainty about those expectations for earnings. Over time, the relationship between stock prices and earnings has a very tight statistical relationship.
Stomach-churning stock market sell-offs are normal🎢
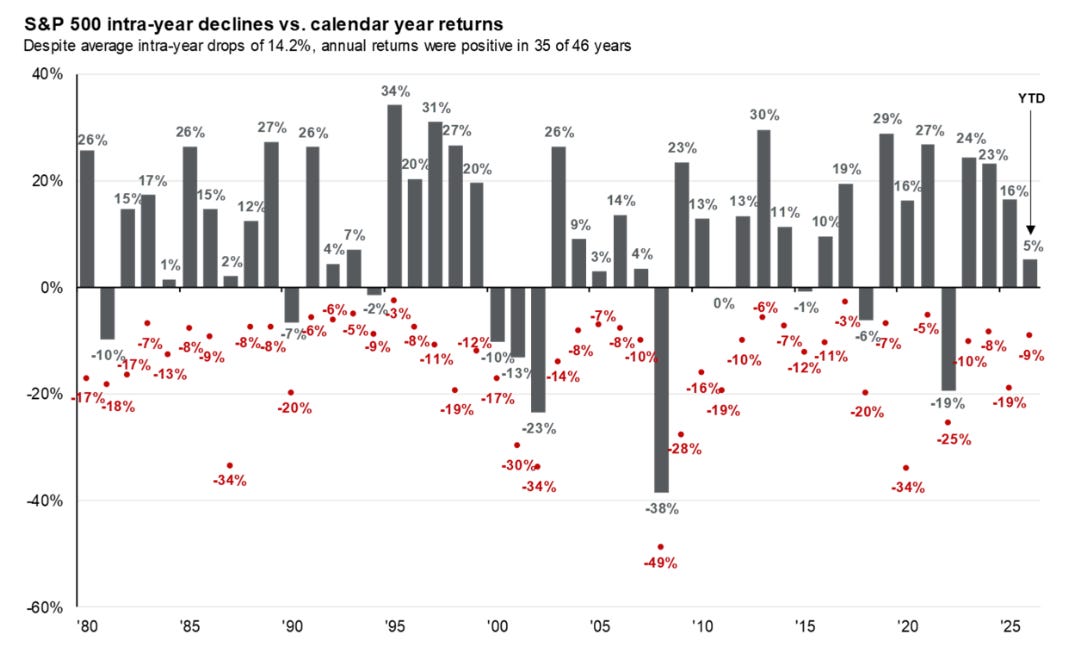
Investors should always be mentally prepared for some big sell-offs in the stock market. It’s part of the deal when you invest in an asset class that is sensitive to the constant flow of good and bad news. Since 1950, the S&P 500 has seen an average annual max drawdown (i.e., the biggest intra-year sell-off) of 14%.
How the stock market performed around recessions 📉📈
Every recession in history was different. And the range of stock performance around them varied greatly. There are two things worth noting. First, recessions have always been accompanied by a significant drawdown in stock prices. Second, the stock market bottomed and inflected upward long before recessions ended.

In the stock market, time pays ⏳
Since 1928, the S&P 500 has generated a positive total return more than 89% of the time over all five-year periods. Those are pretty good odds. When you extend the timeframe to 20 years, you’ll see that there’s never been a period where the S&P 500 didn’t generate a positive return.

What a strong dollar means for stocks 👑
While a strong dollar may be great news for Americans vacationing abroad and U.S. businesses importing goods from overseas, it’s a headwind for multinational U.S.-based corporations doing business in non-U.S. markets.

Stanley Druckenmiller’s No. 1 piece of advice for novice investors 🧐
…you don’t want to buy them when earnings are great, because what are they doing when their earnings are great? They go out and expand capacity. Three or four years later, there’s overcapacity and they’re losing money. What about when they’re losing money? Well, then they’ve stopped building capacity. So three or four years later, capacity will have shrunk and their profit margins will be way up. So, you always have to sort of imagine the world the way it’s going to be in 18 to 24 months as opposed to now. If you buy it now, you’re buying into every single fad every single moment. Whereas if you envision the future, you’re trying to imagine how that might be reflected differently in security prices.
Peter Lynch made a remarkably prescient market observation in 1994 🎯
Some event will come out of left field, and the market will go down, or the market will go up. Volatility will occur. Markets will continue to have these ups and downs. … Basic corporate profits have grown about 8% a year historically. So, corporate profits double about every nine years. The stock market ought to double about every nine years… The next 500 points, the next 600 points — I don’t know which way they’ll go… They’ll double again in eight or nine years after that. Because profits go up 8% a year, and stocks will follow. That’s all there is to it.
Warren Buffett’s ‘fourth law of motion’ 📉
Long ago, Sir Isaac Newton gave us three laws of motion, which were the work of genius. But Sir Isaac’s talents didn’t extend to investing: He lost a bundle in the South Sea Bubble, explaining later, “I can calculate the movement of the stars, but not the madness of men.” If he had not been traumatized by this loss, Sir Isaac might well have gone on to discover the Fourth Law of Motion: For investors as a whole, returns decrease as motion increases.
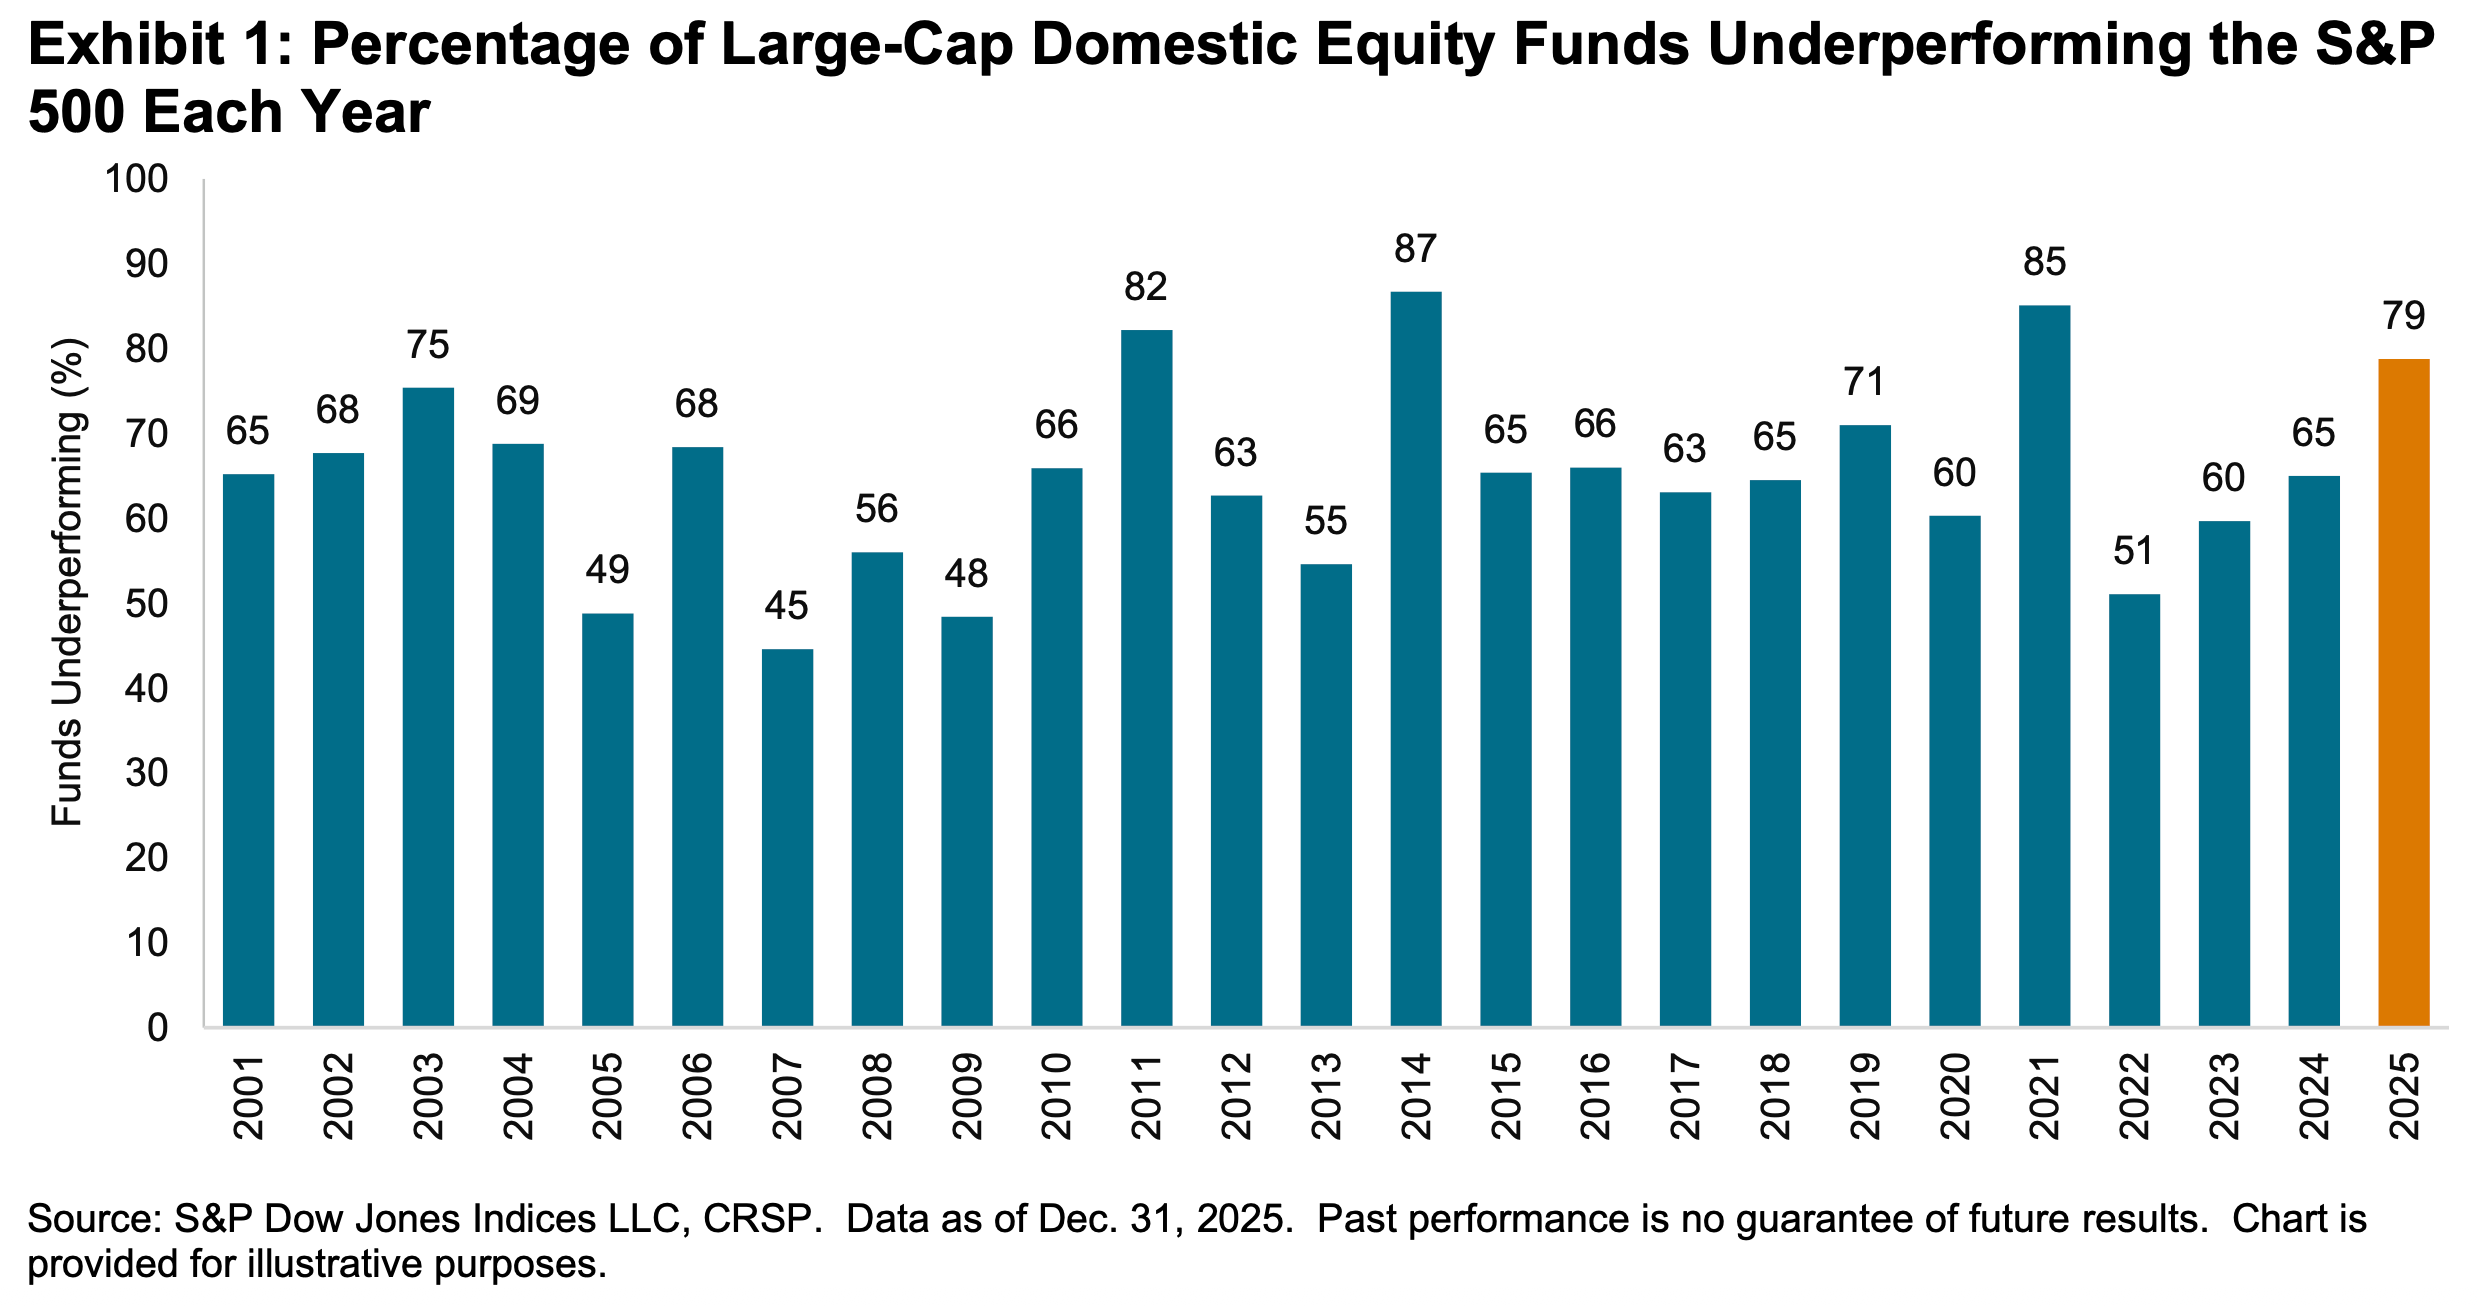
Most pros can’t beat the market 🥊
According to S&P Dow Jones Indices (SPDJI), 79% of U.S. large-cap equity fund managers underperformed the S&P 500 in 2025. As you stretch the time horizon, the numbers get even more dismal. Over three years, 67% underperformed. Over 5 years, 89% underperformed. And over 20 years, 93% underperformed. This 2025 performance was the 16th consecutive year in which the majority of fund managers in this category have lagged the index.
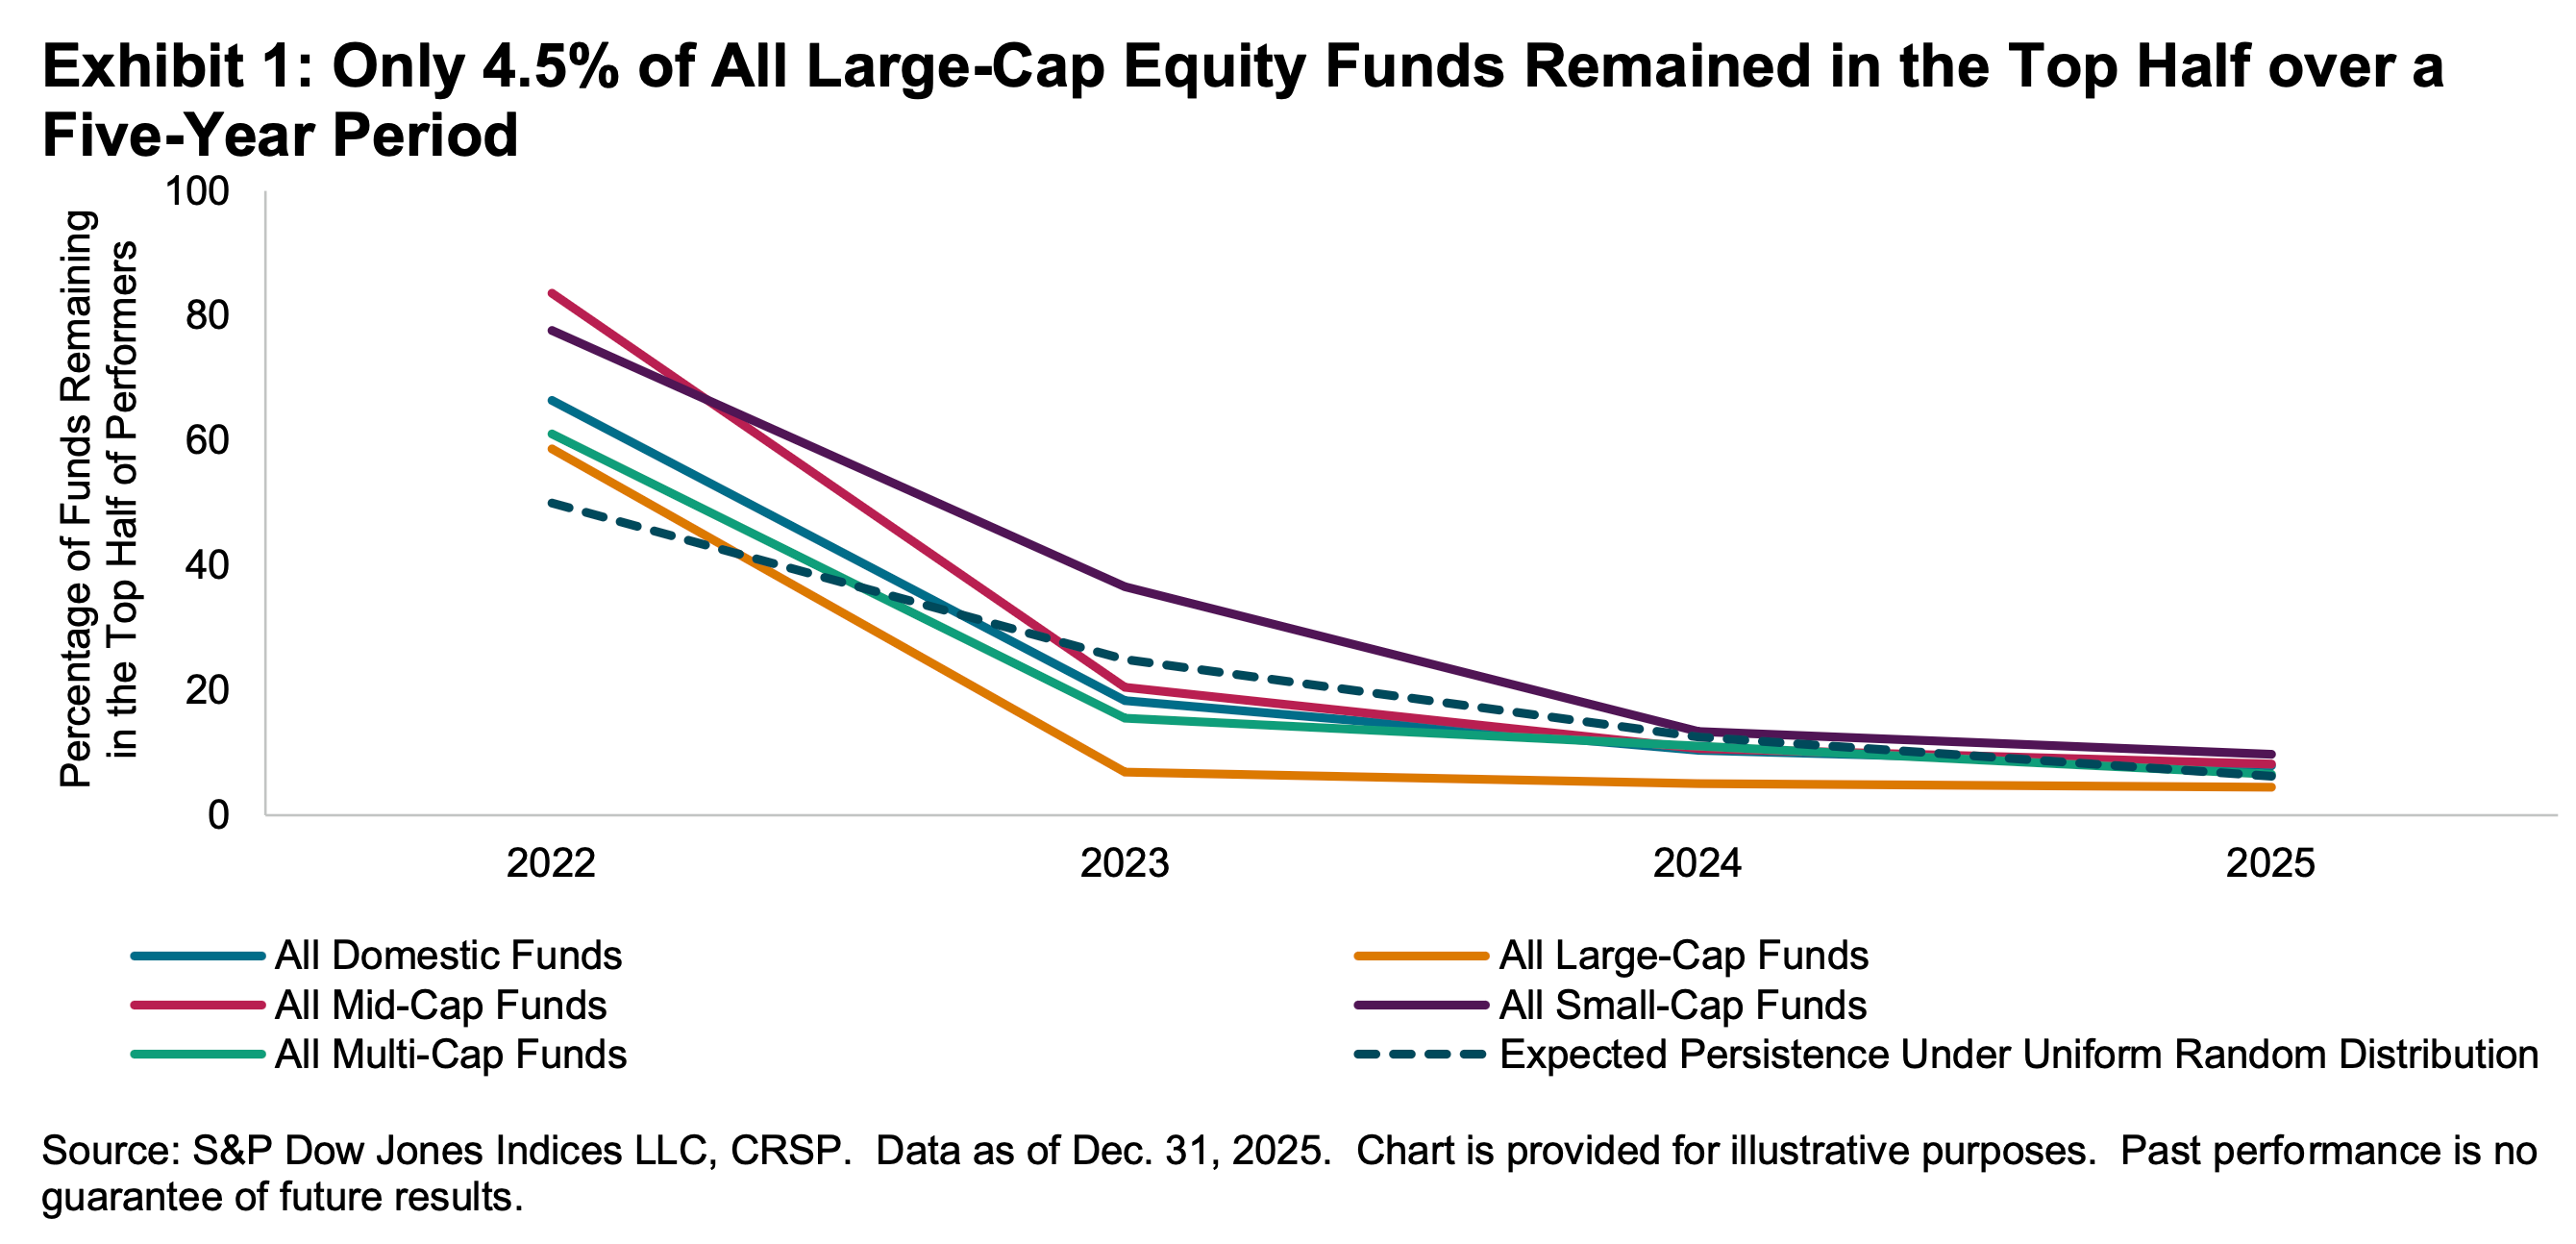
Proof that ‘past performance is no guarantee of future results’ 📊
Even if you are a fund manager who generated industry-leading returns in one year, history says it’s an almost insurmountable task to stay on top consistently in subsequent years. According to S&P Dow Jones Indices, of the 334 large-cap equity funds in the top half of performance in 2021, 58.7% remained at the top half in 2022. However, just 6.9% remained on top through 2023. Only 4.5% stayed on top in the five consecutive years through 2025.
It’s much more dismal when you raise the bar. Of the 164 large-cap equity funds in the top quartile in 2021, just 20.1% remained in that category in 2022. That percentage fell to literally 0.0% in 2023.
The odds are stacked against stock pickers 🎲
Picking stocks in an attempt to beat market averages is an incredibly challenging and sometimes money-losing effort. Most professional stock pickers aren’t able to do this consistently. One of the reasons for this is that most stocks don’t deliver above-average returns. According to S&P Dow Jones Indices, only 19% of the stocks in the S&P 500 outperformed the average stock’s return from 2001 to 2025. Over this period, the average return on an S&P 500 stock was 452%, while the median stock rose by just 59%.