Sure, the stock market is more like the economy than it’s like… a banana.
But in the context of a nuanced discussion of finance and macroeconomics, the stock market is not the economy.
Ritholtz Wealth Management’s Ben Carlson shared this helpful visual on Tuesday’s Animal Spirits podcast. The chart, published by JPMorgan Asset Management, shows a sector breakdown of GDP, employment, and the S&P 500 (which covers 80% of the U.S. stock market).
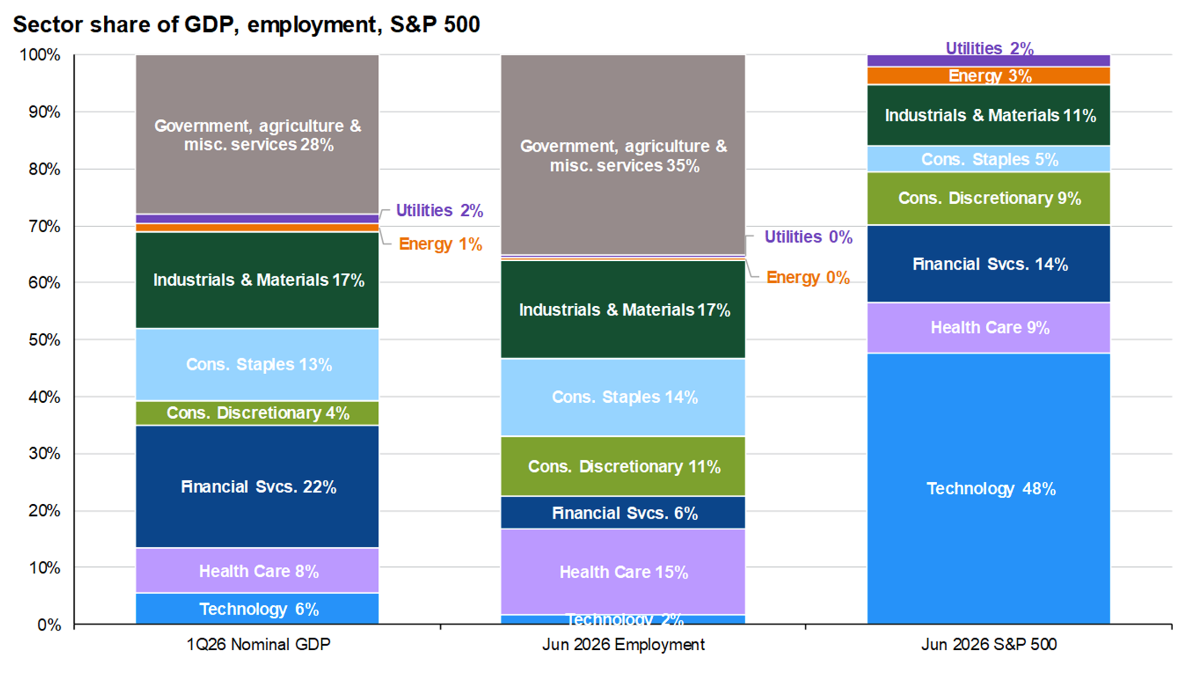
I have four observations about this discrepancy:
Government: The S&P consists exclusively of publicly traded corporations. GDP and employment, which cover the entire U.S. economy, include the extensive activities of the massive U.S. government.
Two angles on the economy: GDP includes only financial measures of the economy, so it doesn’t tell you much about the labor market directly. This is why the NBER’s definition of economic activity, which includes changes in employment, is arguably advantageous. That said, the sector breakdowns of GDP and employment are relatively similar.
International: This isn’t stated in the graphic, but S&P 500 companies generate about 30%-40% of their revenue outside of the U.S., which means a large share of the stock market reflects international economic activity. In the U.S. economy, you could argue this is sorta similar to the import and export activity conducted by U.S. businesses, but net trade is relatively small at about 3% of GDP.
Tech: One of the more glaring differences between the stock market and the economy is that the tech sector accounts for about half of the S&P, but a tiny share of GDP and employment. This is why the many headlines about tech layoffs in the financial press in recent years appeared to conflict with the broad labor market, which has been resilient during the period.
That said, the stock market and the economy are intertwined in countless ways. This is why the stock market often — but not always — struggles during recessions.
But you should be careful about jumping to conclusions about the stock market because of an alarming headline about the economy, and vice versa. Because the stock market is not the economy.
-
Related from TKer:
You don’t have to look outside U.S. stocks for international exposure 🌎
Why mass tech layoffs have little effect on total employment 💾
Review of the macro crosscurrents 🔀
📈The stock market rallied to all-time highs, with the S&P 500 setting an intraday high of 7,844.52 and a closing high of 7,818.93 on Tuesday. The index ended the week at 7,811.54, up 14.1% year-to-date. For market insights, check out the Stock Market tab at TKer. »
There were several notable data points and macroeconomic developments since our last review:
🎈 Inflation expectations heat up. From the New York Fed’s September Survey of Consumer Expectations: “Median inflation expectations increased by 0.3 percentage point to 3.9% at the one-year-ahead horizon and by 0.1 percentage point to 3.3% at the three-year-ahead horizon. Median inflation expectations were unchanged at the five-year-ahead horizon at 3.0%. This is the highest reading for the one-year-ahead inflation expectations since May 2023.”
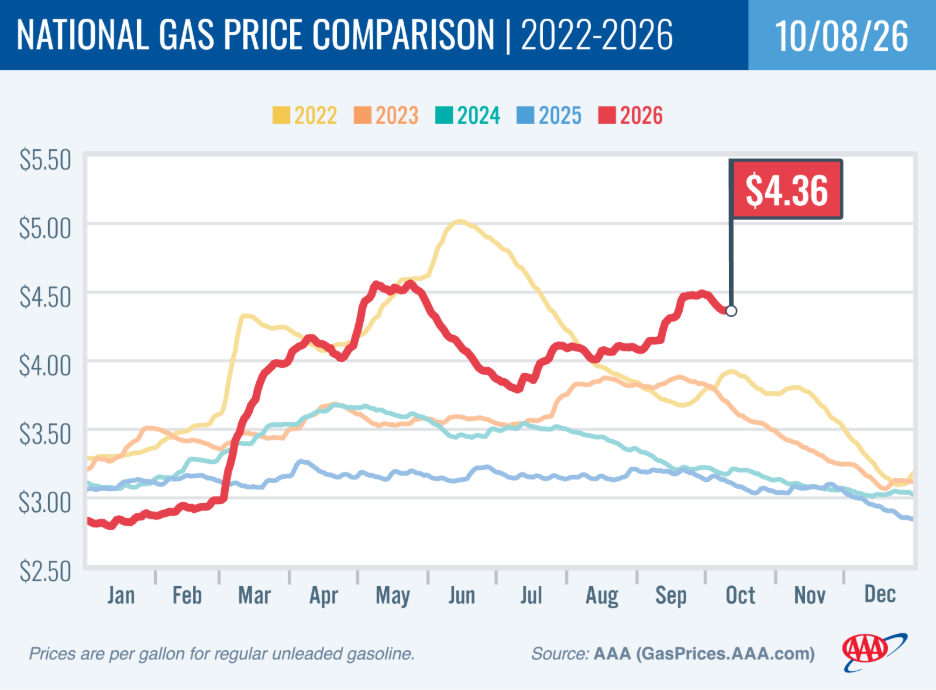
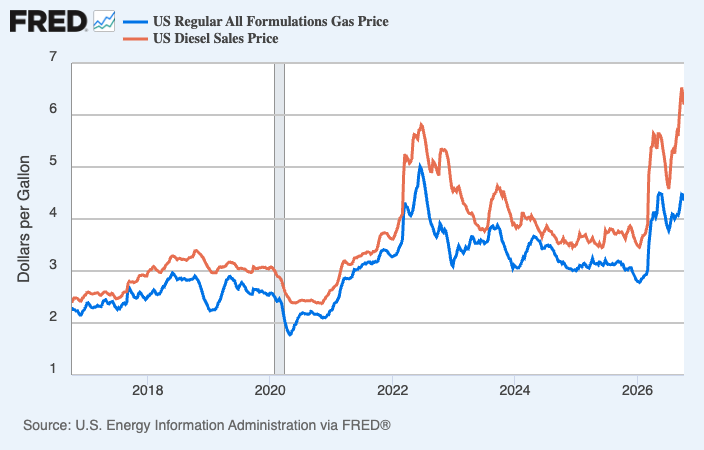
⛽️ Gas prices tick lower, but remain high. From AAA: “Gas prices remain the highest they’ve ever been for this time of year. Even though the national average dropped 5 cents this past week to $4.36, pump prices remain at record highs for autumn. This is the first year the national average has been above $4 per gallon in October. After dipping into the $80 per barrel range for several days, crude oil is back above $90 per barrel. Hurricane Isaias is another factor that could affect gas prices if oil production and refineries in the region are impacted.”
Here’s a longer-term look at the trajectory of gas and diesel prices, as tracked by the EIA.
For more on energy prices, read: Our love-hate relationship with rising oil prices in charts 💔🛢️📊
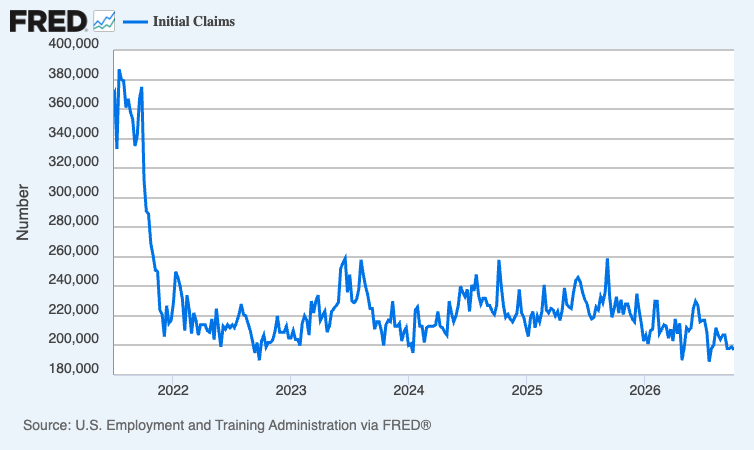
💼 New unemployment insurance claims, total ongoing claims remain low. Initial claims for unemployment benefits ticked down to 197,000 during the week ending Oct. 3, down from 199,000 the week prior. This metric remains at levels historically associated with economic growth.
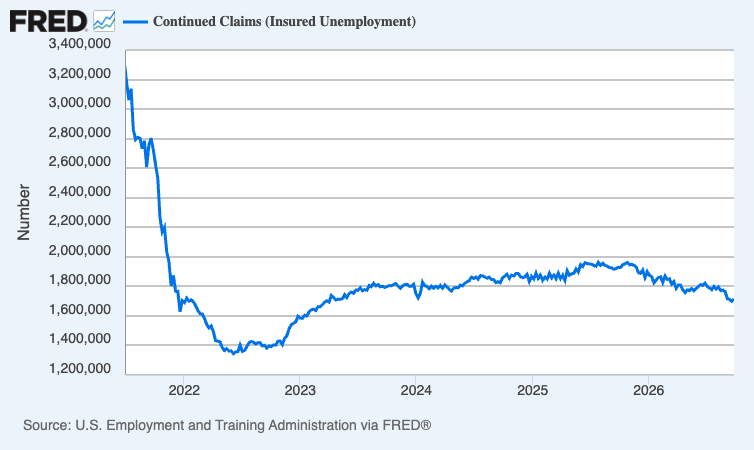
Insured unemployment, which captures those who continue to claim unemployment benefits, ticked up to 1.72 million during the week ending Sept. 26.
For more on the labor market, read: Why mass tech layoffs have little effect on total employment 💾
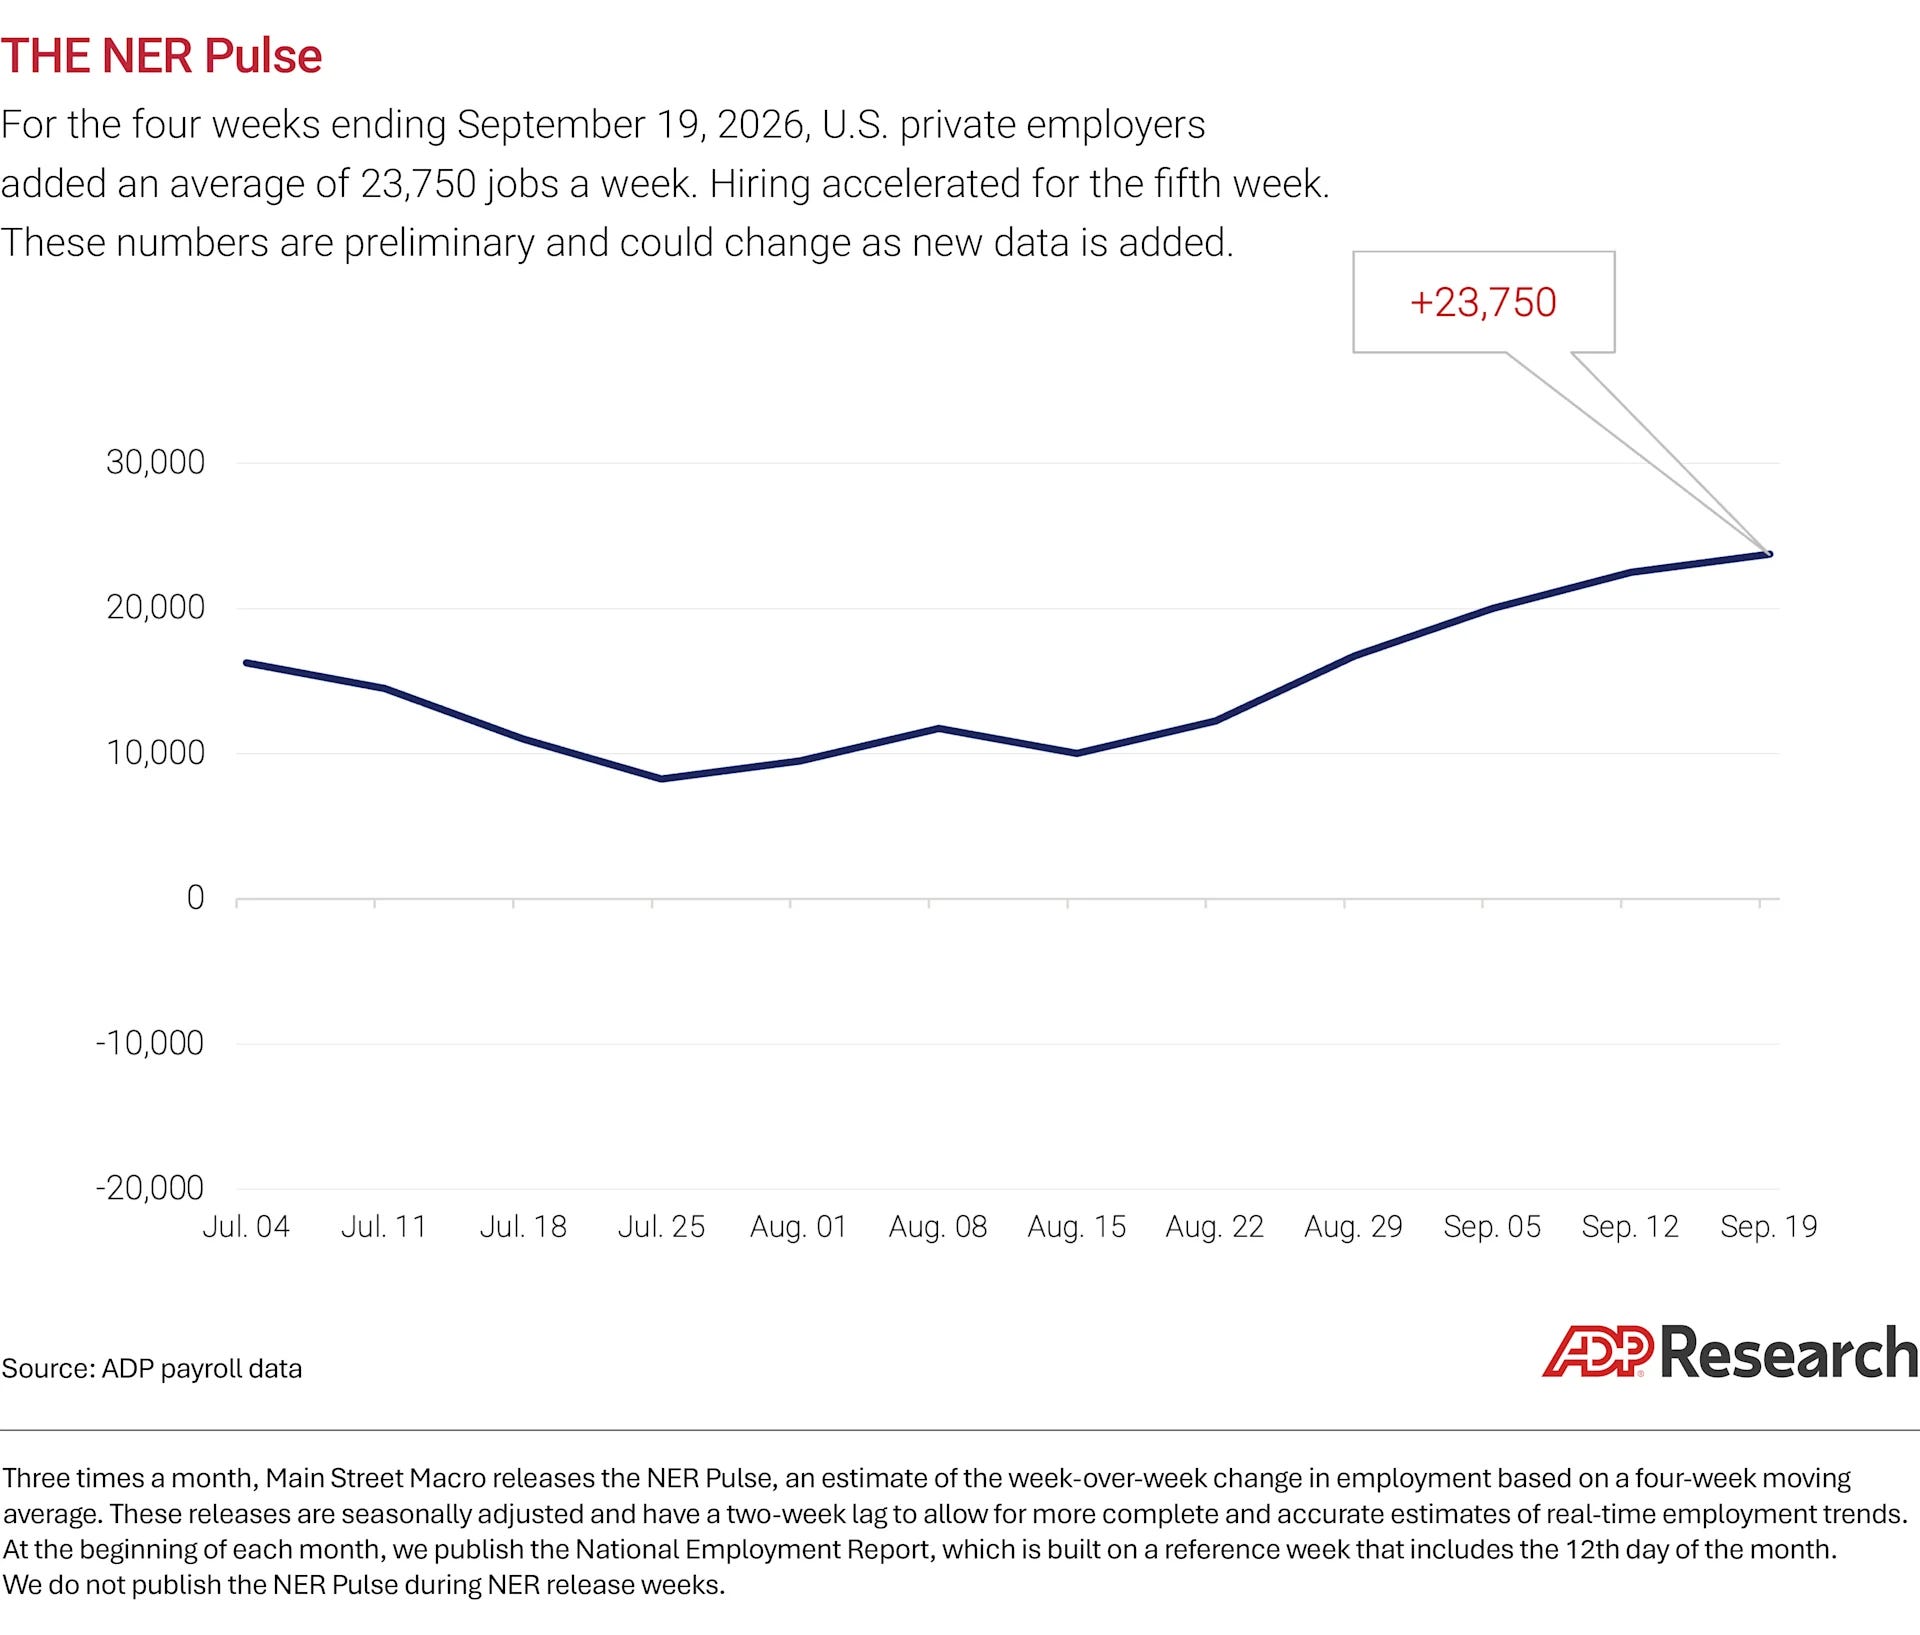
🤔 Recent private job growth is picking up. According to payroll processor ADP, private U.S. employers added 23,750 jobs in the four weeks ending Sept. 19.
For more on the labor market, read: Things are looking up in the labor market 👍
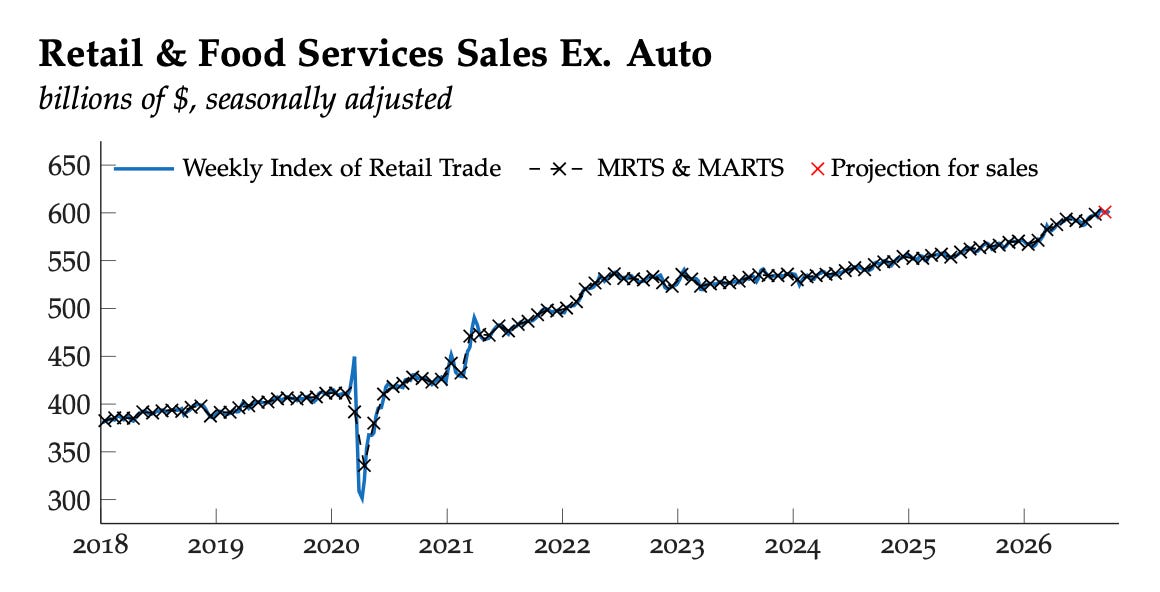
🛍️ Retail sales may have cooled last month. According to the Chicago Fed’s Advance Retail Trade Summary, sales rose 0.4% in September. Adjusted for inflation, sales were down 0.7% from the prior period.
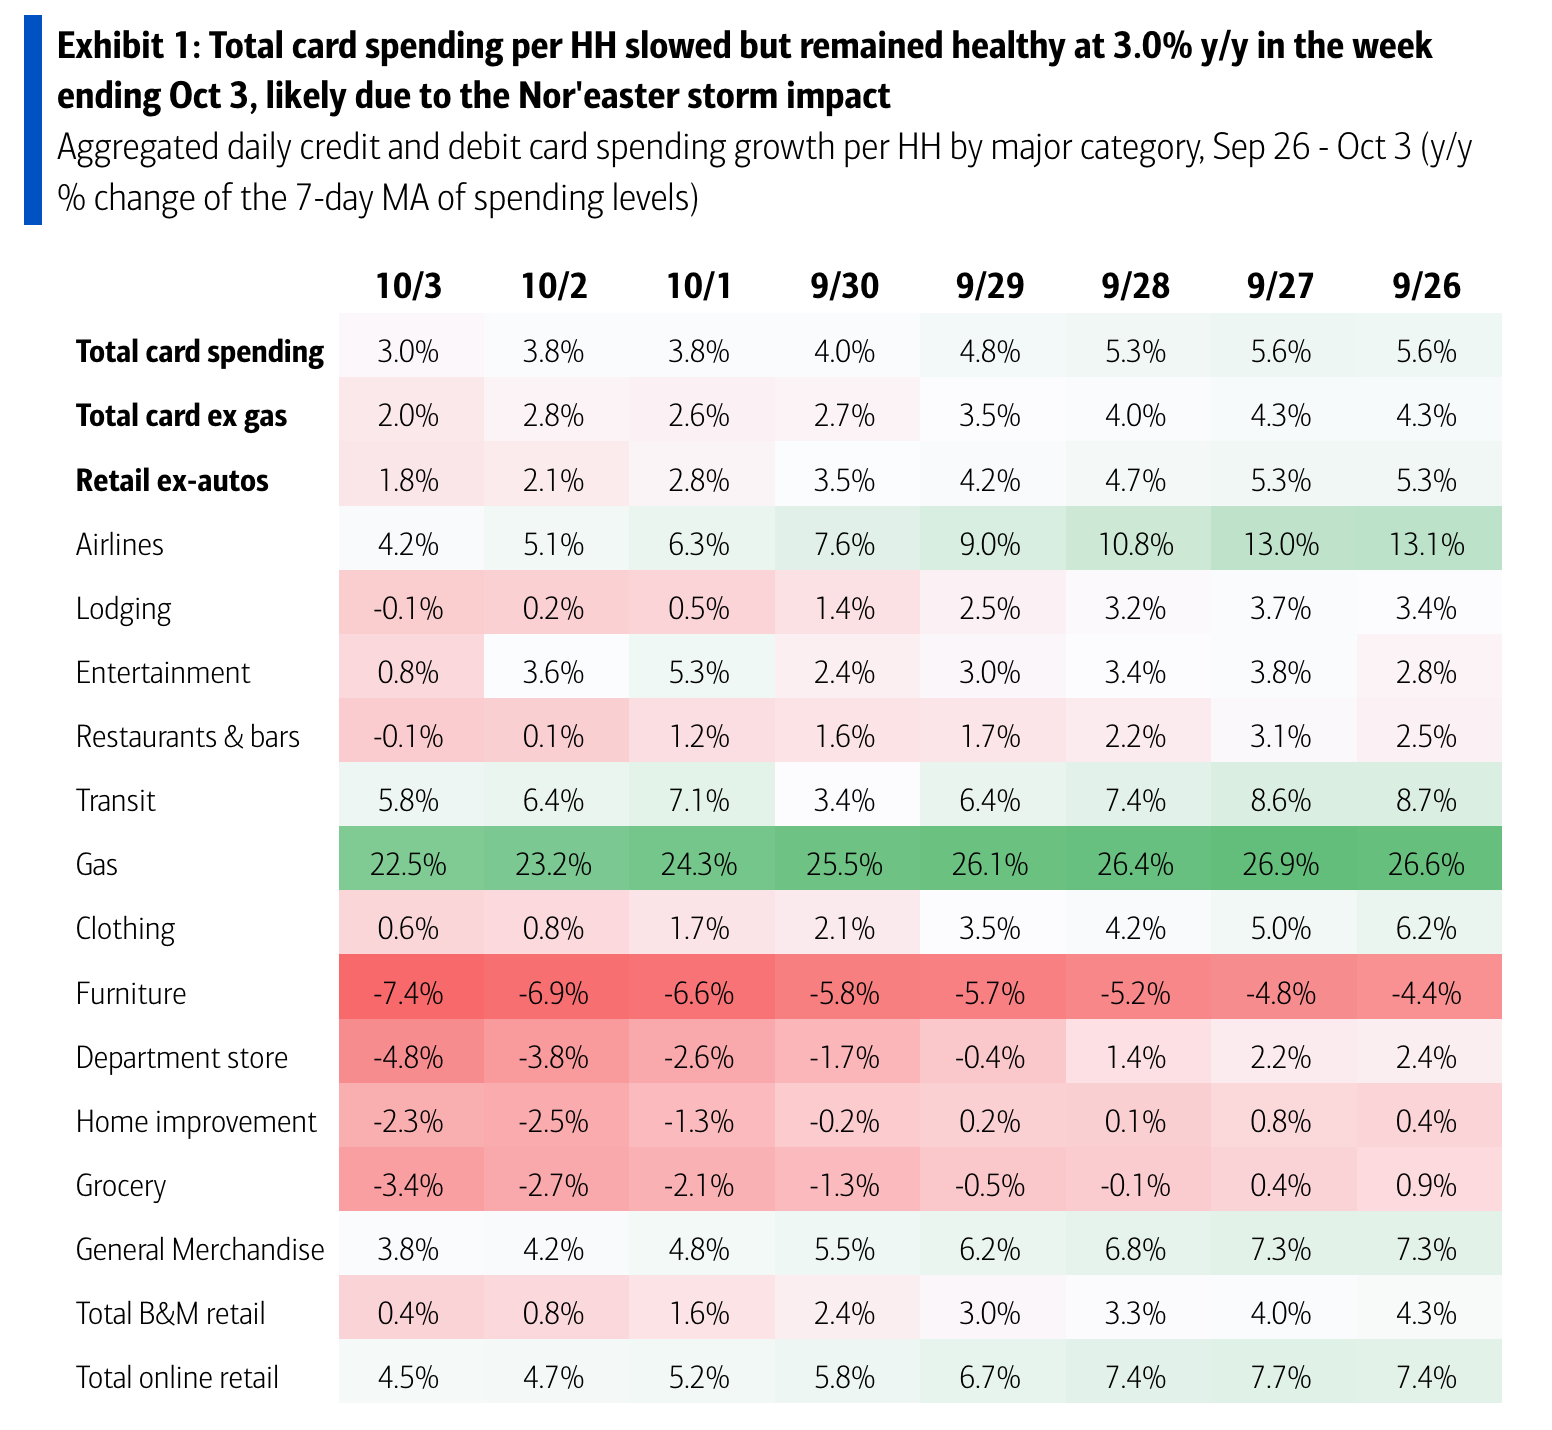
💳 Card spending data is holding up. From BofA: “Total card spending per HH was up 3.0% y/y in the week ending Oct 3, according to BAC aggregated credit & debit card data. The Nor’easter storm likely contributed to the broad-based moderation in spending growth. Lower-income spending growth continued to outpace higher-income in the week ending Oct 3.”
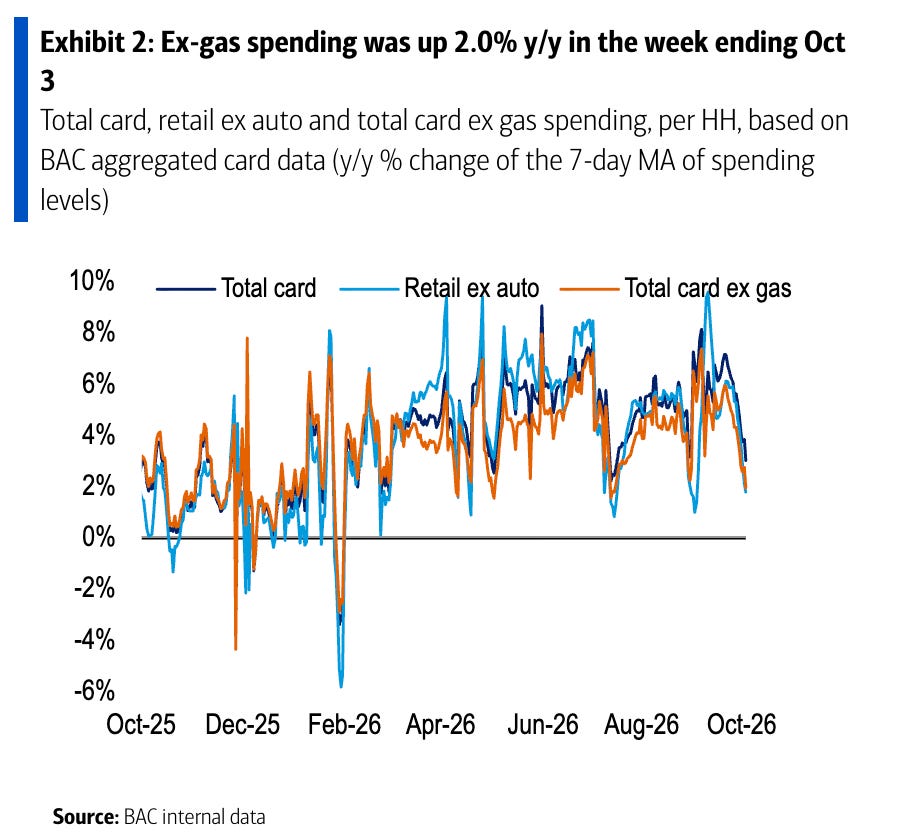
Consumer spending data has looked a lot better than consumer sentiment readings. For more on this contradiction, read: We’re taking that vacation whether we like it or not 🛫 and Household finances are both ‘worse’ and ‘good’ 🌦️
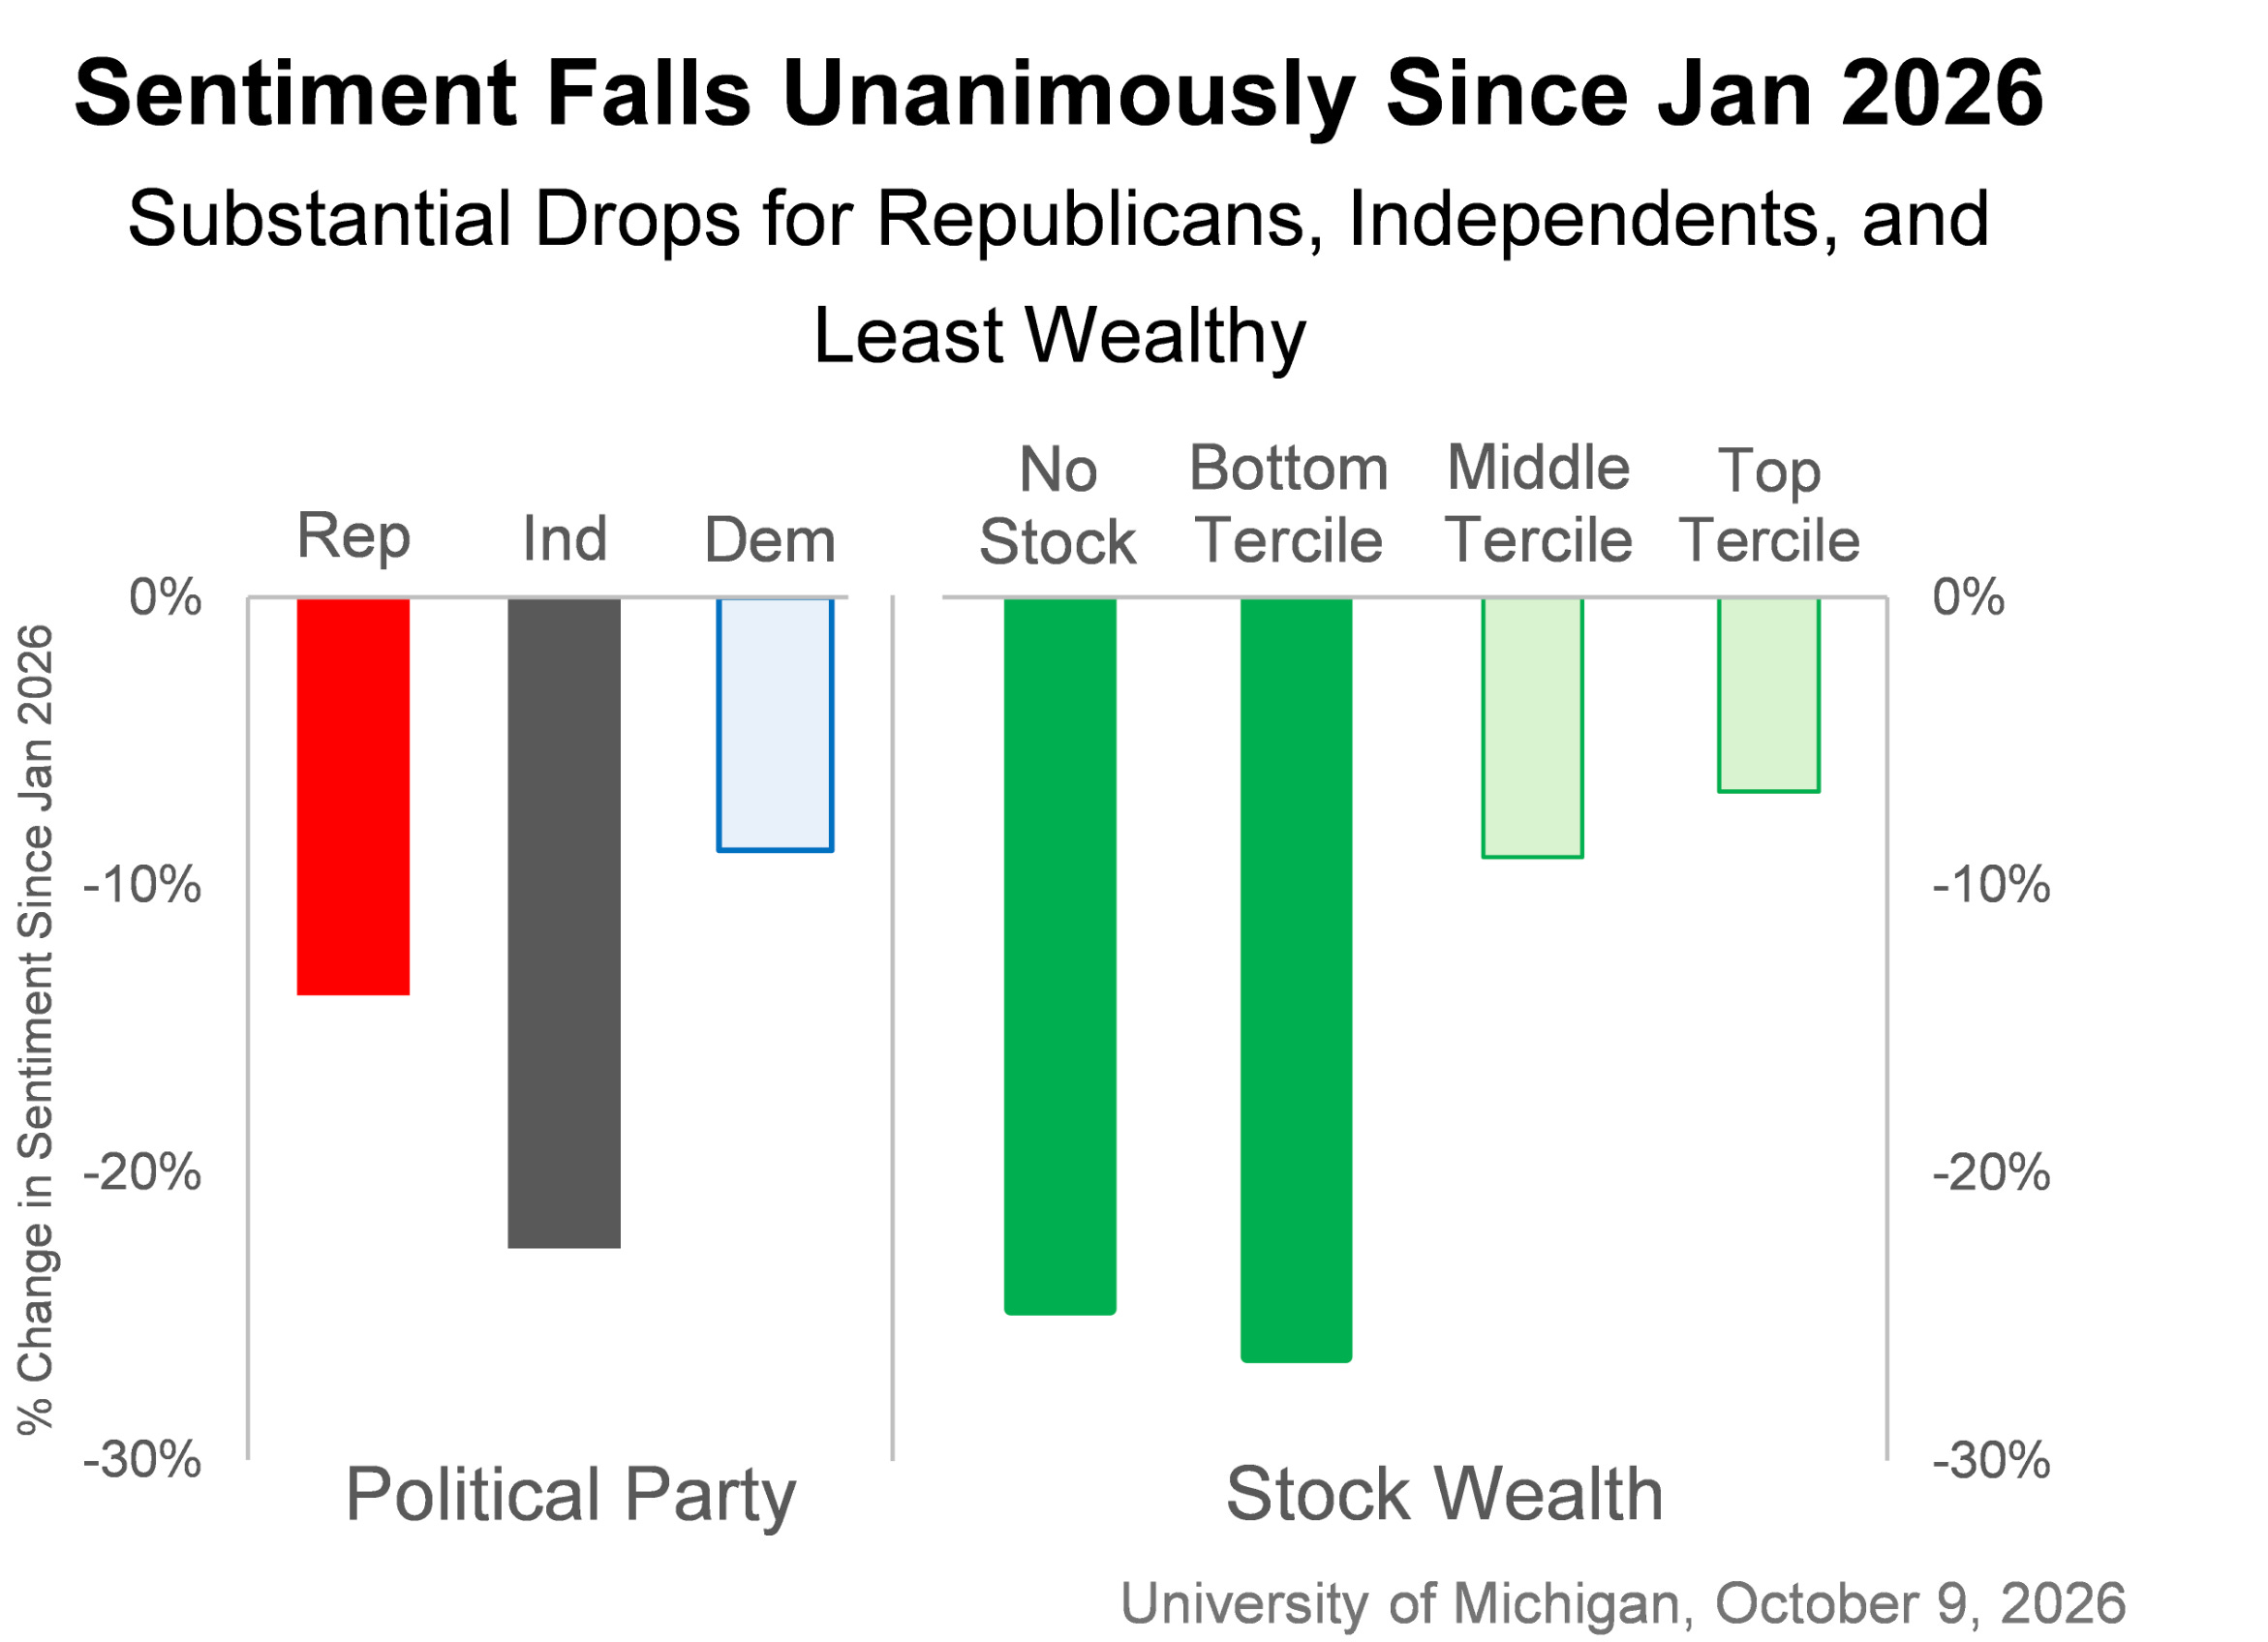
👎 Consumer vibes are in the dumps. From the University of Michigan’s October Surveys of Consumers: “While year-ahead expectations for personal finances and business conditions crept up slightly, buying conditions for durables plummeted amid high prices and borrowing costs.”
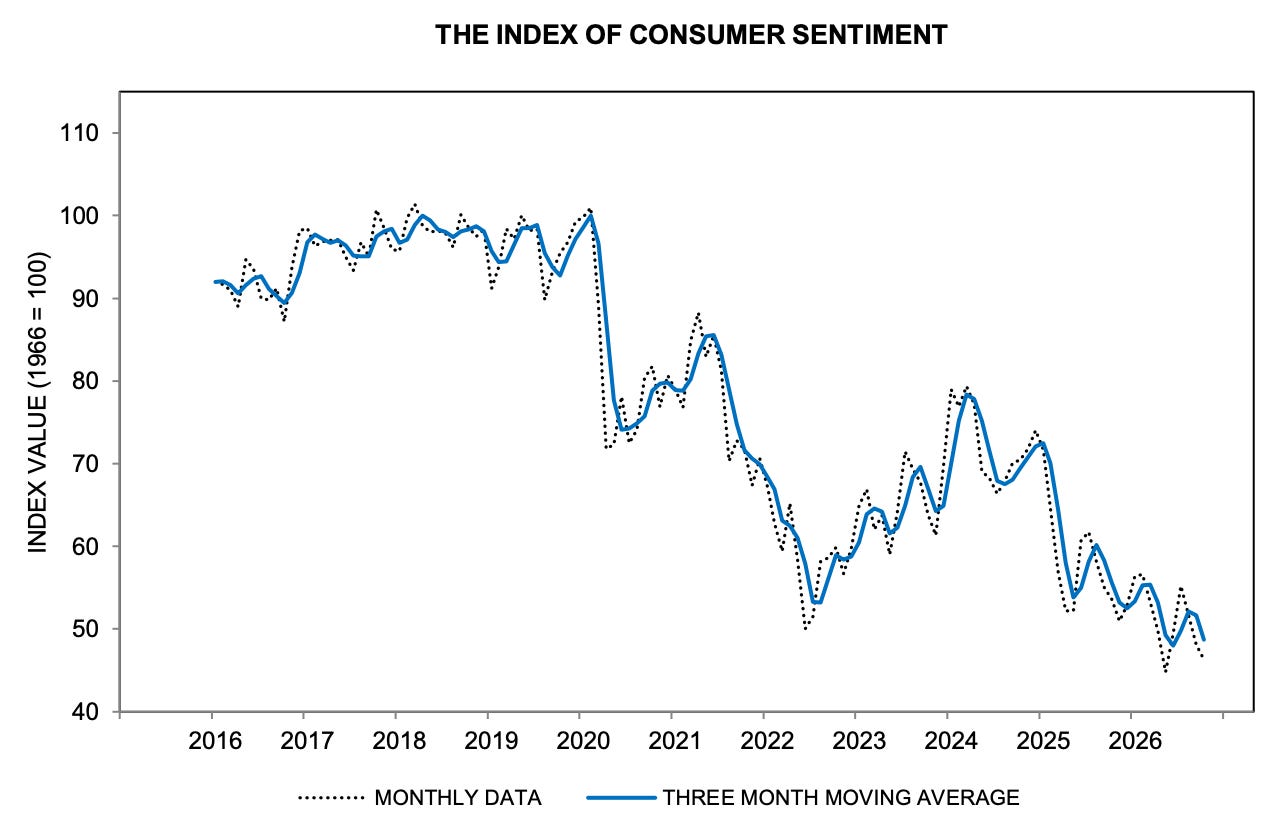
More from the report: “Increases in sentiment among Democrats and Republicans were offset by a decline among independents this month. Overall, sentiment for lower-income consumers and those with smaller stock porfolios dropped steeply this month, groups that have fewer resources to weather increases in prices. Frustration over cost-of-living continues to mount, as consumers across the political spectrum believe that the trajectory of the economy has weakened since the beginning of the year.“
For more on consumer sentiment, read: What consumers do > what consumers say 🙊
🏠 Mortgage rates rise. According to Freddie Mac, the average 30-year fixed-rate mortgage rose to 7.4%, up from 7.28% last week. This is the highest average rate since Nov. 2023.
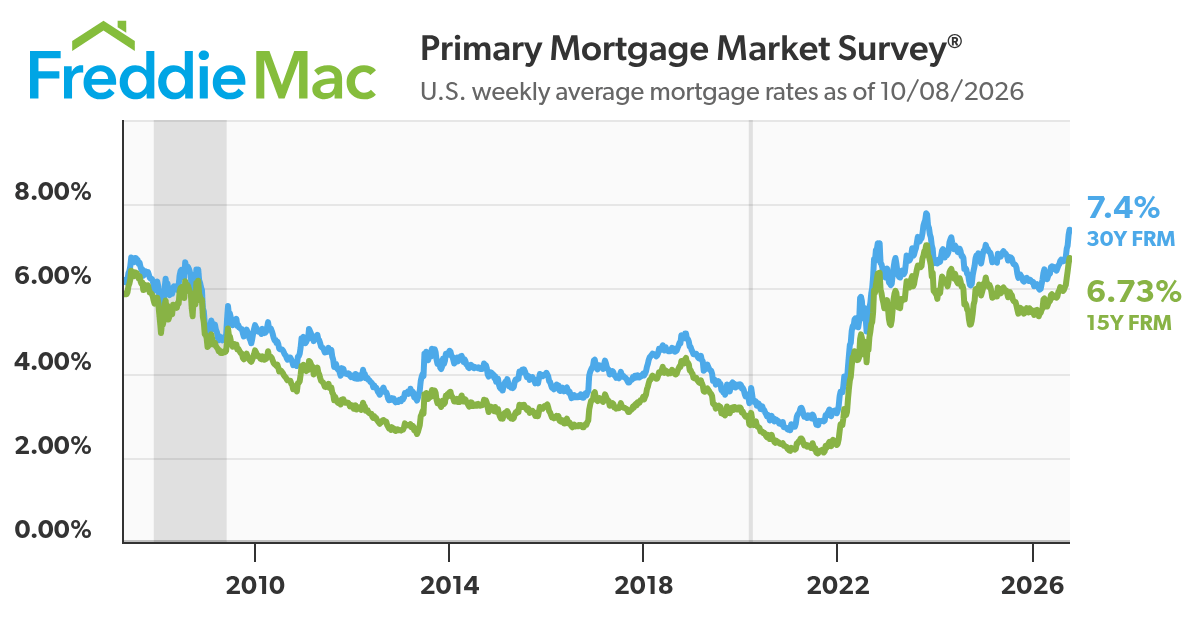
As of Q2, there were 149.5 million housing units in the U.S., of which 87.0 million were owner-occupied and about 40% were mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the weekly movements in home prices or mortgage rates.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
⌨️ Services activity surveys signal growth. From S&P Global’s September U.S. Services PMI: “September has seen US business growth surge to its highest for over five years, with rising demand and improved optimism encouraging firms to take on workers at a pace not seen for over four years. Combined with the encouragingly solid manufacturing PMI, the strong service sector expansion points to economic growth of around 4% in the third quarter and 5% in September alone, the latter hinting at accelerating momentum into the fourth quarter. New orders and backlogs of work are rising at increased rates and growth expectations have recovered to a one-year high, adding to the sense of an economy picking up further pace in the near term. Tech companies are reporting by far the strongest growth but the rising tide is now lifting all boats as far as the major sectors are concerned, with accelerating growth also reported for consumer-facing businesses as well as industrials and healthcare, alongside sustained solid growth in financial services.”
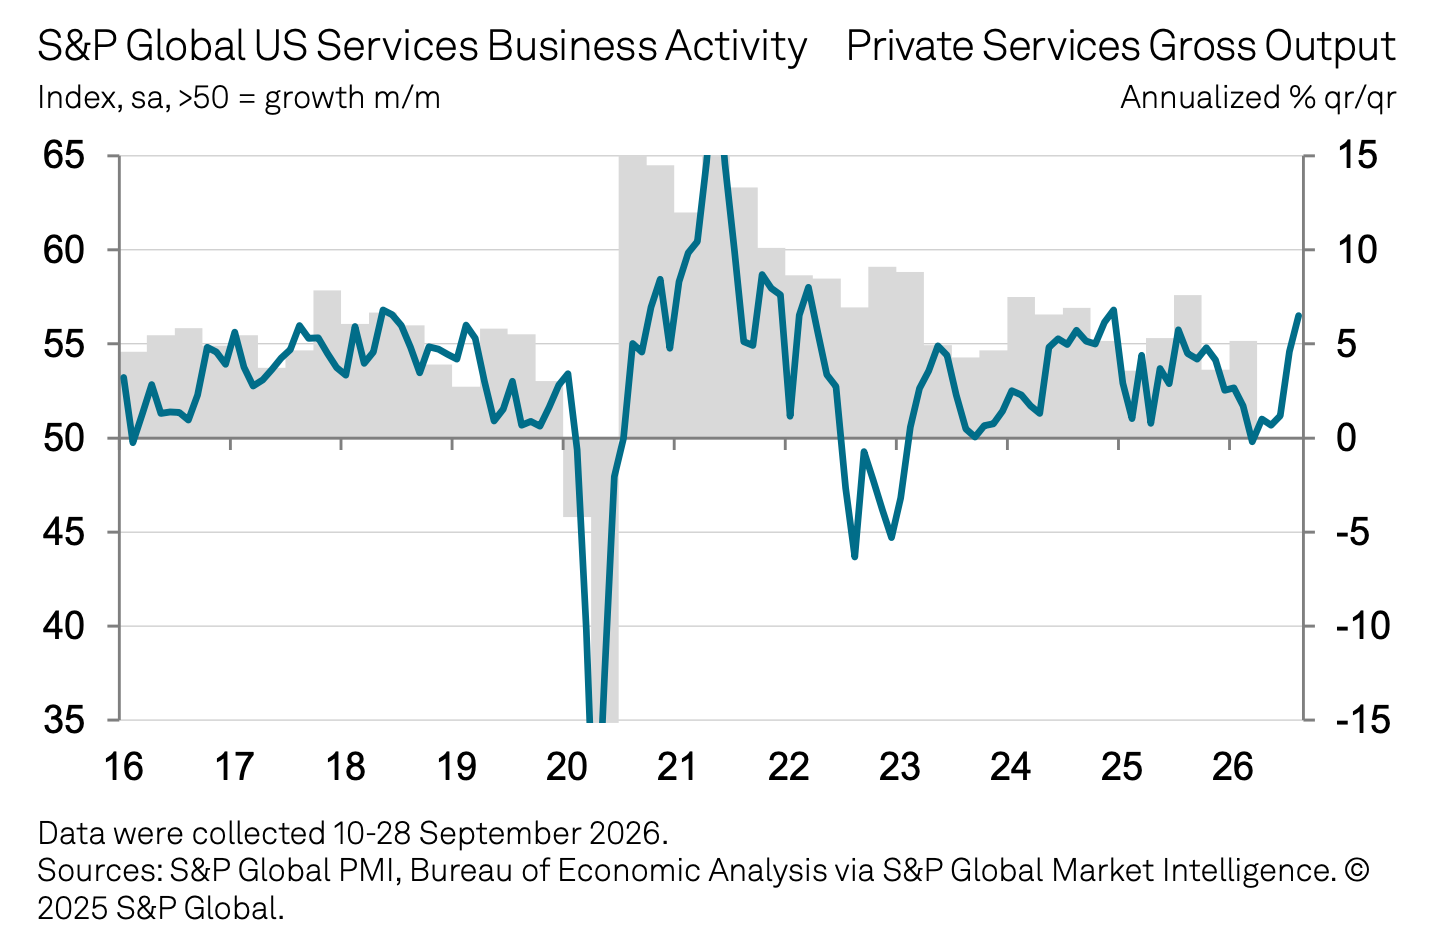
The September ISM Services PMI signaled growth, but at a cooler pace.
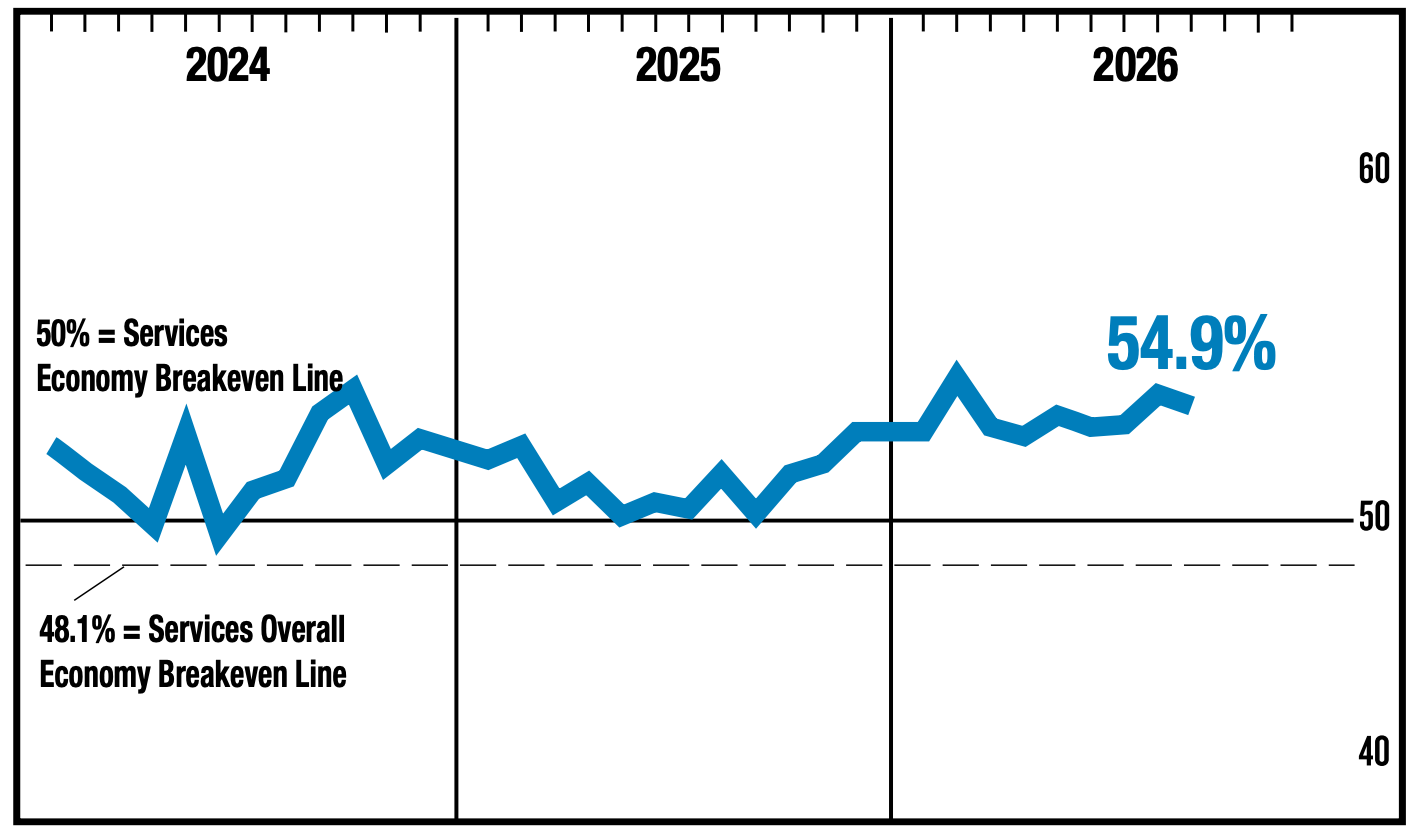
Keep in mind that during times of perceived stress, soft survey data tends to be more exaggerated than actual hard data.
For more on this, read: What businesses do > what businesses say 🙊 and 4 sometimes-conflicting ways I’m thinking about the economy 😬😞😎🙃
📈 Near-term GDP growth estimates are tracking positively. The Atlanta Fed’s GDPNow model sees real GDP growth rising at a 3.6% rate in Q3.
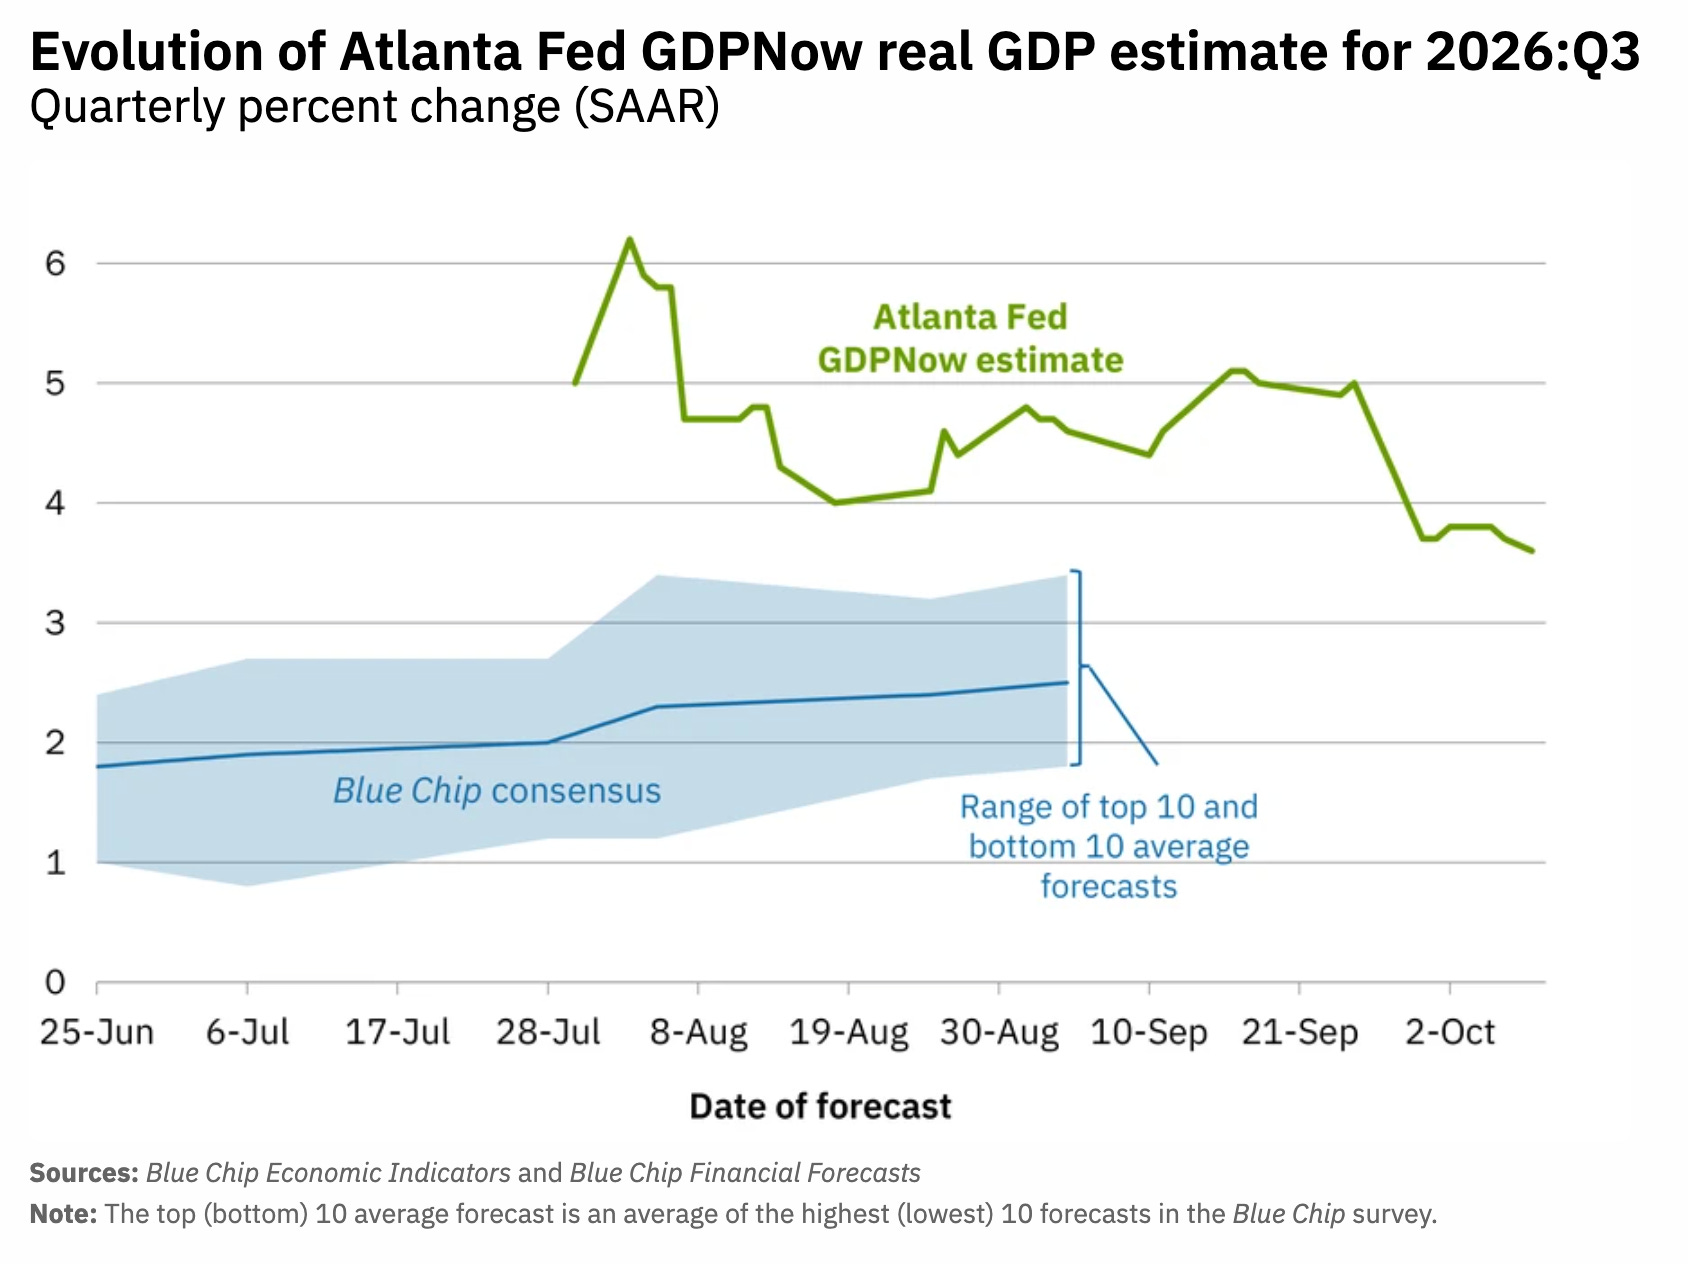
For more on GDP and the economy, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and Economic data can often be both ‘worse’ and ‘good’ 🌦️
Putting it all together 📋
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Personal spending activity remains at record levels. Core capex orders, which are a leading indicator of business spending, have been trending higher.
Growth rates have cooled: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like job openings and excess savings have faded. Job creation, while positive, is not as hot as it used to be. It has become harder to argue that growth is destiny.
Actions speak louder than words: We are in an odd period, as hard economic data has decoupled from soft, sentiment-driven data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data holds up.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This included strategic layoffs and investment in new equipment, including AI-powered hardware. These moves are driving positive operating leverage, meaning modest sales growth — in the cooling economy — translates into robust earnings growth.
Mind the ever-present risks: We should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyberattacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term market volatility.
Investing is never a smooth ride: Economic recessions and bear markets are harsh realities that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
Think long-term: For now, there’s no reason to believe the economy and the markets will face a challenge they can’t overcome. The long game remains undefeated, and long-term investors can expect that streak to continue.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
Key insights about the stock market 📈
Here’s a roundup of some of TKer’s most talked-about paid and free newsletters about the stock market. All of the headlines are hyperlinked to the archived pieces.
10 truths about the stock market 📈
The stock market can be intimidating: It’s real money on the line, the information is overwhelming, and people can lose fortunes very quickly. But it’s also where thoughtful investors have long accumulated wealth. The main difference between those two outlooks comes down to misconceptions about the stock market that can lead people to make poor investment decisions.
The makeup of the S&P 500 is constantly changing 🔀
Passive investing usually means buying and holding a fund that tracks an index. And no passive investment strategy has attracted as much attention as buying an S&P 500 index fund. However, the S&P 500 — an index of 500 of the largest U.S. companies — is anything but a static set of 500 stocks.

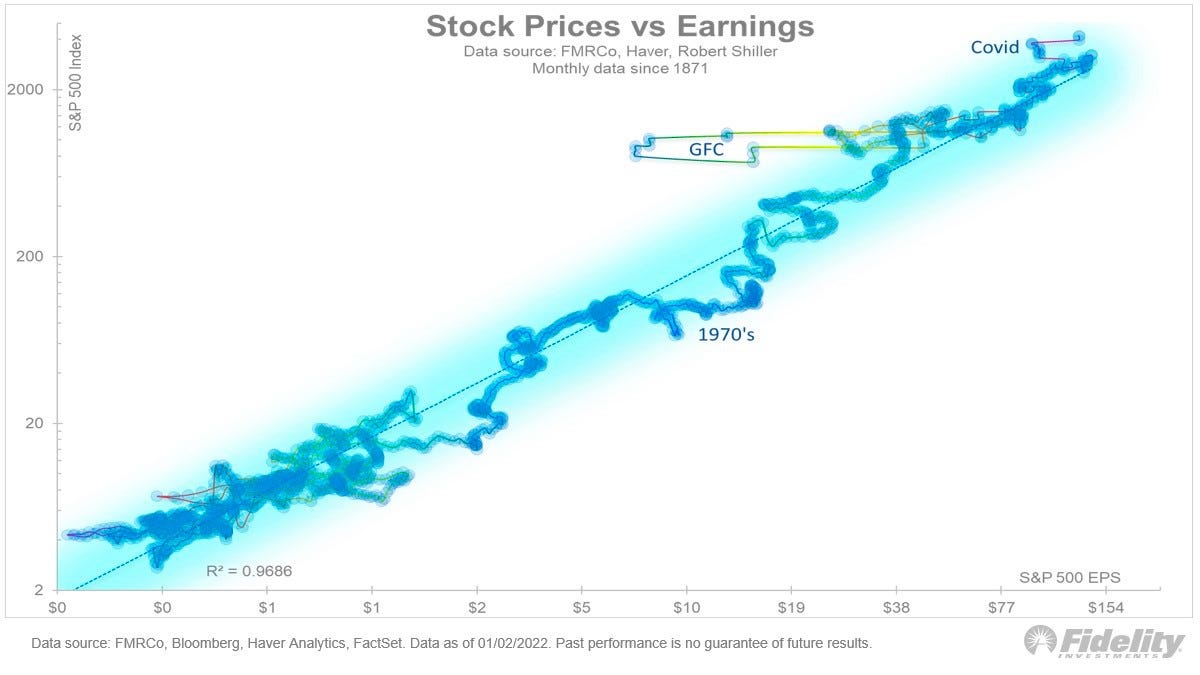
The key driver of stock prices: Earnings💰
For investors, anything you can ever learn about a company matters only if it also tells you something about earnings. That’s because a stock's long-term moves can ultimately be explained by the underlying company’s earnings, earnings expectations, and uncertainty about those expectations. Over time, stock prices and earnings have a very tight statistical relationship.
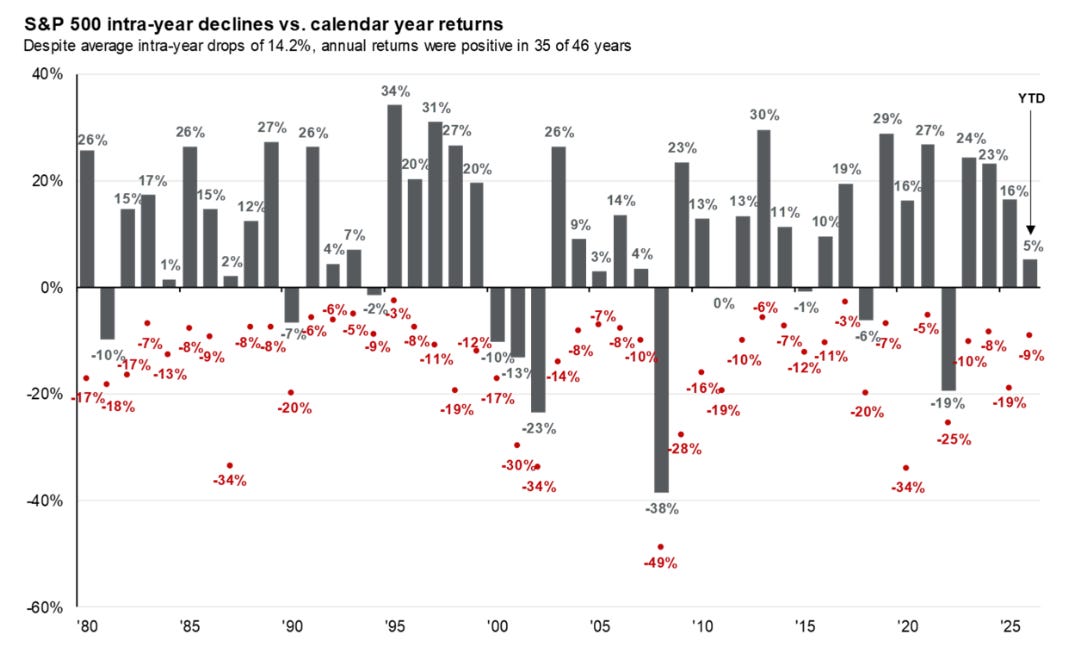
Stomach-churning stock market sell-offs are normal🎢
Investors should always be mentally prepared for major stock market sell-offs. It’s part of the deal when you invest in an asset class that is sensitive to the constant flow of good and bad news. Since 1950, the S&P 500 has averaged a max annual drawdown (i.e., the biggest intra-year sell-off) of 14%.
How the stock market performed around recessions 📉📈
Every recession in history was different. And stock performance around them varied widely. There are two things worth noting. First, recessions have always been accompanied by a significant drawdown in stock prices. Second, the stock market bottomed and inflected upward long before recessions ended.

In the stock market, time pays ⏳
Since 1928, the S&P 500 has generated a positive total return in more than 89% of five-year periods. Those are pretty good odds. When you extend the timeframe to 20 years, you’ll see that the S&P 500 has never had a period where it didn’t generate a positive return.

What a strong dollar means for stocks 👑
While a strong dollar may be great news for Americans vacationing abroad and U.S. businesses importing goods from overseas, it’s a headwind for multinational U.S.-based corporations doing business in non-U.S. markets.

Stanley Druckenmiller’s No. 1 piece of advice for novice investors 🧐
…you don’t want to buy them when earnings are great, because what are they doing when their earnings are great? They go out and expand capacity. Three or four years later, there’s overcapacity and they’re losing money. What about when they’re losing money? Well, then they’ve stopped building capacity. So three or four years later, capacity will have shrunk and their profit margins will be way up. So, you always have to sort of imagine the world the way it’s going to be in 18 to 24 months as opposed to now. If you buy it now, you’re buying into every single fad every single moment. Whereas if you envision the future, you’re trying to imagine how that might be reflected differently in security prices.
Peter Lynch made a remarkably prescient market observation in 1994 🎯
Some event will come out of left field, and the market will go down, or the market will go up. Volatility will occur. Markets will continue to have these ups and downs. … Basic corporate profits have grown about 8% a year historically. So, corporate profits double about every nine years. The stock market ought to double about every nine years… The next 500 points, the next 600 points — I don’t know which way they’ll go… They’ll double again in eight or nine years after that. Because profits go up 8% a year, and stocks will follow. That’s all there is to it.
Warren Buffett’s ‘fourth law of motion’ 📉
Long ago, Sir Isaac Newton gave us three laws of motion, which were the work of genius. But Sir Isaac’s talents didn’t extend to investing: He lost a bundle in the South Sea Bubble, explaining later, “I can calculate the movement of the stars, but not the madness of men.” If he had not been traumatized by this loss, Sir Isaac might well have gone on to discover the Fourth Law of Motion: For investors as a whole, returns decrease as motion increases.
Most pros can’t beat the market 🥊
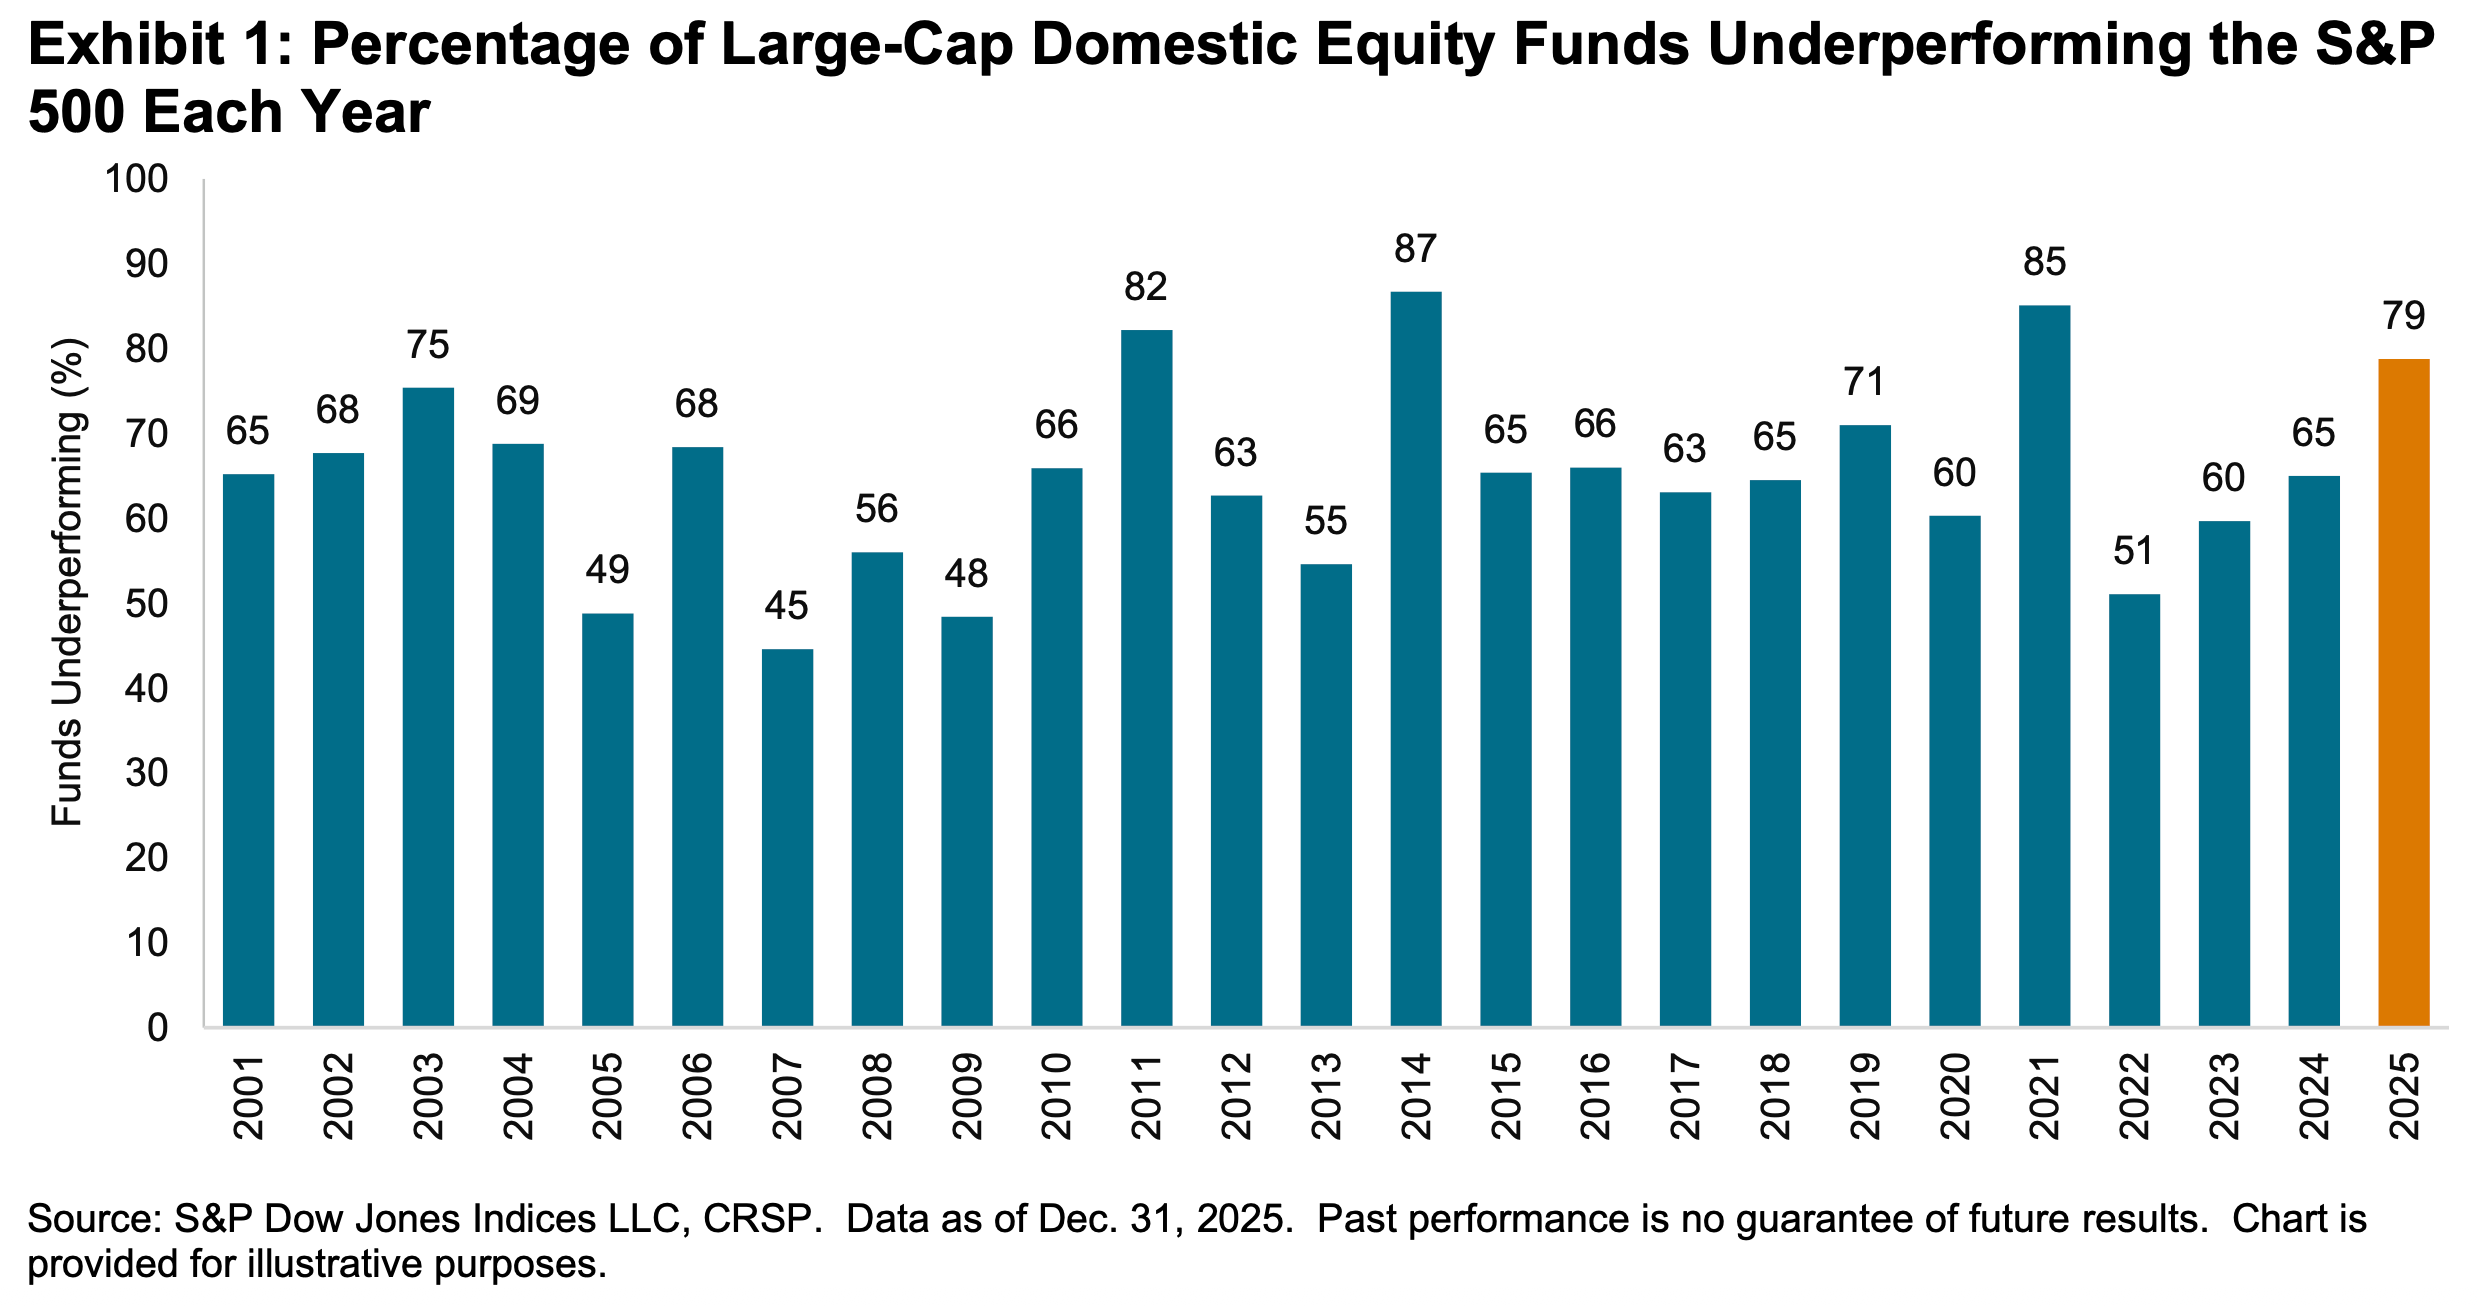
According to S&P Dow Jones Indices (SPDJI), 79% of U.S. large-cap equity fund managers underperformed the S&P 500 in 2025. As you extend the time horizon, the numbers get even worse. Over three years, 67% underperformed. Over 5 years, 89% underperformed. And over 20 years, 93% underperformed. This 2025 performance marked the 16th consecutive year the majority of fund managers in this category have lagged the index.
Proof that ‘past performance is no guarantee of future results’ 📊
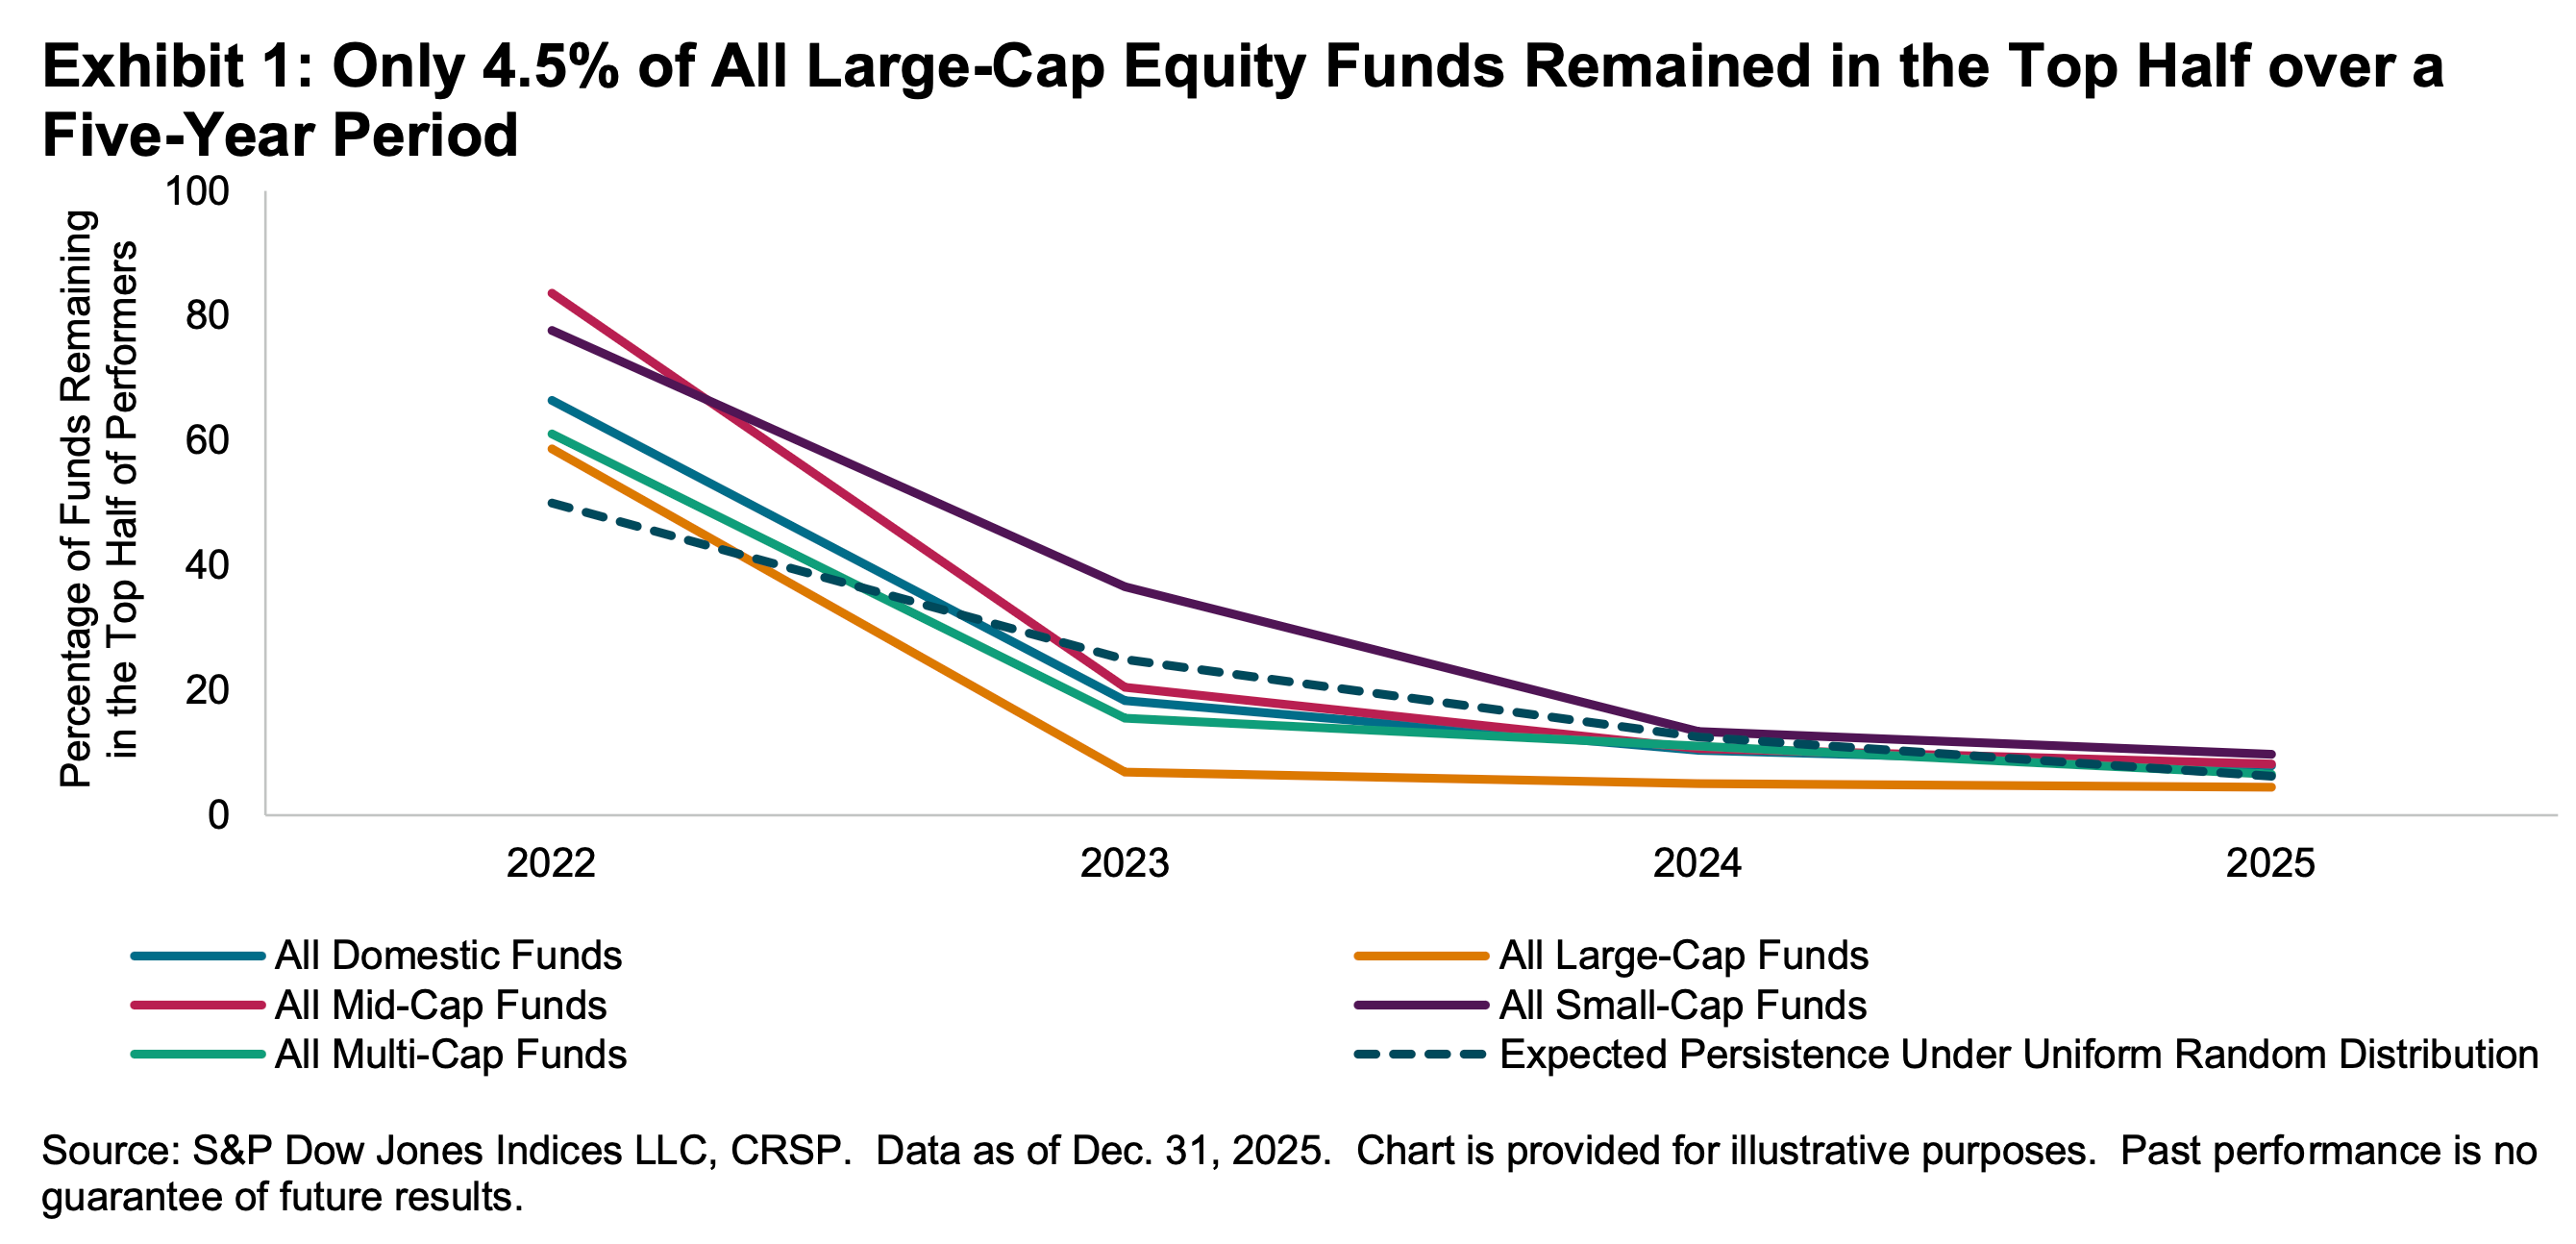
Even if you are a fund manager who generated industry-leading returns in one year, history says it’s an almost insurmountable task to stay on top consistently in subsequent years. According to S&P Dow Jones Indices, of the 334 large-cap equity funds in the top half of performance in 2021, 58.7% remained at the top half in 2022. However, just 6.9% remained on top through 2023. Only 4.5% stayed on top in the five consecutive years through 2025.
It’s much more dismal when you raise the bar. Of the 164 large-cap equity funds in the top quartile in 2021, just 20.1% remained in that category in 2022. That percentage fell to literally 0.0% in 2023.
The odds are stacked against stock pickers 🎲
Picking stocks in an attempt to beat market averages is an incredibly challenging and sometimes money-losing effort. Most professional stock pickers can’t do this consistently. One reason is that most stocks don’t deliver above-average returns. According to S&P Dow Jones Indices, only 19% of S&P 500 stocks outperformed the average stock return from 2001 to 2025. Over this period, the average S&P 500 stock returned 452%, while the median stock returned just 59%.