The stock market falls almost every other day.
Often, you’ll see the market slide a percent or two in a given week.
Sometimes, those modest declines turn into 5% pullbacks.
Occasionally, those pullbacks will morph into a 10% correction. And suddenly you’re rattled, and you’re once again wondering if this is the beginning of a bear market or market crash. After all, all of history’s worst downturns by definition started as 10% declines. If you think harder about it, they all began as 1% declines before that.
For the uninitiated or the forgetful, this is where you can make a mistake, like selling during a run-of-the-mill market correction, only to have to buy higher later, doing irreparable damage to your potential long-term returns.
To be clear, the market does occasionally experience downturns that are worse than the milder ones we see every couple of months. But the data shows it is nearly impossible to trade in and out of these periods in a way that generates alpha. It’s usually better to stick with a sound long-term investment strategy that includes dollar-cost averaging and periodic rebalancing.
All this speaks to why it’s helpful to study history, remember how often markets get ugly, and not bury your head in the sand while in the throes of market turmoil.
I like how my friend Peter Lazaroff articulated this issue in his new book, “The Perfect Portfolio.” From Chapter 2:
EXPOSURE THERAPY FOR INVESTORS
Therapists treat phobias with exposure. A person who’s terrified of spiders doesn’t wake up one day and decide to be brave. They get small, repeated exposures to the thing they fear until their body stops reacting as if it’s in danger.
Investors benefit from the same approach. Each downturn can feel unique and frightening, but the data shows us that volatility is both common and survivable. By becoming more familiar with how stocks behave, you decrease the likelihood that any given decline leads to panic.
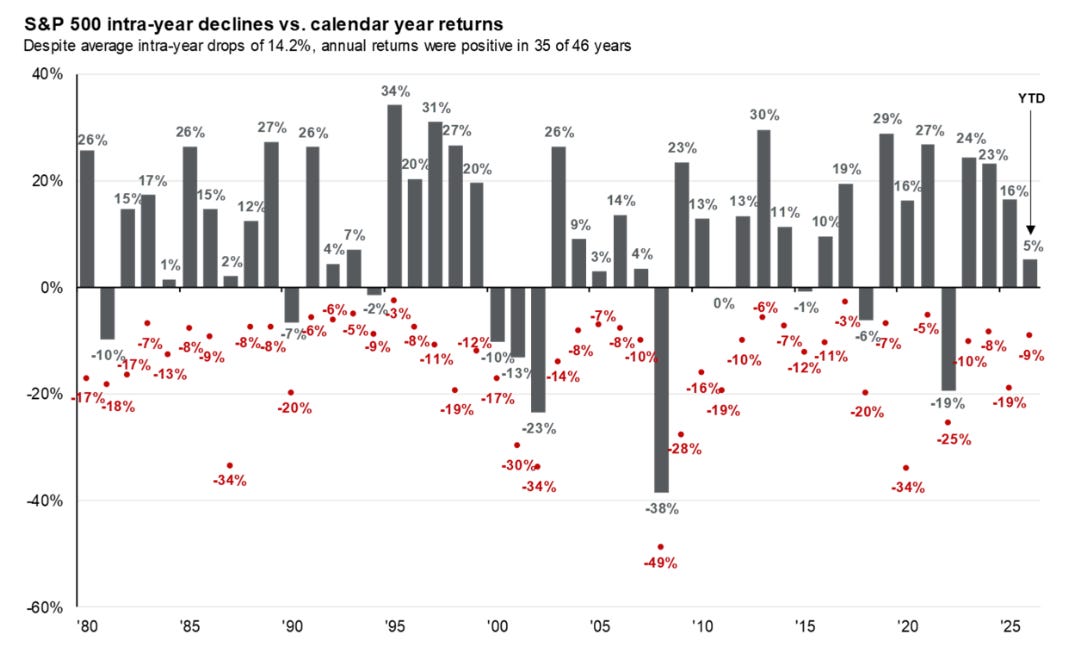
… Roughly two-thirds of calendar years have included a double-digit decline at some point along the way. Despite this, the S&P 500 delivered an average annual return of more than 10% because those losses were temporary setbacks — not permanent destruction.
Volatility is not the enemy — it’s simply the price investors pay for higher returns over the long run.
We are not machines. We’re humans with brains that often respond to unsettling developments in ways that make things worse. When it comes to money and investing, that can be a big problem.
So it can be unproductive to only think about what can go right. Because that can make you more vulnerable to making mistakes when things go wrong.
Of course, not all of us have or can develop the constitution it takes to hold stocks as prescribed in most generic investing advice. Some of us would be better suited by taking less risk. Some of us might actually want to take more risk.
“A portfolio built for ‘anyone’ is usually built for no one in particular,” Lazaroff writes. “No single mix of funds stays perfect across every job, every family situation, every tax bracket, every market environment, and every temperament. A portfolio works when it matches your purpose, your limits, your stage of life, and your ability to stay steady when markets get loud.”
If you’re looking to tailor your portfolio to better fit your wants and needs, check out “The Perfect Portfolio.” In it, Lazaroff guides readers through his process for forming an investing plan that aligns with individual goals while being mindful of one’s stomach for volatility. (You can pre-order it on Amazon.)
-
Related from TKer:
Burying your head in the sand works for some investors, but it’s not the best advice 🫣
Remembering moments when I thought things took a permanent turn for the worse 🙇♂️
Review of the macro crosscurrents 🔀
📉The stock market declined last week, with the S&P 500 shedding 0.1% to end at 7,650.50. The index is now down 1.9% from its August 13 closing high of 7,798.99 and up 11.8% year-to-date. For market insights, check out the Stock Market tab at TKer. »
There were several notable data points and macroeconomic developments since our last review:
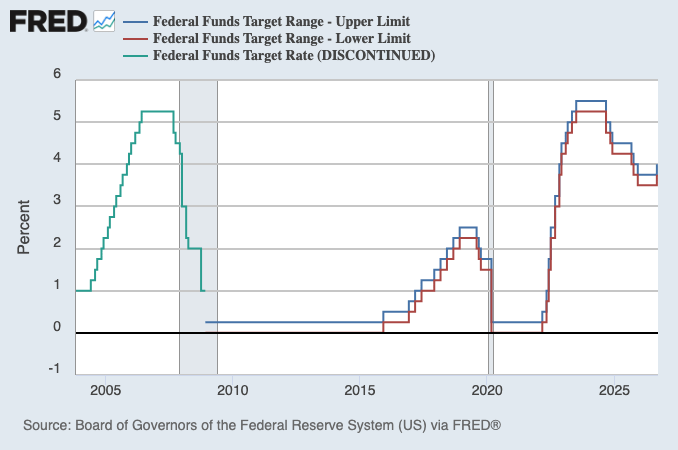
🏛️ Fed hikes rates. On Wednesday, the Federal Reserve raised its benchmark interest rate target range to 3.75% to 4.00%, up by 25 basis points. The decision was unanimous.
From the Fed’s policy statement: “Economic activity is expanding at a solid pace. While uncertainty remains elevated owing, in part, to geopolitical developments, domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little. Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2% goal. The Committee will deliver price stability.“
In its Summary of Economic Projections, the Fed raised its inflation forecast. It also raised its forecast for GDP growth while lowering its forecast for the unemployment rate. On balance, this supports the case for further rate hikes. Indeed, the Fed’s “dot plot” implies one more rate hike later this year, followed by a rate cut in 2028.
There’s some evidence to suggest a first rate hike is associated with short-term market volatility. But you’re always likely to face some volatility in the short run. For long-term investors in the stock market, what matters are the economic conditions in which these policy decisions are made. And right now, the economic backdrop remains supportive of earnings growth, which explains why the stock market remains resilient.
For more on what Fed policy could mean for markets, read: Does the stock market test new Fed chairs? 🏛️ and ‘When will the Fed cut rates?’ is not the right question for investors right now ✂️
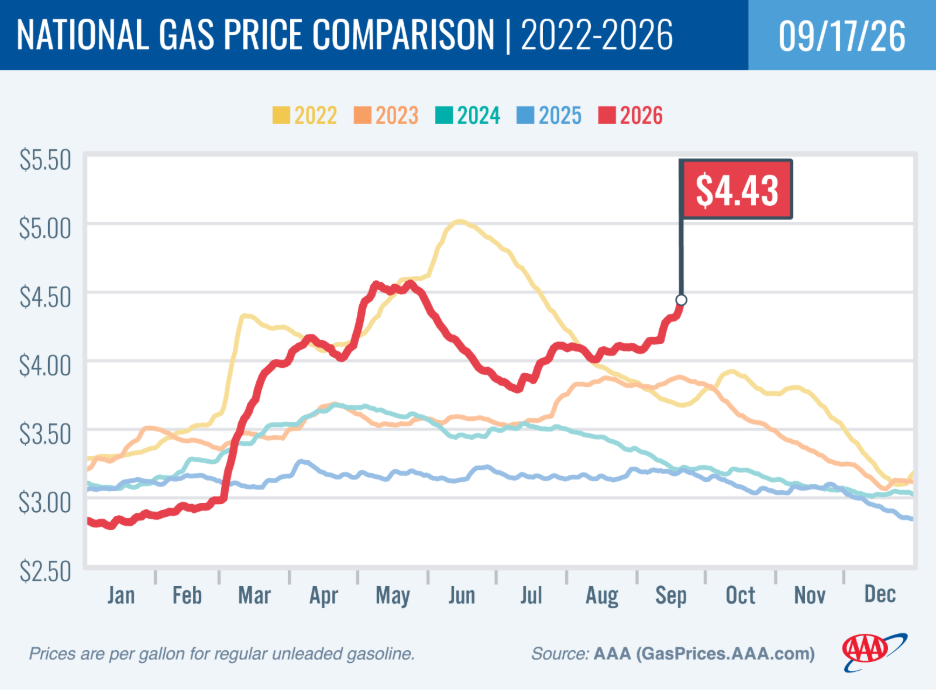
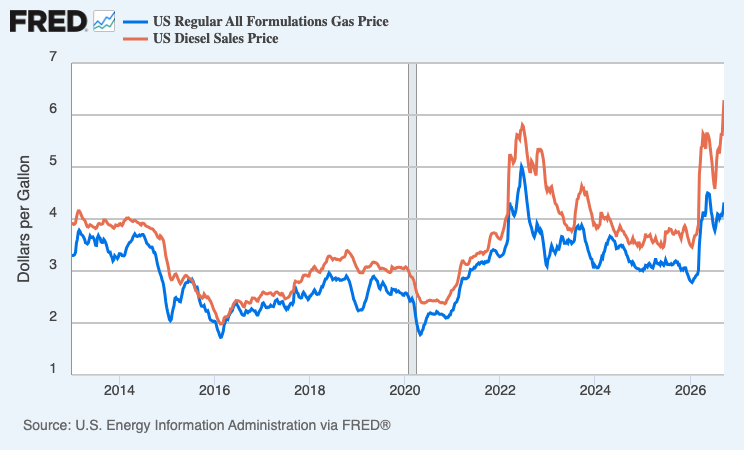
⛽️ Gas prices rise. From AAA: “The national average for a gallon of regular gasoline is up 16 cents from last week at $4.43 and more than one dollar higher than it was a year ago. Crude oil remains high, averaging $100 per barrel amid continued volatility in the Strait of Hormuz. Gas prices are back to what they were earlier this year during the spring, and the national average is inching closer to this year’s record high of $4.56 set on May 21. The all-time high for the national average is $5.01 set on June 14, 2022.“
Here’s a longer-term look at the trajectory of gas and diesel prices, as tracked by the EIA.
For more on energy prices, read: Our love-hate relationship with rising oil prices in charts 💔🛢️📊
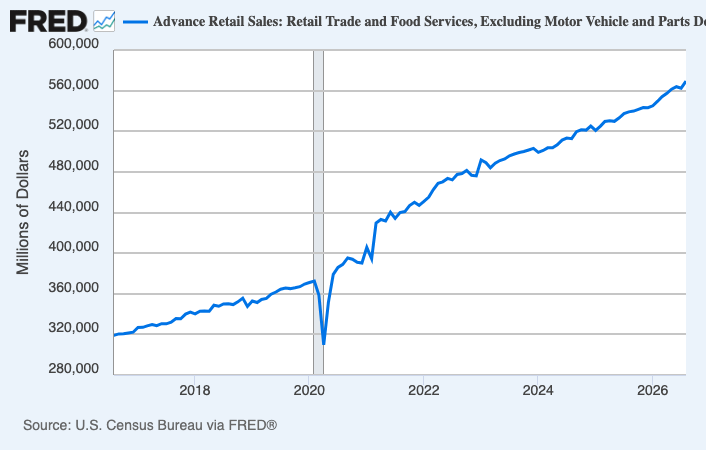
🛍️ Retail shopping activity rose to record levels. Retail sales in August increased 1.2% to a record $773.9 billion.
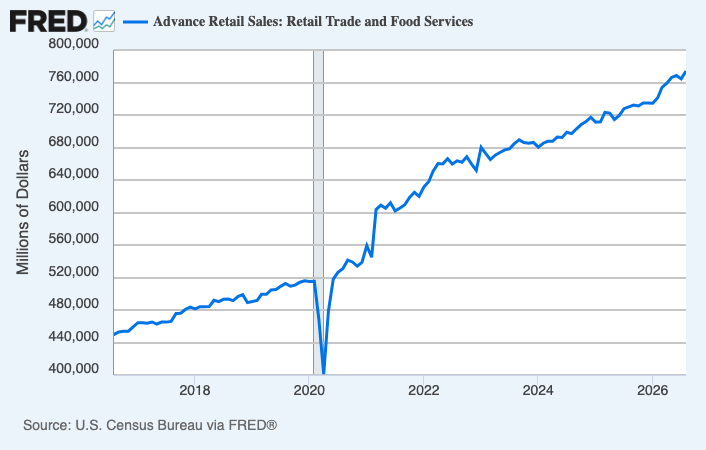
Excluding autos and gas, which tend to be volatile in the short term, retail sales declined 0.2%.
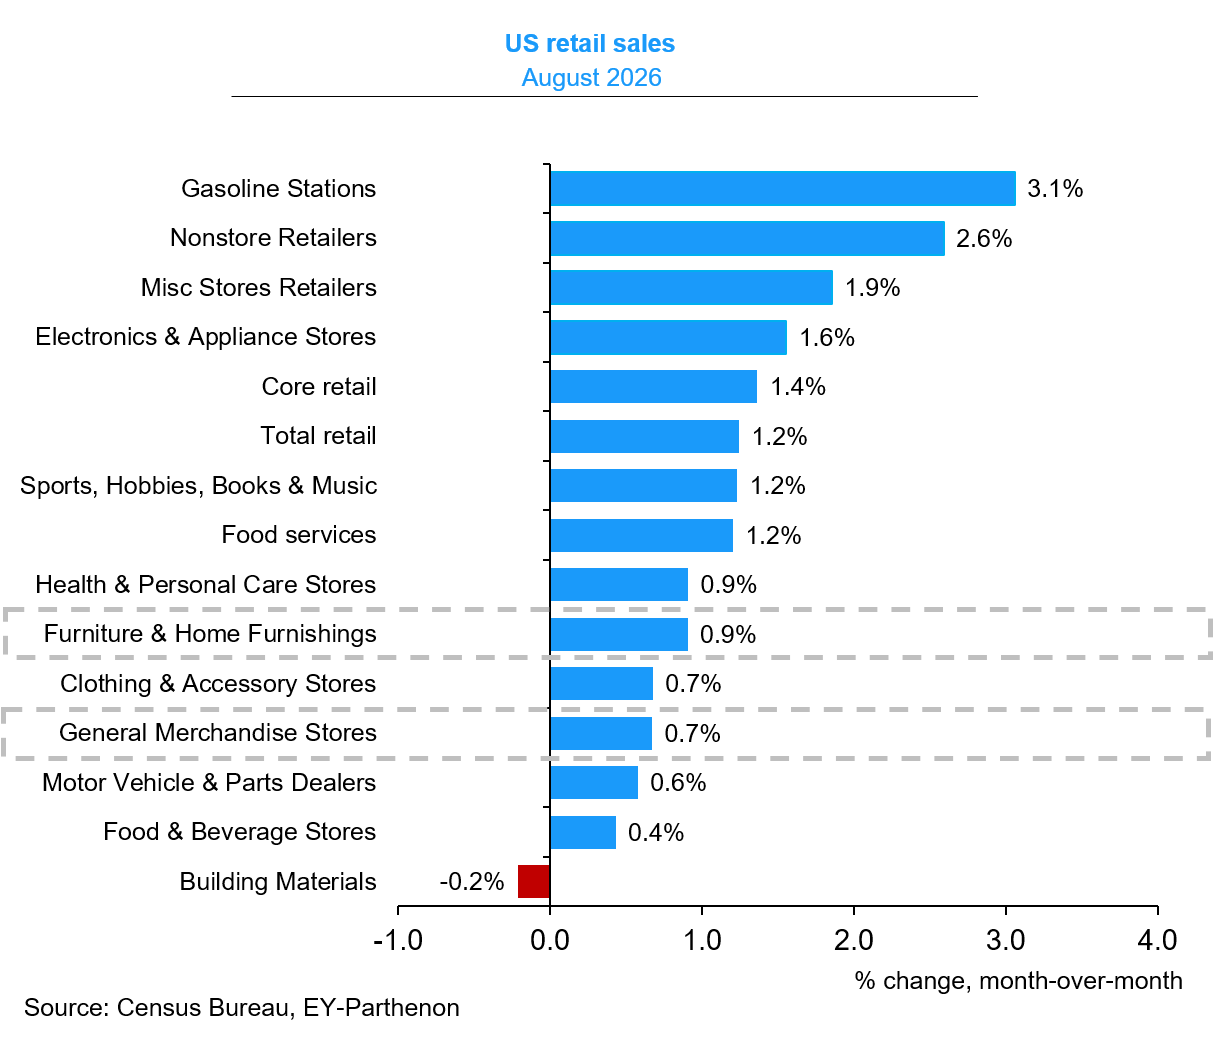
Here’s a look at the change in retail sales by category.
💳 Card spending data is holding up. From BofA: “Total card spending per HH was up 5.8% y/y in the week ending Sep 12, according to BAC aggregated credit & debit card data. The strength in spending growth was likely due to favorable base effects from the shift in Labor Day timing. Overall, spending remains steady in early Sep. However, K-shaped spending increasingly looks like a stale narrative.”
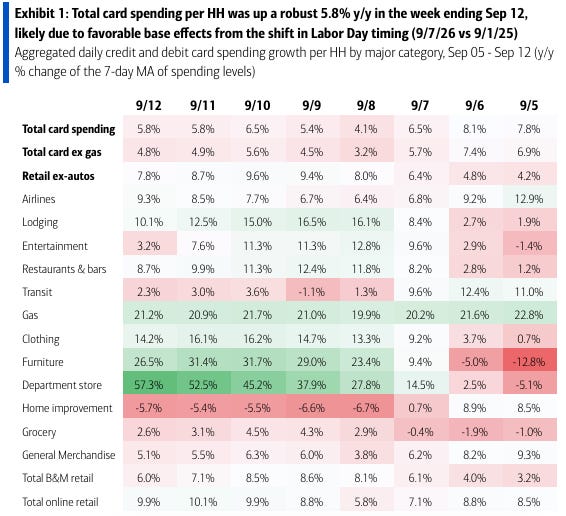
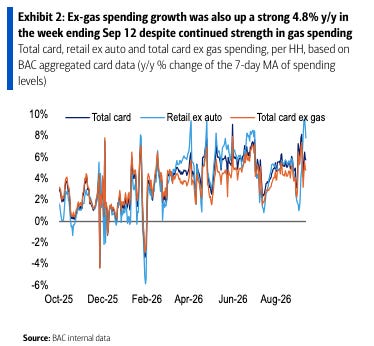
Consumer spending data has looked a lot better than consumer sentiment readings. For more on this contradiction, read: We’re taking that vacation whether we like it or not 🛫 and Household finances are both ‘worse’ and ‘good’ 🌦️
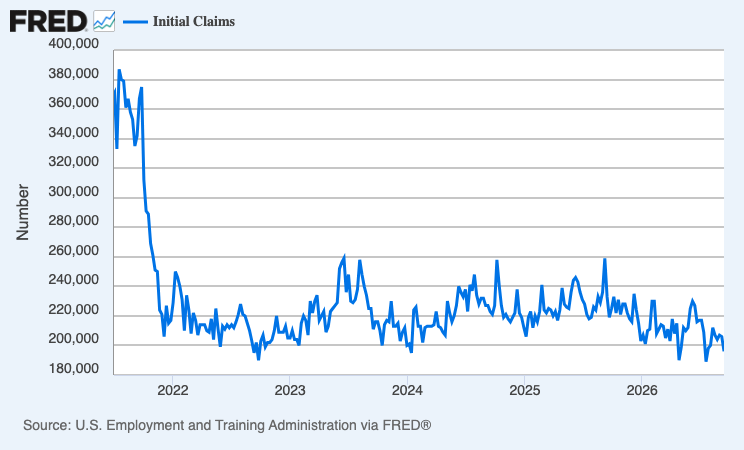
💼 New unemployment insurance claims, total ongoing claims remain low. Initial claims for unemployment benefits ticked down to 196,000 during the week ending Sept. 12, down from 206,000 the week prior. This metric remains at levels historically associated with economic growth.
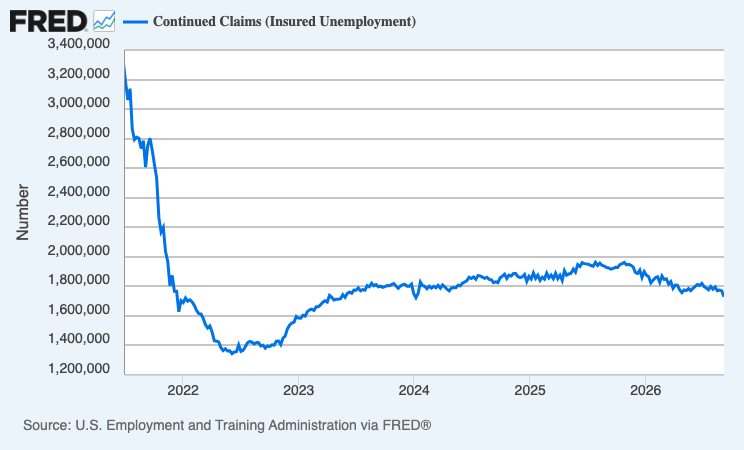
Insured unemployment, which captures those who continue to claim unemployment benefits, ticked down to 1.73 million during the week ending Sept. 5.
For more on the labor market, read: Why mass tech layoffs have little effect on total employment 💾
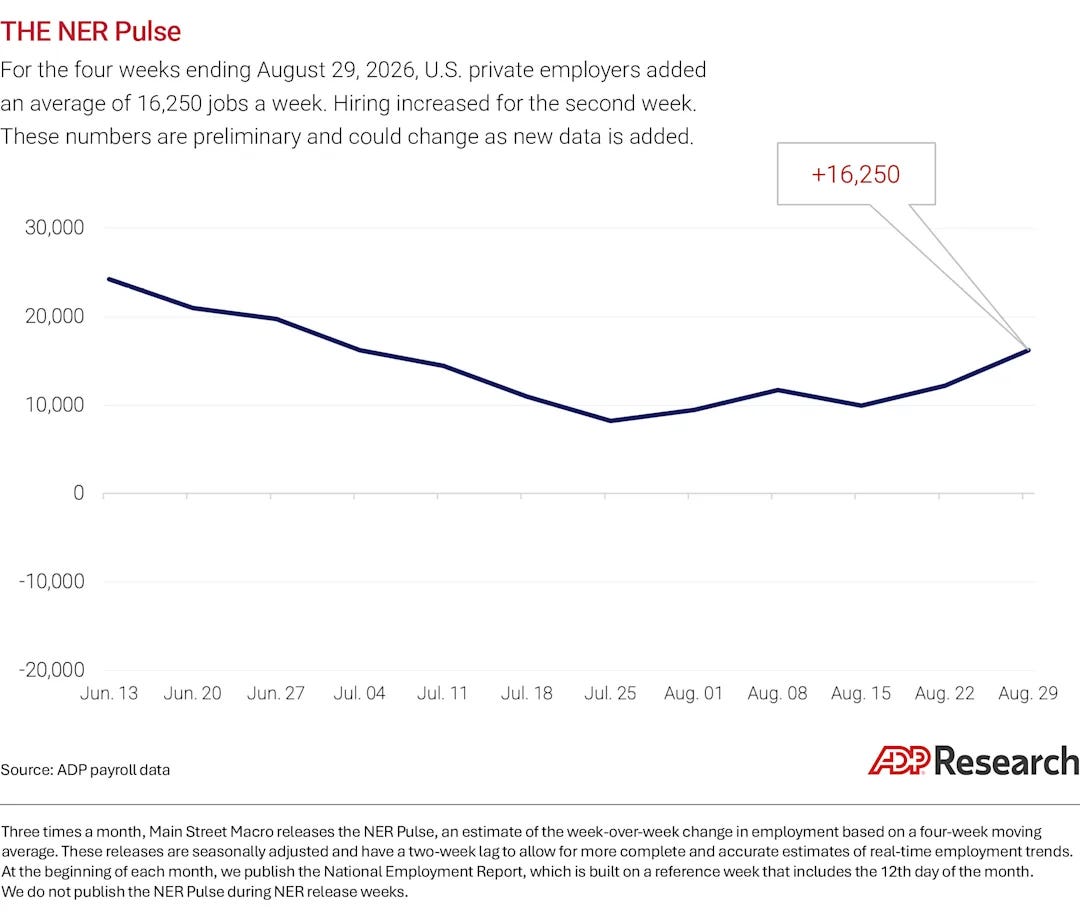
🤔 Recent private job growth is picking up. According to payroll processor ADP, private U.S. employers added 16,500 jobs in the four weeks ending Aug. 29.
For more on the labor market, read: Things are looking up in the labor market 👍
🏠 Mortgage rates rise. According to Freddie Mac, the average 30-year fixed-rate mortgage rose to 6.95%, up from 6.76% last week.
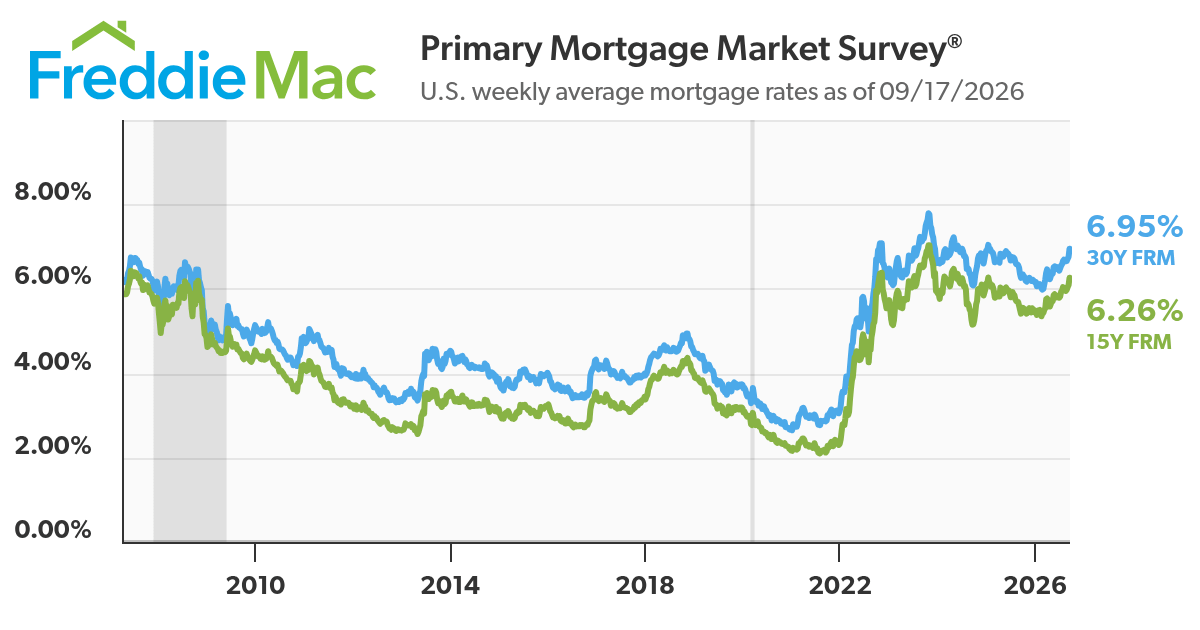
As of Q2, there were 149.5 million housing units in the U.S., of which 87.0 million were owner-occupied and about 40% were mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the weekly movements in home prices or mortgage rates.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
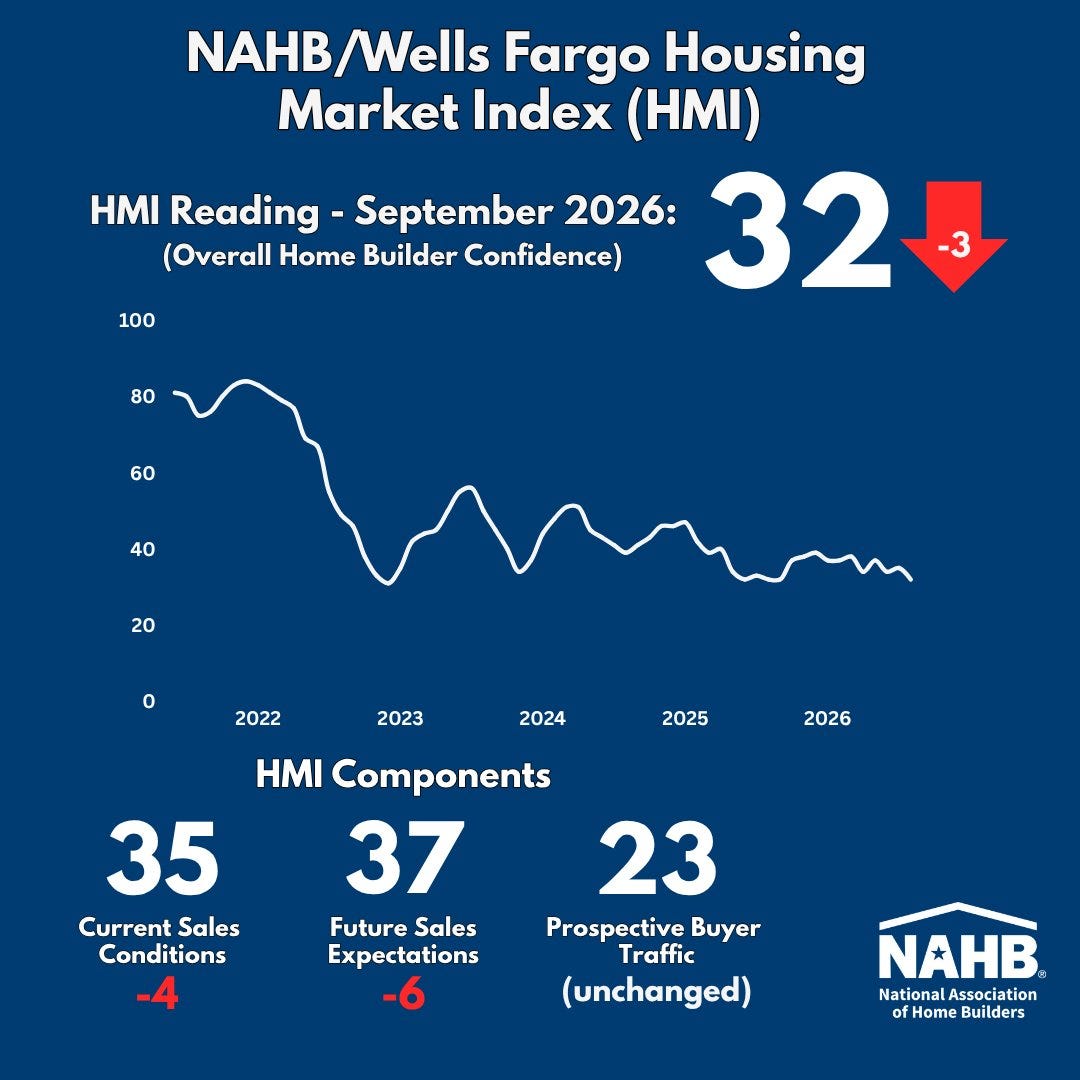
🏠 Homebuilder sentiment ticks lower. From the NAHB: “Buyer traffic has weakened across much of the country, largely because of rising mortgage rates. Builders also continue to face higher material costs, rising gas and diesel prices and persistent labor shortages. In some markets, builders report that increased immigration enforcement is discouraging legal workers from reporting to job sites.”
🔨 New home construction starts fell. Housing starts declined 2.6% in August to an annualized rate of 1.28 million units, according to the Census Bureau. Building permits fell 2.7% to an annualized rate of 1.39 million units.
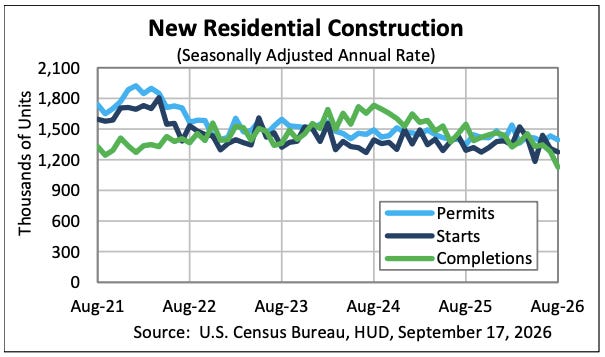
It’s worth noting that the starts metric comes with a very large margin of error. For more on margins of error, read: Mathematical context can totally change the story 🧮
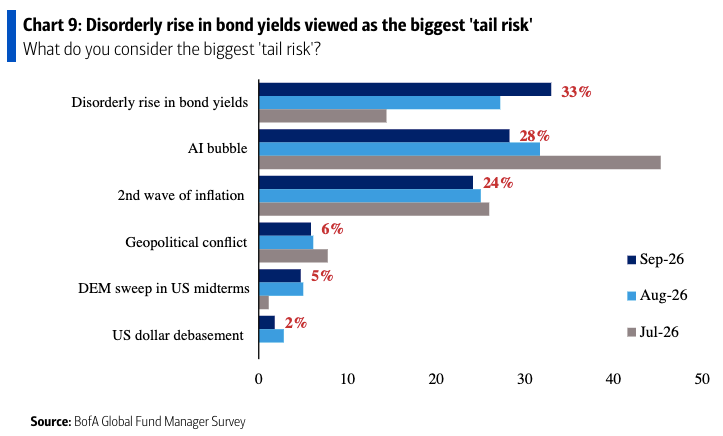
😬 This is the stuff pros are worried about. From BofA’s September Global Fund Manager Survey: “The biggest tail risk in September is a ‘disorderly rise in bond yields’ (33%), replacing last month’s #1 ‘AI bubble’ (drops to 28% from 32%)..”
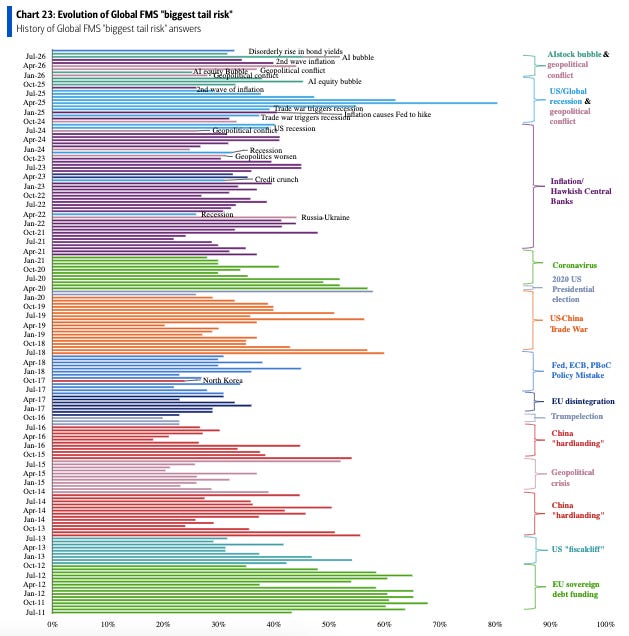
Here’s how the biggest “tail risk” has evolved over the years.
For more on risks, read: Known worries and unknown unknowns 😬 and Two times when uncertainty seemed low and confidence was high 🌈
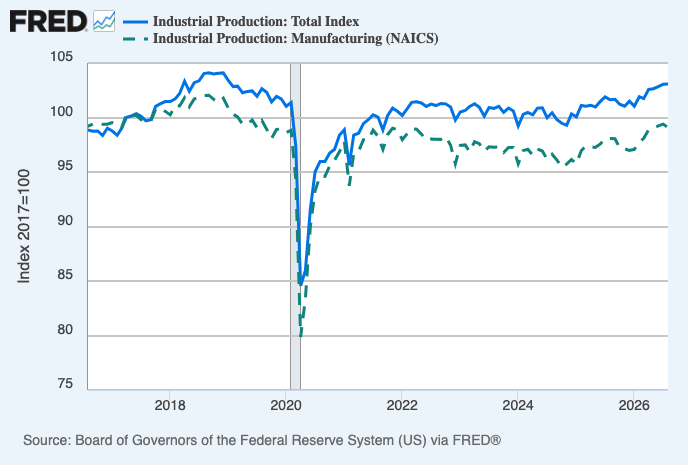
🛠️ Industrial activity cooled. Industrial production activity in August was flat from prior month levels. Manufacturing output declined 0.3% compared to the prior month.
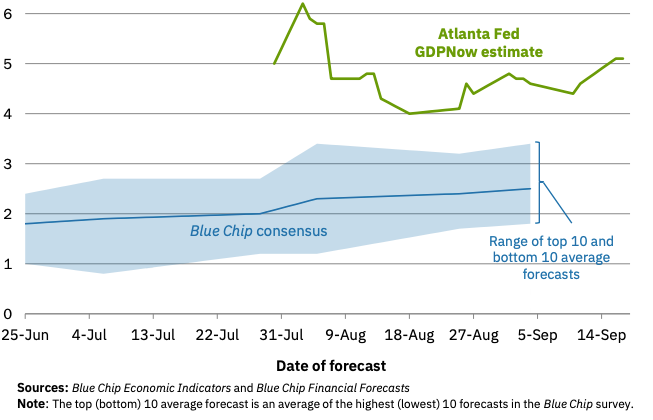
📈 Near-term GDP growth estimates are tracking positively. The Atlanta Fed’s GDPNow model sees real GDP growth rising at a 5.1% rate in Q3.
For more on GDP and the economy, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and Economic data can often be both ‘worse’ and ‘good’ 🌦️
Putting it all together 📋
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Personal spending activity remains at record levels. Core capex orders, which are a leading indicator of business spending, have been trending higher.
Growth rates have cooled: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like job openings and excess savings have faded. Job creation, while positive, is not as hot as it used to be. It has become harder to argue that growth is destiny.
Actions speak louder than words: We are in an odd period, given that the hard economic data decoupled from the soft sentiment-oriented data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data continues to hold up.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This came with strategic layoffs and investment in new equipment, including hardware powered by AI. These moves are resulting in positive operating leverage, which means a modest amount of sales growth — in the cooling economy — is translating to robust earnings growth.
Mind the ever-present risks: Of course, we should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyber attacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term volatility in the markets.
Investing is never a smooth ride: There’s also the harsh reality that economic recessions and bear markets are developments that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
Think long-term: For now, there’s no reason to believe there’ll be a challenge that the economy and the markets won’t overcome. The long game remains undefeated, and it’s a streak that long-term investors can expect to continue.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
Key insights about the stock market 📈
Here’s a roundup of some of TKer’s most talked-about paid and free newsletters about the stock market. All of the headlines are hyperlinked to the archived pieces.
10 truths about the stock market 📈
The stock market can be an intimidating place: It’s real money on the line, there’s an overwhelming amount of information, and people have lost fortunes in it very quickly. But it’s also a place where thoughtful investors have long accumulated a lot of wealth. The primary difference between those two outlooks is related to misconceptions about the stock market that can lead people to make poor investment decisions.
The makeup of the S&P 500 is constantly changing 🔀
Passive investing is a concept usually associated with buying and holding a fund that tracks an index. And no passive investment strategy has attracted as much attention as buying an S&P 500 index fund. However, the S&P 500 — an index of 500 of the largest U.S. companies — is anything but a static set of 500 stocks.

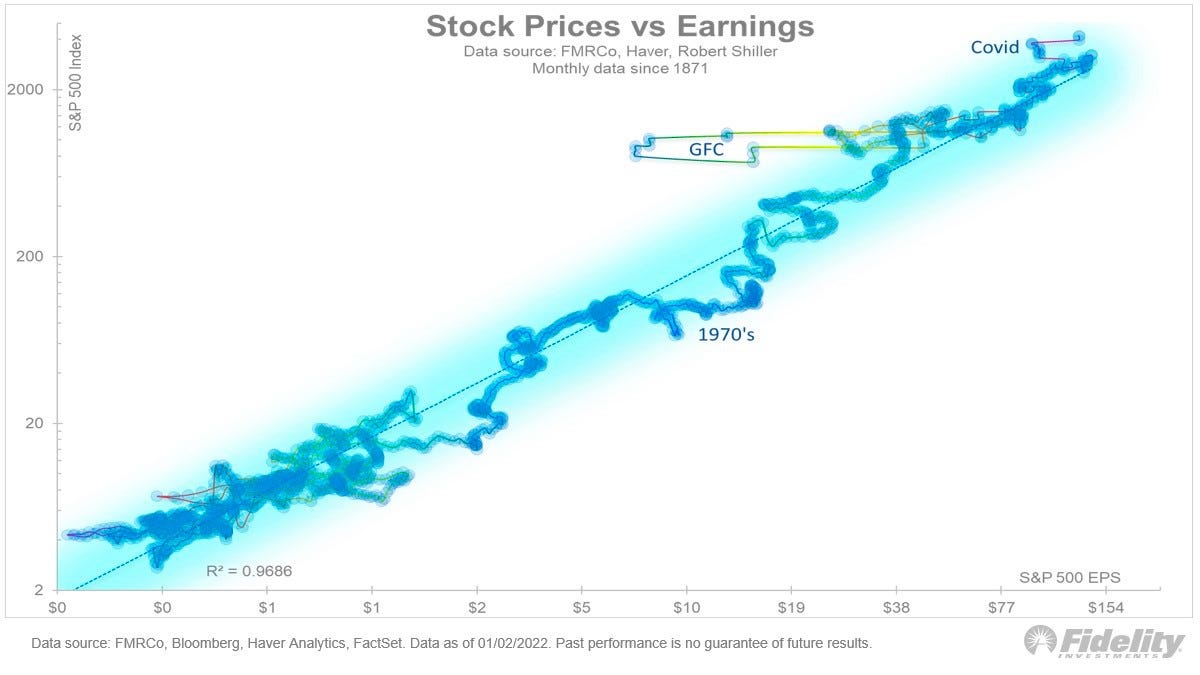
The key driver of stock prices: Earnings💰
For investors, anything you can ever learn about a company matters only if it also tells you something about earnings. That’s because long-term moves in a stock can ultimately be explained by the underlying company’s earnings, expectations for earnings, and uncertainty about those expectations for earnings. Over time, the relationship between stock prices and earnings has a very tight statistical relationship.
Stomach-churning stock market sell-offs are normal🎢
Investors should always be mentally prepared for some big sell-offs in the stock market. It’s part of the deal when you invest in an asset class that is sensitive to the constant flow of good and bad news. Since 1950, the S&P 500 has seen an average annual max drawdown (i.e., the biggest intra-year sell-off) of 14%.
How the stock market performed around recessions 📉📈
Every recession in history was different. And the range of stock performance around them varied greatly. There are two things worth noting. First, recessions have always been accompanied by a significant drawdown in stock prices. Second, the stock market bottomed and inflected upward long before recessions ended.

In the stock market, time pays ⏳
Since 1928, the S&P 500 has generated a positive total return more than 89% of the time over all five-year periods. Those are pretty good odds. When you extend the timeframe to 20 years, you’ll see that there’s never been a period where the S&P 500 didn’t generate a positive return.

What a strong dollar means for stocks 👑
While a strong dollar may be great news for Americans vacationing abroad and U.S. businesses importing goods from overseas, it’s a headwind for multinational U.S.-based corporations doing business in non-U.S. markets.

Stanley Druckenmiller’s No. 1 piece of advice for novice investors 🧐
…you don’t want to buy them when earnings are great, because what are they doing when their earnings are great? They go out and expand capacity. Three or four years later, there’s overcapacity and they’re losing money. What about when they’re losing money? Well, then they’ve stopped building capacity. So three or four years later, capacity will have shrunk and their profit margins will be way up. So, you always have to sort of imagine the world the way it’s going to be in 18 to 24 months as opposed to now. If you buy it now, you’re buying into every single fad every single moment. Whereas if you envision the future, you’re trying to imagine how that might be reflected differently in security prices.
Peter Lynch made a remarkably prescient market observation in 1994 🎯
Some event will come out of left field, and the market will go down, or the market will go up. Volatility will occur. Markets will continue to have these ups and downs. … Basic corporate profits have grown about 8% a year historically. So, corporate profits double about every nine years. The stock market ought to double about every nine years… The next 500 points, the next 600 points — I don’t know which way they’ll go… They’ll double again in eight or nine years after that. Because profits go up 8% a year, and stocks will follow. That’s all there is to it.
Warren Buffett’s ‘fourth law of motion’ 📉
Long ago, Sir Isaac Newton gave us three laws of motion, which were the work of genius. But Sir Isaac’s talents didn’t extend to investing: He lost a bundle in the South Sea Bubble, explaining later, “I can calculate the movement of the stars, but not the madness of men.” If he had not been traumatized by this loss, Sir Isaac might well have gone on to discover the Fourth Law of Motion: For investors as a whole, returns decrease as motion increases.
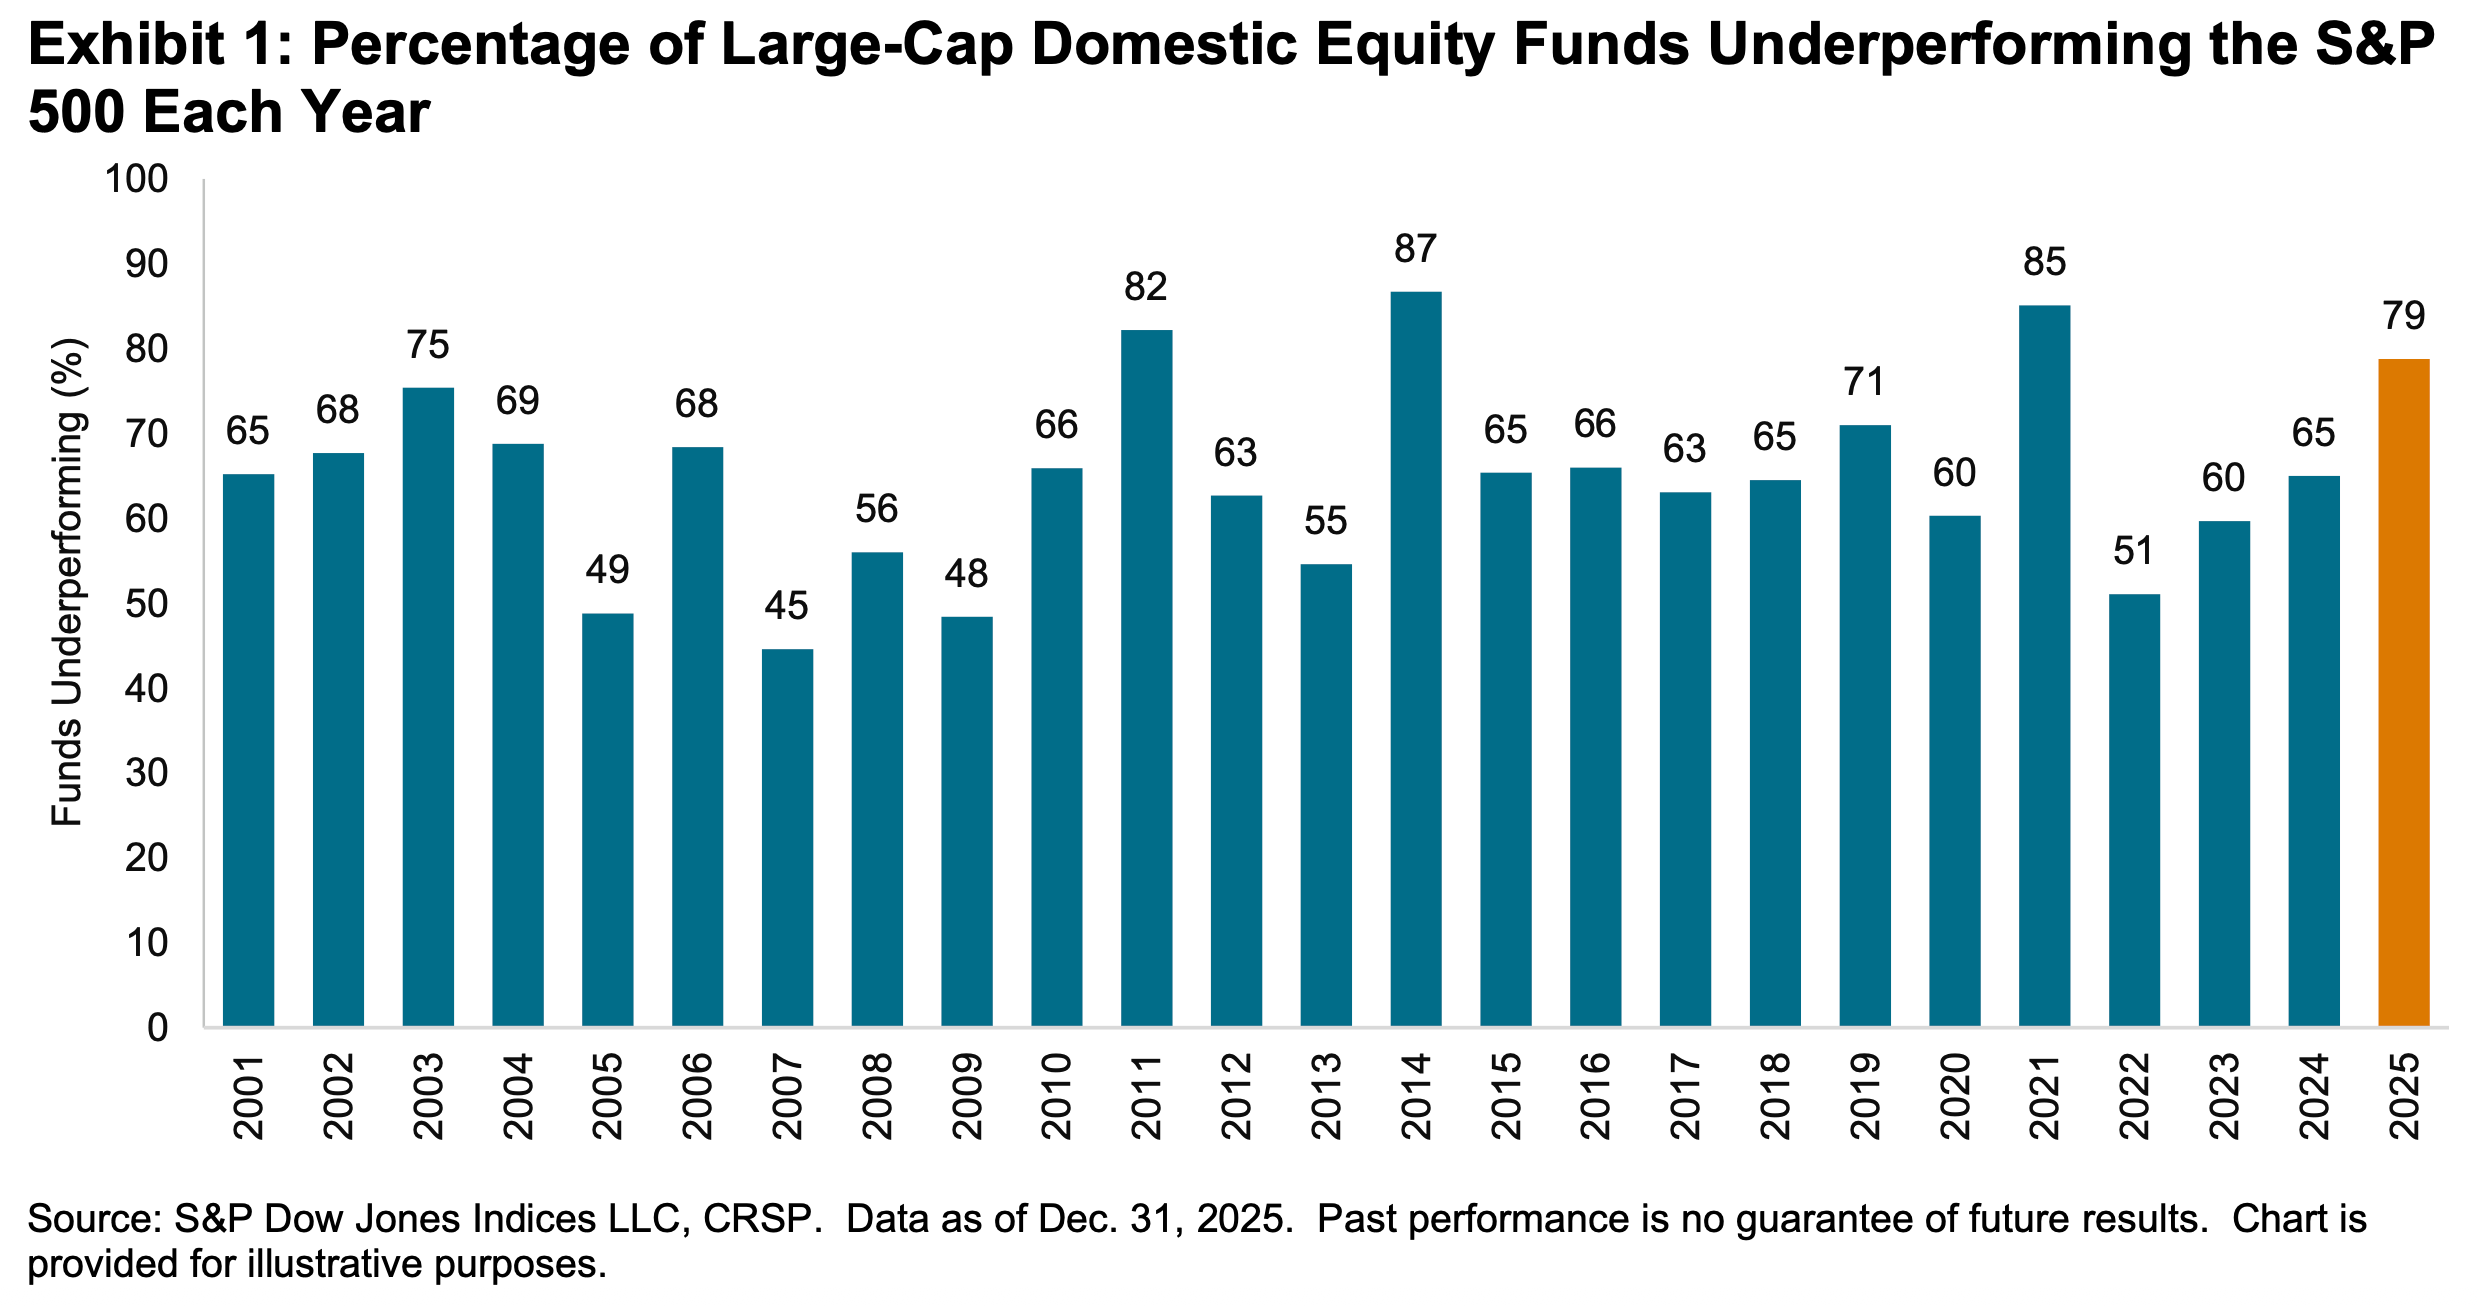
Most pros can’t beat the market 🥊
According to S&P Dow Jones Indices (SPDJI), 79% of U.S. large-cap equity fund managers underperformed the S&P 500 in 2025. As you stretch the time horizon, the numbers get even more dismal. Over three years, 67% underperformed. Over 5 years, 89% underperformed. And over 20 years, 93% underperformed. This 2025 performance was the 16th consecutive year in which the majority of fund managers in this category have lagged the index.
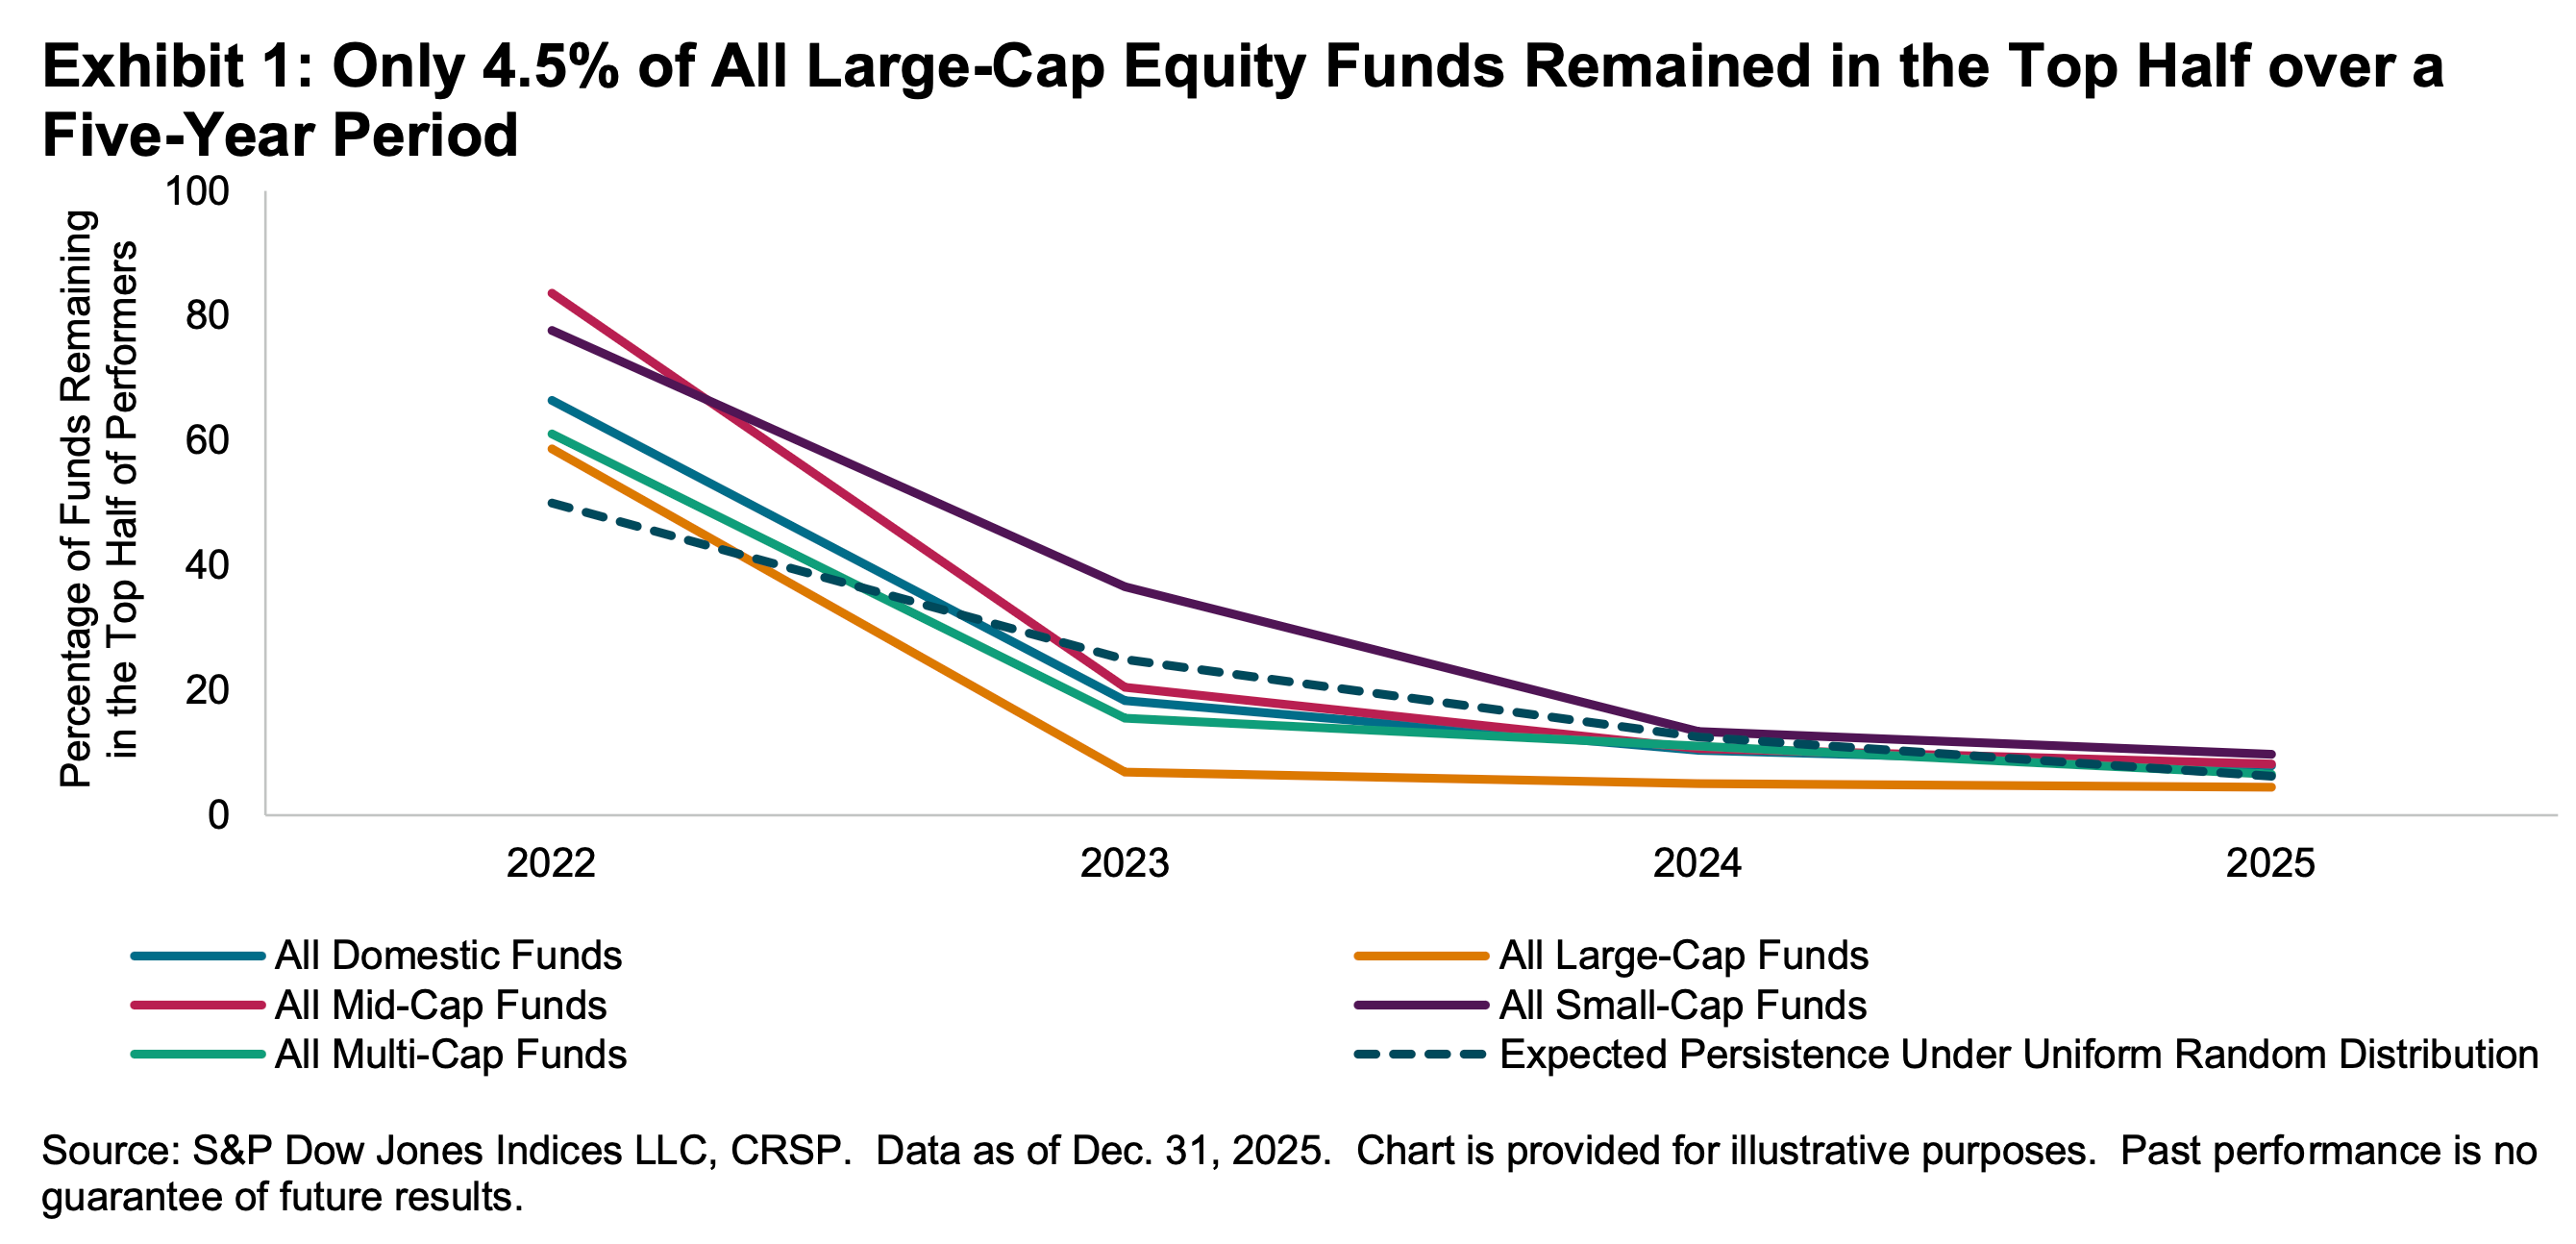
Proof that ‘past performance is no guarantee of future results’ 📊
Even if you are a fund manager who generated industry-leading returns in one year, history says it’s an almost insurmountable task to stay on top consistently in subsequent years. According to S&P Dow Jones Indices, of the 334 large-cap equity funds in the top half of performance in 2021, 58.7% remained at the top half in 2022. However, just 6.9% remained on top through 2023. Only 4.5% stayed on top in the five consecutive years through 2025.
It’s much more dismal when you raise the bar. Of the 164 large-cap equity funds in the top quartile in 2021, just 20.1% remained in that category in 2022. That percentage fell to literally 0.0% in 2023.
The odds are stacked against stock pickers 🎲
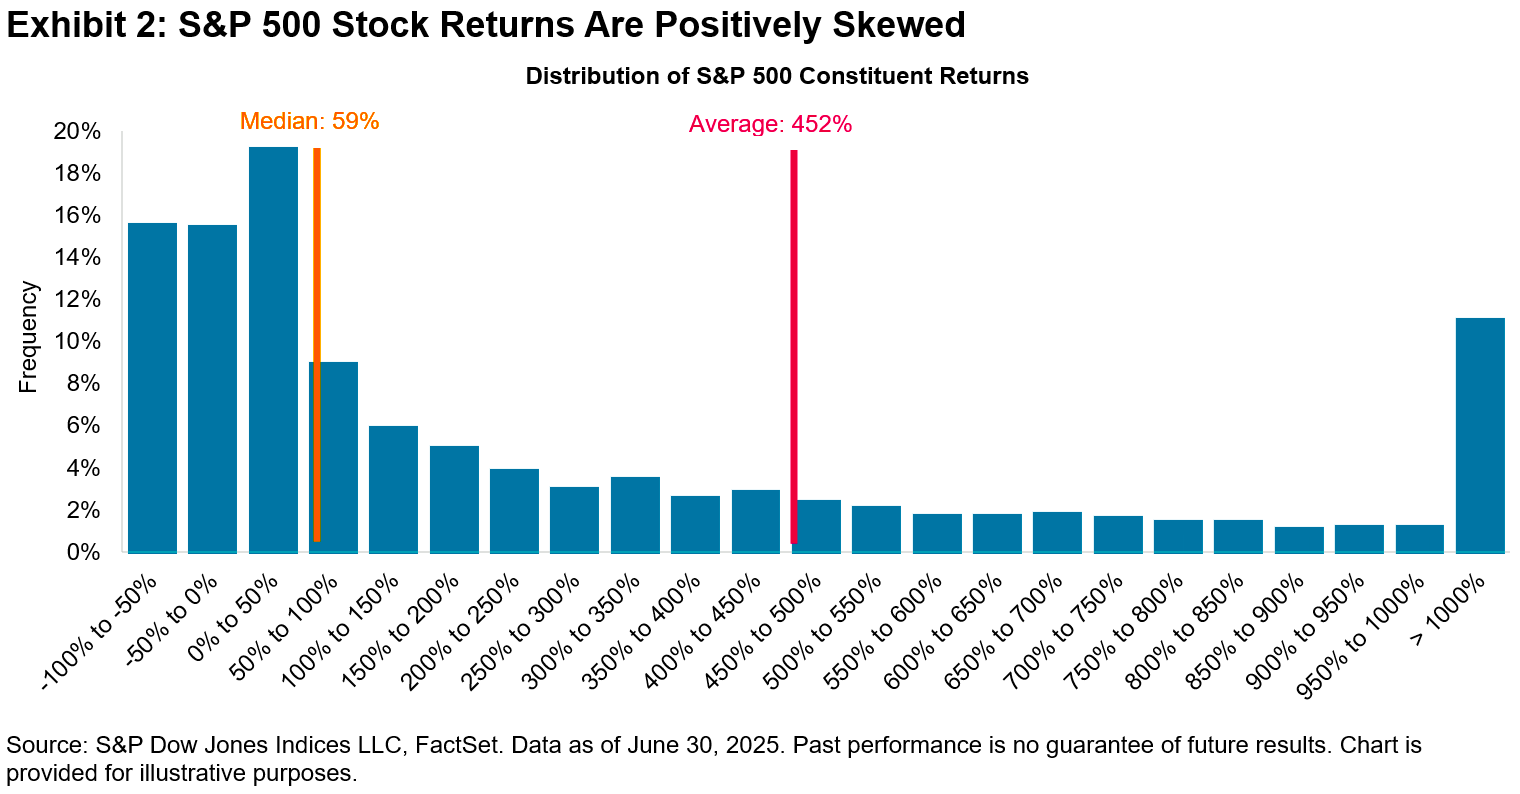
Picking stocks in an attempt to beat market averages is an incredibly challenging and sometimes money-losing effort. Most professional stock pickers aren’t able to do this consistently. One of the reasons for this is that most stocks don’t deliver above-average returns. According to S&P Dow Jones Indices, only 19% of the stocks in the S&P 500 outperformed the average stock’s return from 2001 to 2025. Over this period, the average return on an S&P 500 stock was 452%, while the median stock rose by just 59%.