The periods before and after midterm elections are famously volatile for stocks.
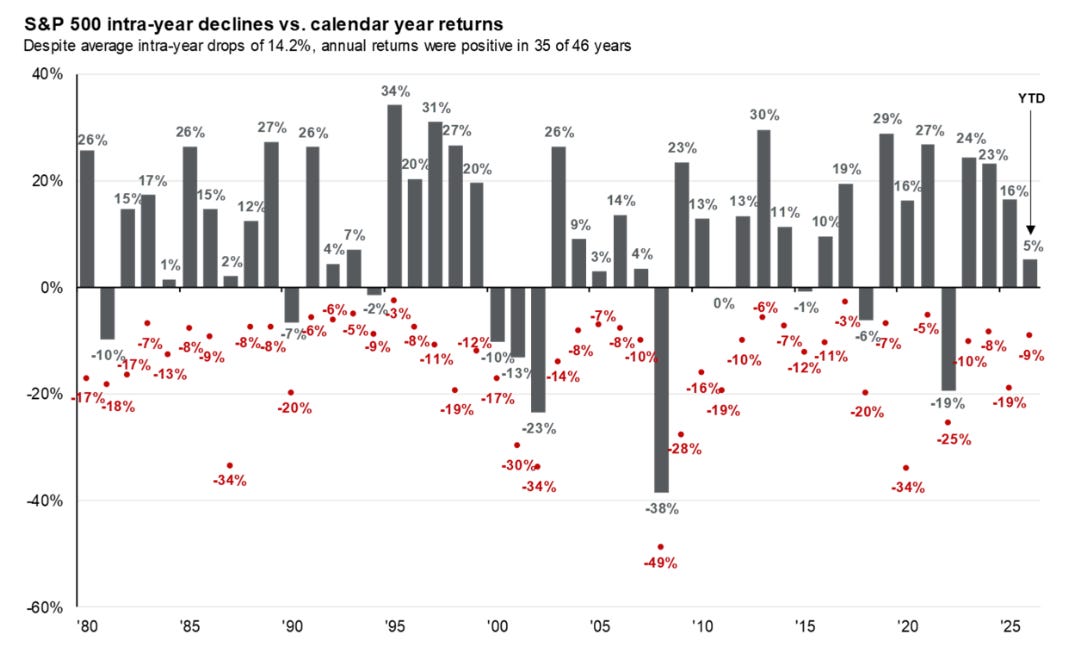
Historically, midterm election years have had an average intra-year drawdown of 18% for the S&P 500. This is worse than the average 14% drawdown across all years.
On the plus side, the stock market has tended to perform well once there’s a clearer indication of what the election results could look like. As the midterm election gets closer, markets typically react positively, regardless of the party in power.
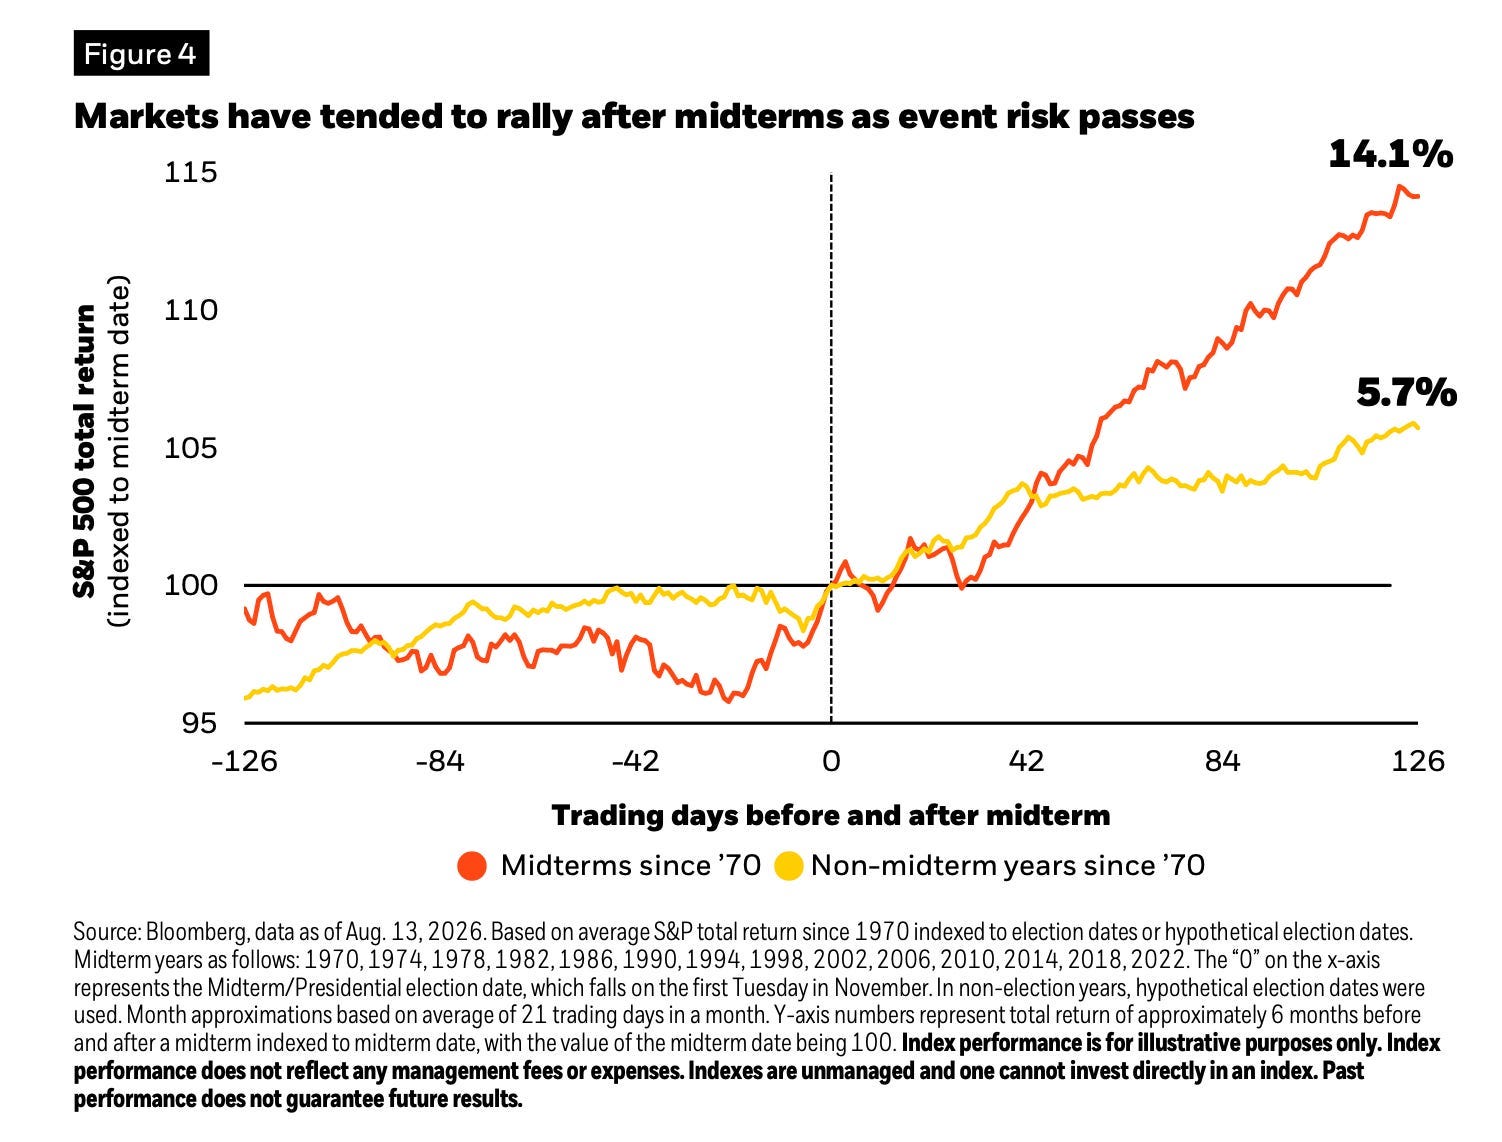
“Since 1970, the market has started to rally on average around a month (22 trading days) before a midterm election, as polling data provides clearer indications of results,” BlackRock analysts wrote earlier this year. “As event risk passes post-election, equities have historically experienced tailwinds, with an average return of 14.1% in the following six months compared to 5.7% in non-midterm years.”
Other analysts have found similarly compelling data points.
Jeffrey Hirsch of Almanac Trader has noted the strongest 6-month period of the 4-year presidential cycle has historically started in November of midterm election years.
Joe Terranova of Virtus Investment Partners found that since 1939, the stock market has produced a positive return from the midterm election date to June 30 of the following year 100% of the time. Of those 21 observations, 14 had double-digit returns.
There’s a basic explanation for this pattern: Midterm elections can have significant policy implications, and the uncertainty caps prices as everyone waits for clarity on the policy outlook.
And the elections are an uncertainty-clearing event.
There are cases to be made that certain election results are more bullish for the market than others. But regardless of the outcome, removing uncertainty alone seems enough to boost prices, as businesses move forward with any plans that may have been exposed to upcoming policy decisions.
A cautionary note ⚠️
All of these historical patterns are consistent with a stock market that experiences intermittent volatility even as it usually goes up.
But especially in the short run, there’s never a guarantee that what’s been a statistically regular event will repeat next time.
In other words, I’d be reluctant to get too creative with trades based on what history suggests could happen in the next several months.
Keep in mind that so far this year, the S&P 500 has experienced a max drawdown of just 9%, which is already a bit inconsistent with the historical averages.
To be clear, I’m not suggesting you reposition your portfolio for one outcome or another. Personally, I don’t expect to stray from my long-term strategy. I almost never do.
Rather, I’m just cautioning against getting too excited about what’s historically been a bullish short-term period for stocks.
-
Related from TKer:
2026 could be crappy for the stock market, and that would be normal 📉
27 charts to consider as we look forward in the stock market 📉📈
Review of the macro crosscurrents 🔀
📉The stock market fell last week, with the S&P 500 shedding 0.6% to end at 7,623.68. The index is now down 3.1% from its October 6 closing high of 7,818.93 and up 10.7% year-to-date. For market insights, check out the Stock Market tab at TKer. »
There were several notable data points and macroeconomic developments since our last review:
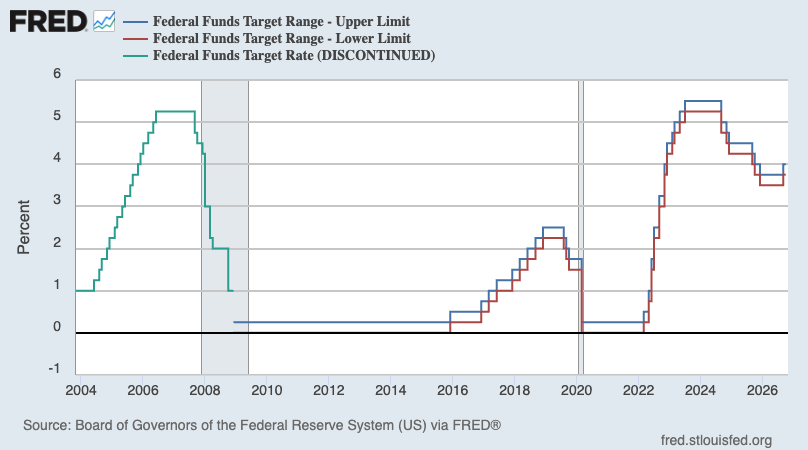
🏛️ Fed holds rates. On Wednesday, the Federal Reserve kept its benchmark interest rate target unchanged at a range of 3.75% to 4.00%. The decision passed 10-2, with Governor Lisa Cook and Cleveland Fed President Beth Hammack dissenting and calling for a rate hike.
From the Fed’s statement: “Economic activity is expanding at a strong pace. While uncertainty remains elevated owing, in part, to geopolitical developments, domestic spending has been resilient. Productivity growth is strong, and capital investment is robust. Job gains have kept pace with the workforce, and the unemployment rate has changed little. Inflation remains elevated. The accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee’s 2% goal. The Committee will deliver price stability.”
For more on what Fed policy could mean for markets, read: Does the stock market test new Fed chairs? 🏛️ and ‘When will the Fed cut rates?’ is not the right question for investors right now ✂️
🎈 Fed’s preferred inflation measure heat up. The personal consumption expenditures (PCE) price index in September was up 3.6% from a year ago. The core PCE price index — the Federal Reserve’s preferred measure of inflation — rose 3.1% during the month, up from August’s 3.0%.
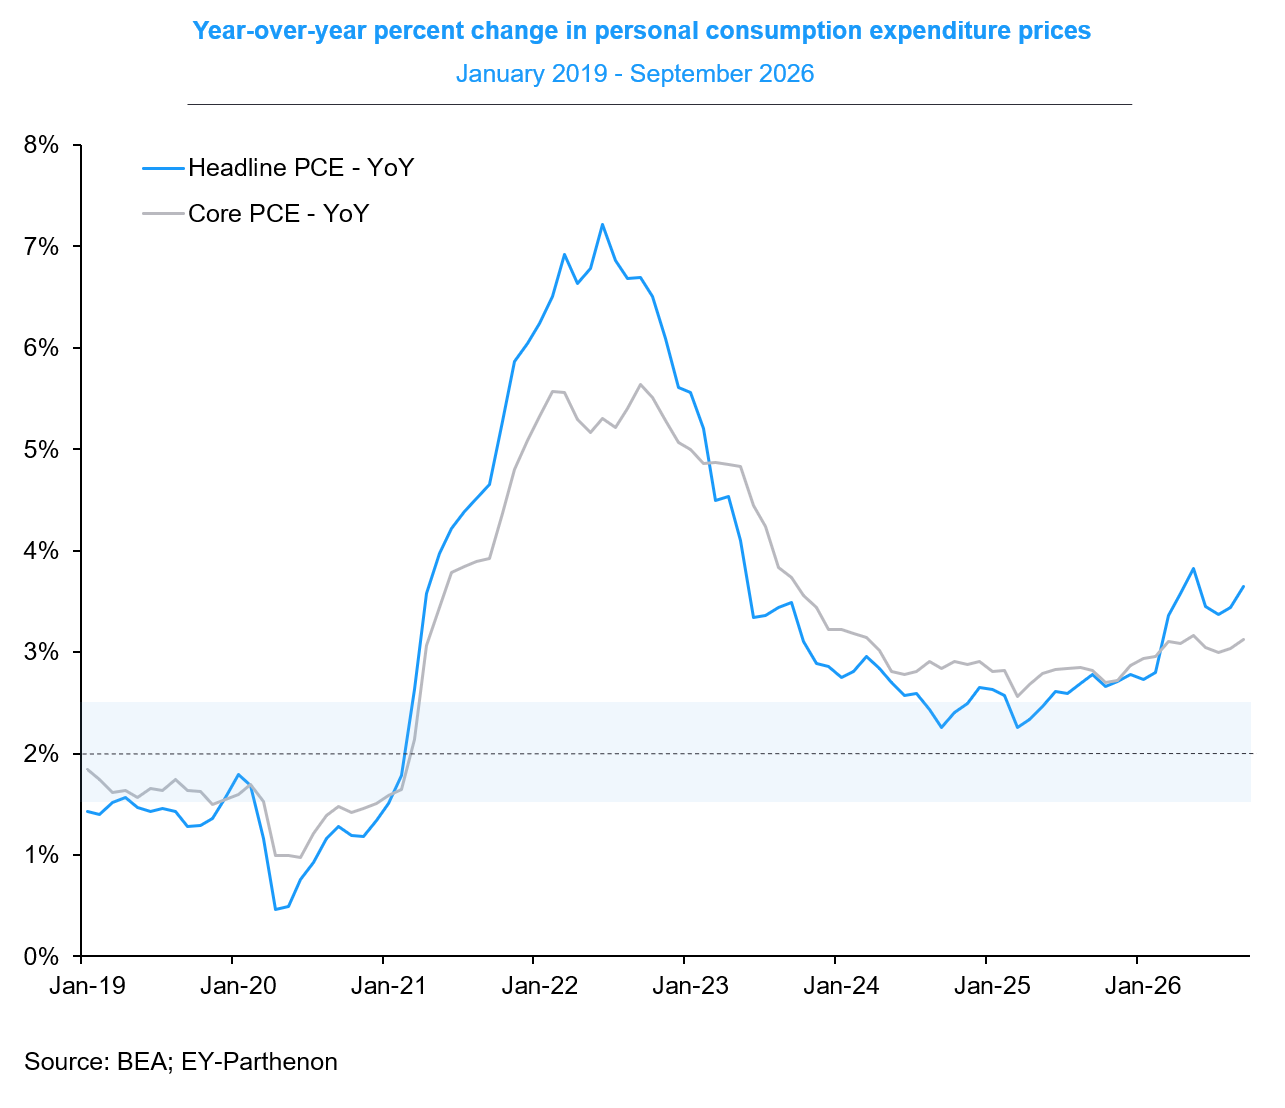
On a month-over-month basis, the core PCE price index was up 0.3%. If you annualize the three-month trend in the monthly figures — a reflection of the short-term trend in prices — core PCE climbed 2.9%.
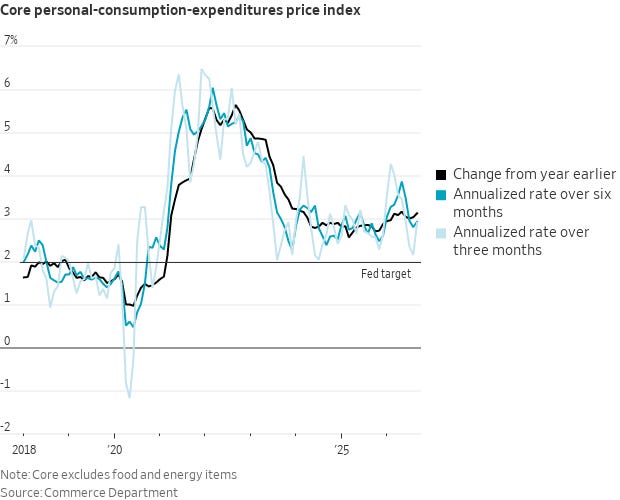
Inflation rates continue to trend above the Federal Reserve’s 2% target. How price trends evolve in the near term remains worth watching.
For more on the Fed’s impact on markets, read: ‘When will the Fed cut rates?’ is not the right question for investors right now ✂️
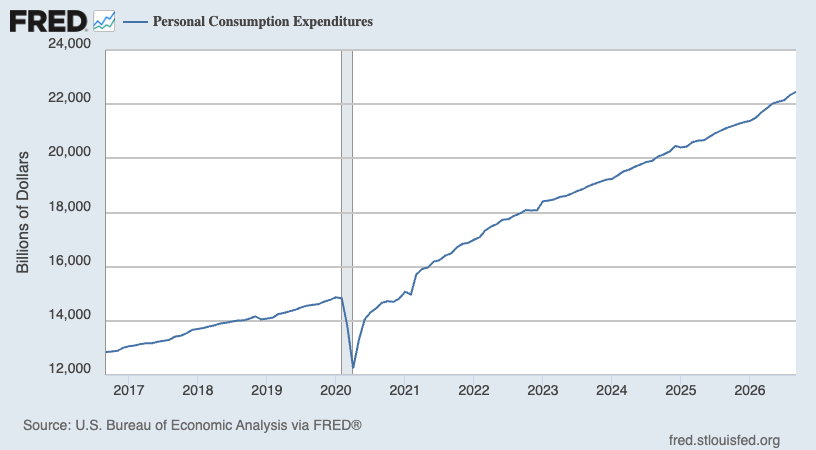
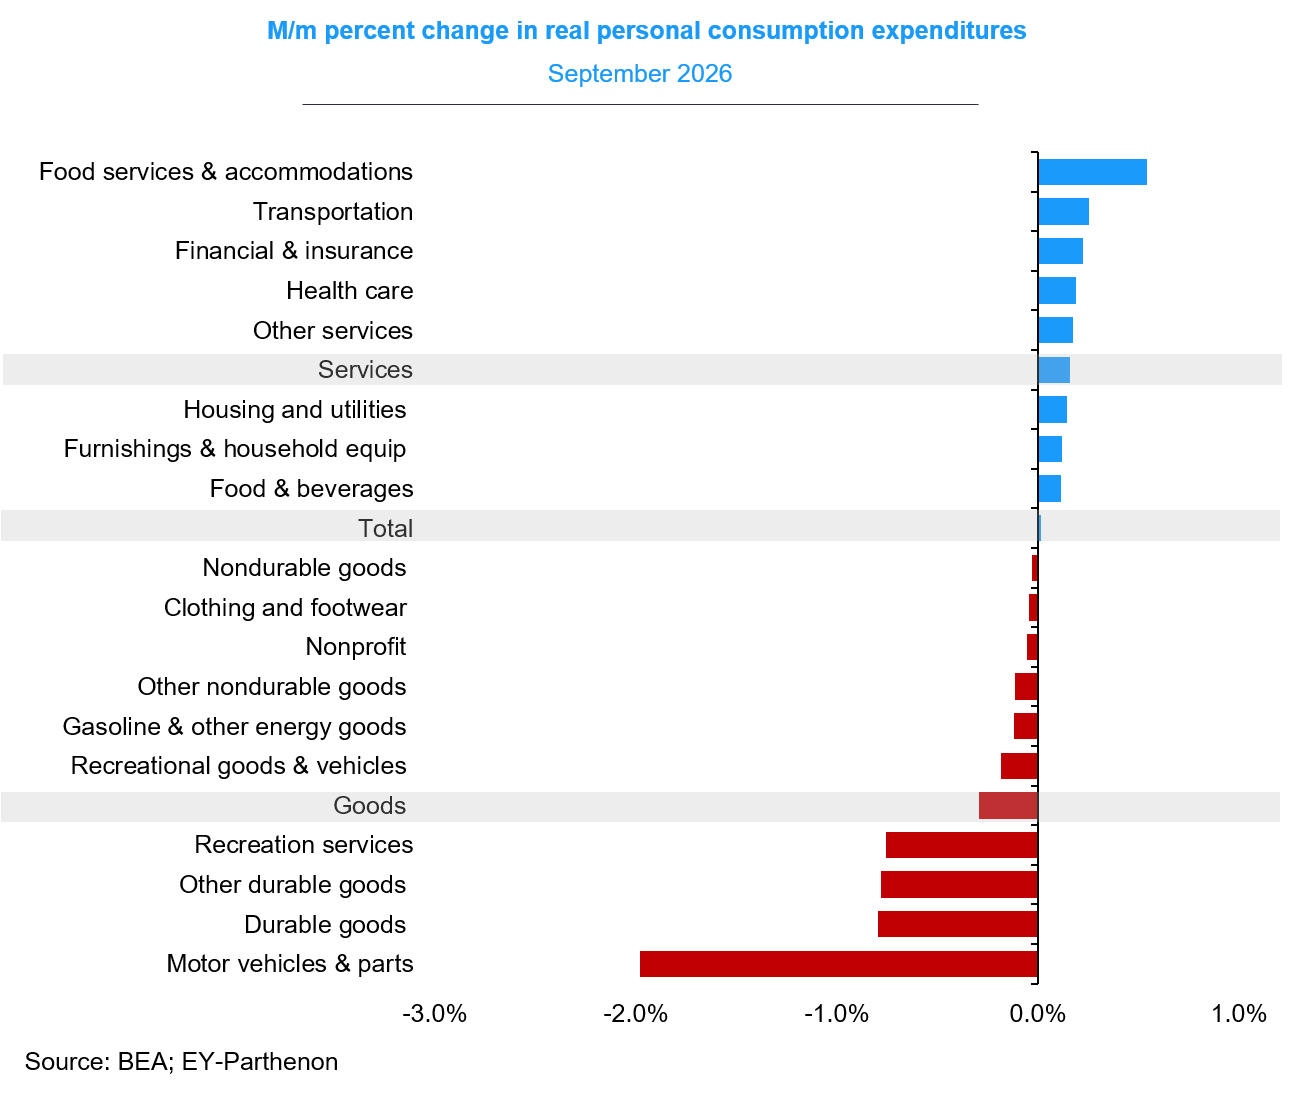
🛍️ Consumer spending ticks higher. BEA data show personal consumption expenditures rose 0.5% month-over-month in September to an annual rate of $22.5 trillion, an all-time high.
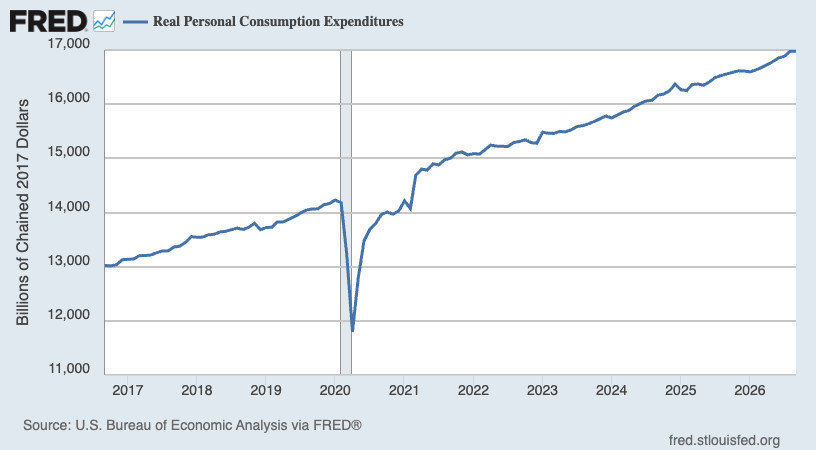
Adjusted for inflation, real personal consumption expenditures was unchanged from the prior month’s all-time high.
Here’s a breakdown of real spending growth by category.
For more on the economy, read: Fortunately, it’s not all bad news 📰
💰The personal saving rate is low, but that’s not obviously a bad sign. Personal saving — disposable personal income minus personal consumption — has been shrinking over the past two years, causing the personal saving rate — personal saving as a percentage of disposable personal income — to trend lower. In September, the saving rate was 3.8%, its lowest level since Oct. 2022.
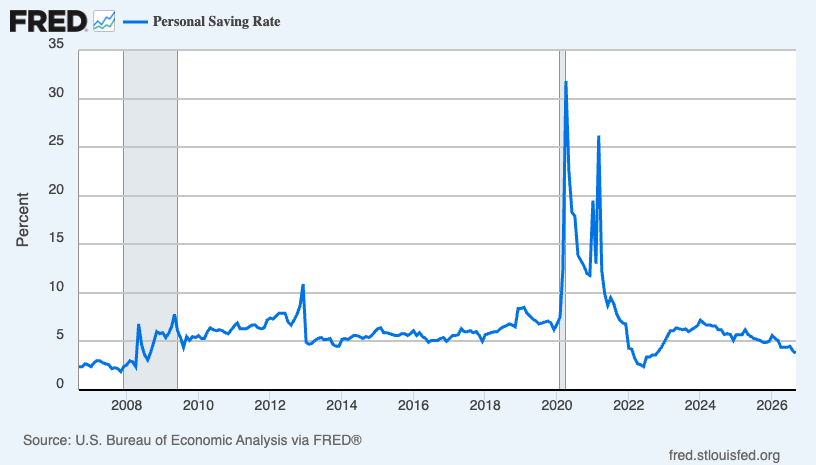
All else equal, this is not great. The implication is that more people are drawing from their savings to support their spending amid inflationary pressures. However, the saving rate tends to decline when net worths are rising. And net worths have been rising, driven by record-high home prices and elevated stock prices.
For more on this dynamic, read: A contrarian note about the falling personal saving rate 💸
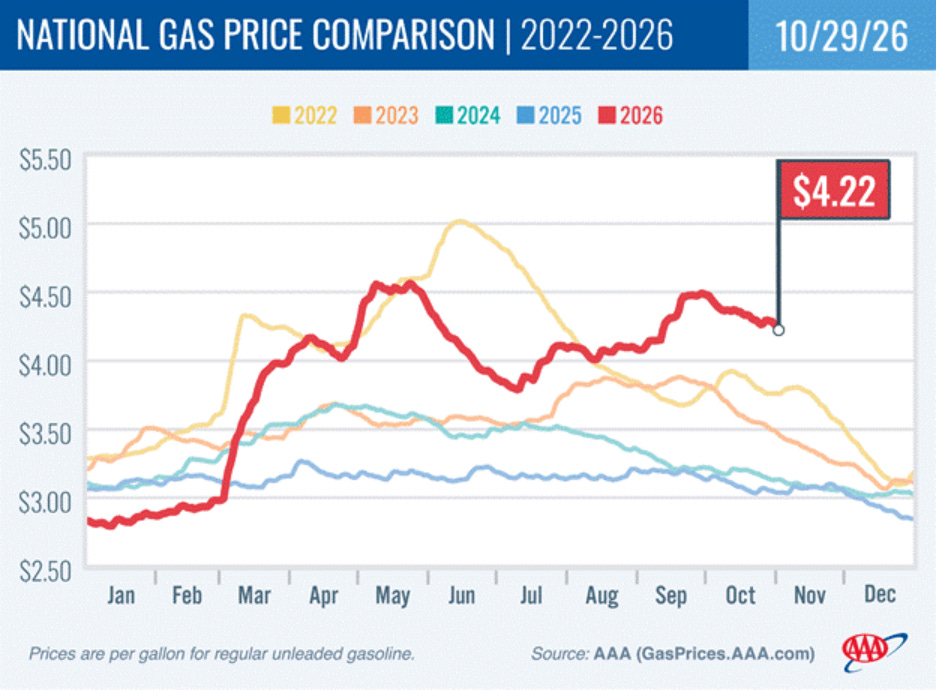
⛽️ Gas prices tick lower, but remain high. From AAA: “The national average for a gallon of regular gasoline fell 5 cents over the past week to $4.22. Crude oil prices above $100 per barrel, however, are limiting further declines at the pump. As drivers fuel up for the weekend, AAA reminds them that Saturday’s trick-or-treating and the end of daylight saving time Sunday call for extra care behind the wheel. With pedestrians out for Halloween and earlier evening darkness ahead, drivers should slow down, put distractions away and watch carefully at crosswalks and in neighborhoods.”
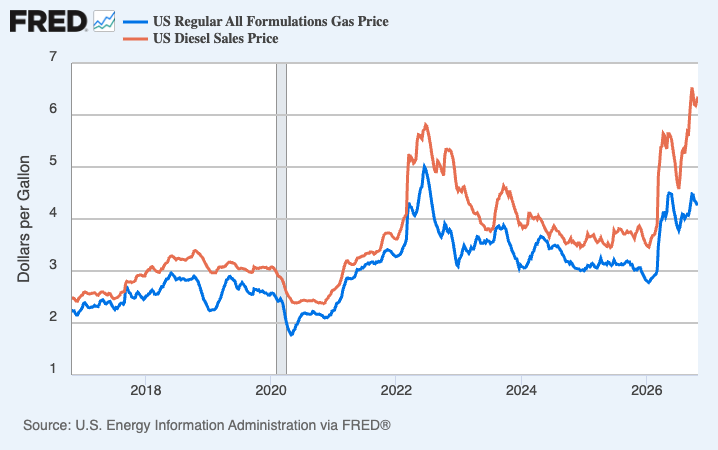
Here’s a longer-term look at gas and diesel price trends, as tracked by the EIA.
For more on energy prices, read: Our love-hate relationship with rising oil prices in charts 💔🛢️📊
💳 Card spending data is holding up. From BofA: “Total card spending per HH was up 6.0% y/y in the week ending Oct 24, according to BAC aggregated credit & debit card data. Spending growth strengthened broadly relative to last week, led by entertainment, clothing, and online retail. Lower-income spending growth has consistently outpaced higher-income spending growth over the past several weeks.”
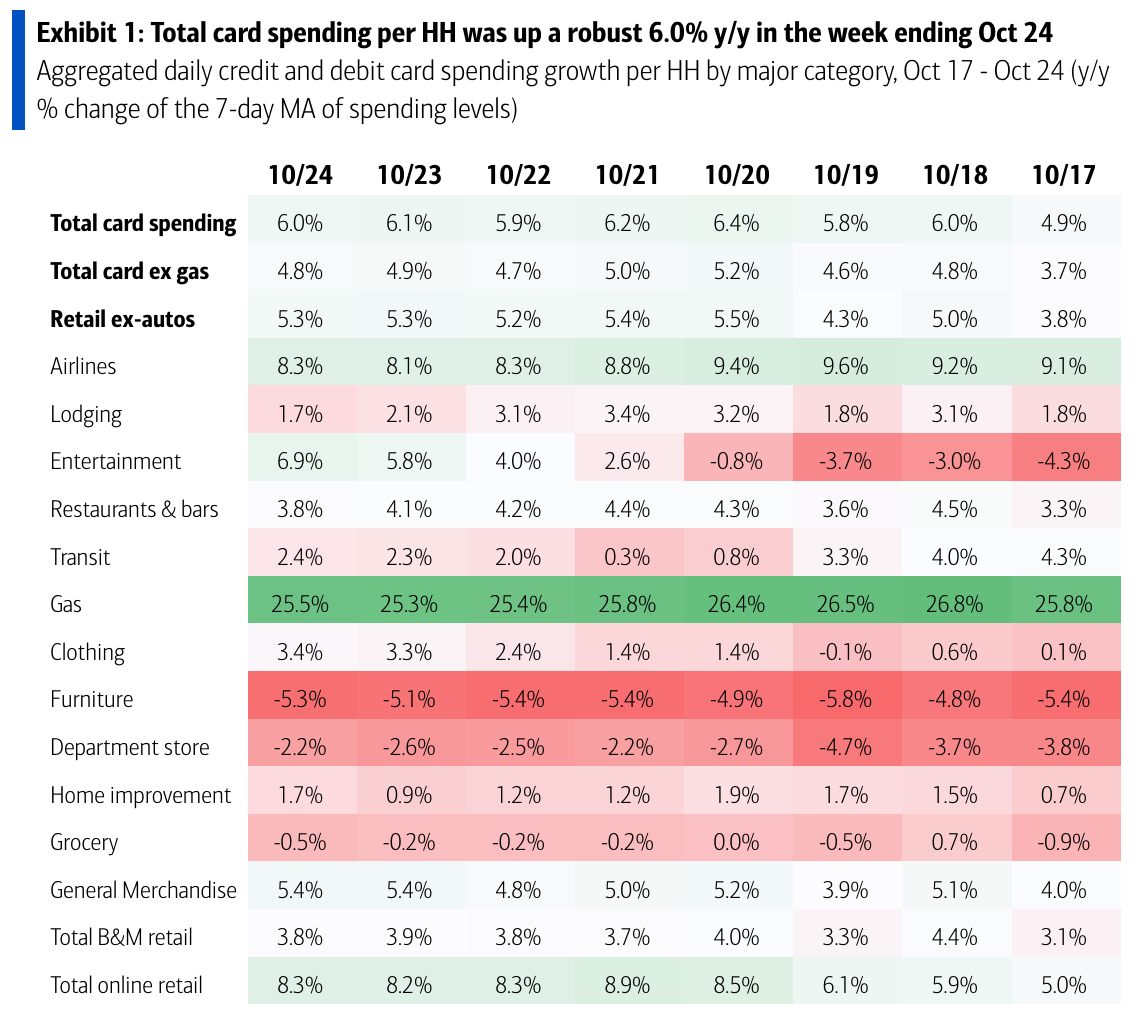
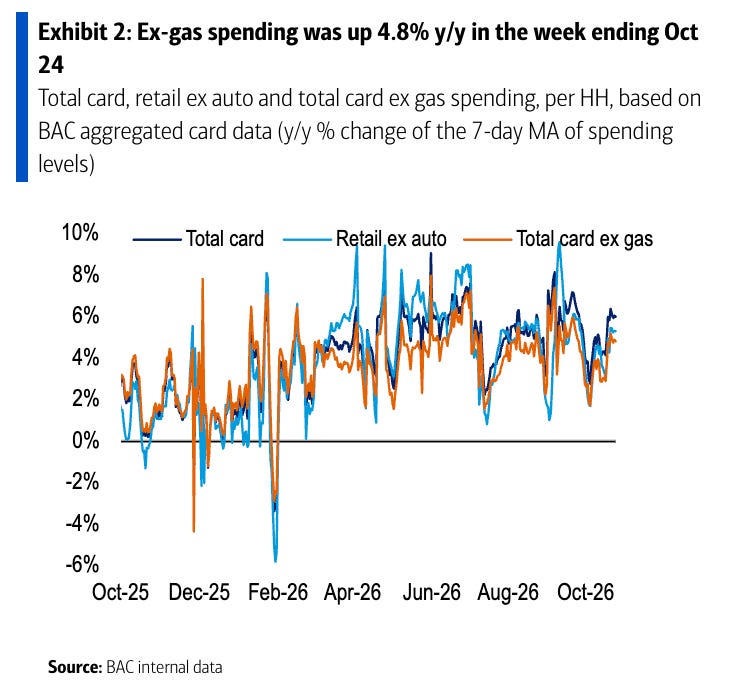
Consumer spending data has looked a lot better than consumer sentiment readings. For more on this contradiction, read: We’re taking that vacation whether we like it or not 🛫 and Household finances are both ‘worse’ and ‘good’ 🌦️
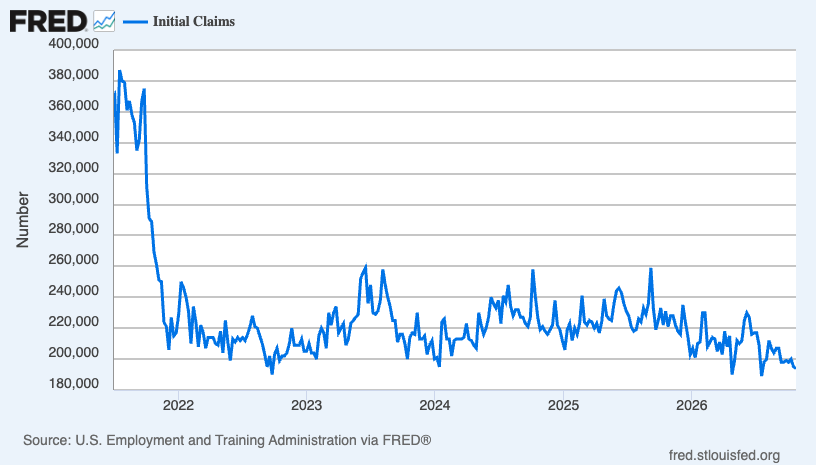
💼 New unemployment insurance claims, total ongoing claims remain low. Initial claims for unemployment benefits ticked down to 194,000 during the week ending Oct. 24, down from 195,000 the week prior. This metric remains at levels historically associated with economic growth.
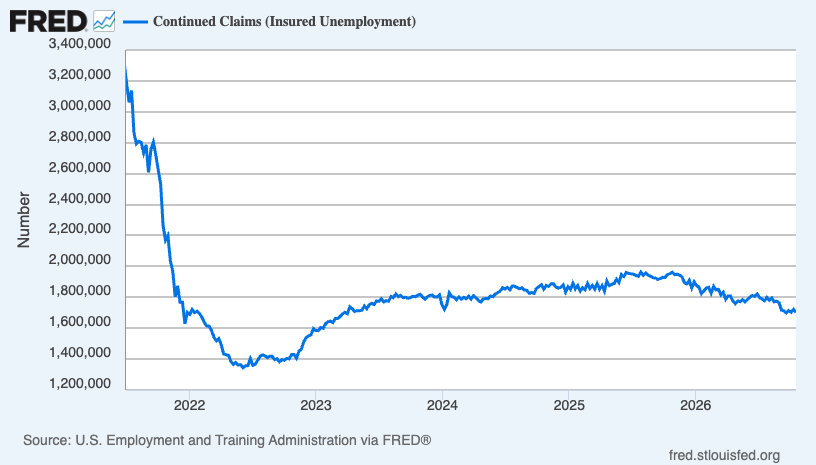
Insured unemployment, which captures those who continue to claim unemployment benefits, declined to 1.70 million during the week ending Oct. 17.
For more on the labor market, read: Why mass tech layoffs have little effect on total employment 💾
🤔 Recent private job growth is positive. According to payroll processor ADP, private U.S. employers added 16,750 jobs in the four weeks ending Oct. 10.
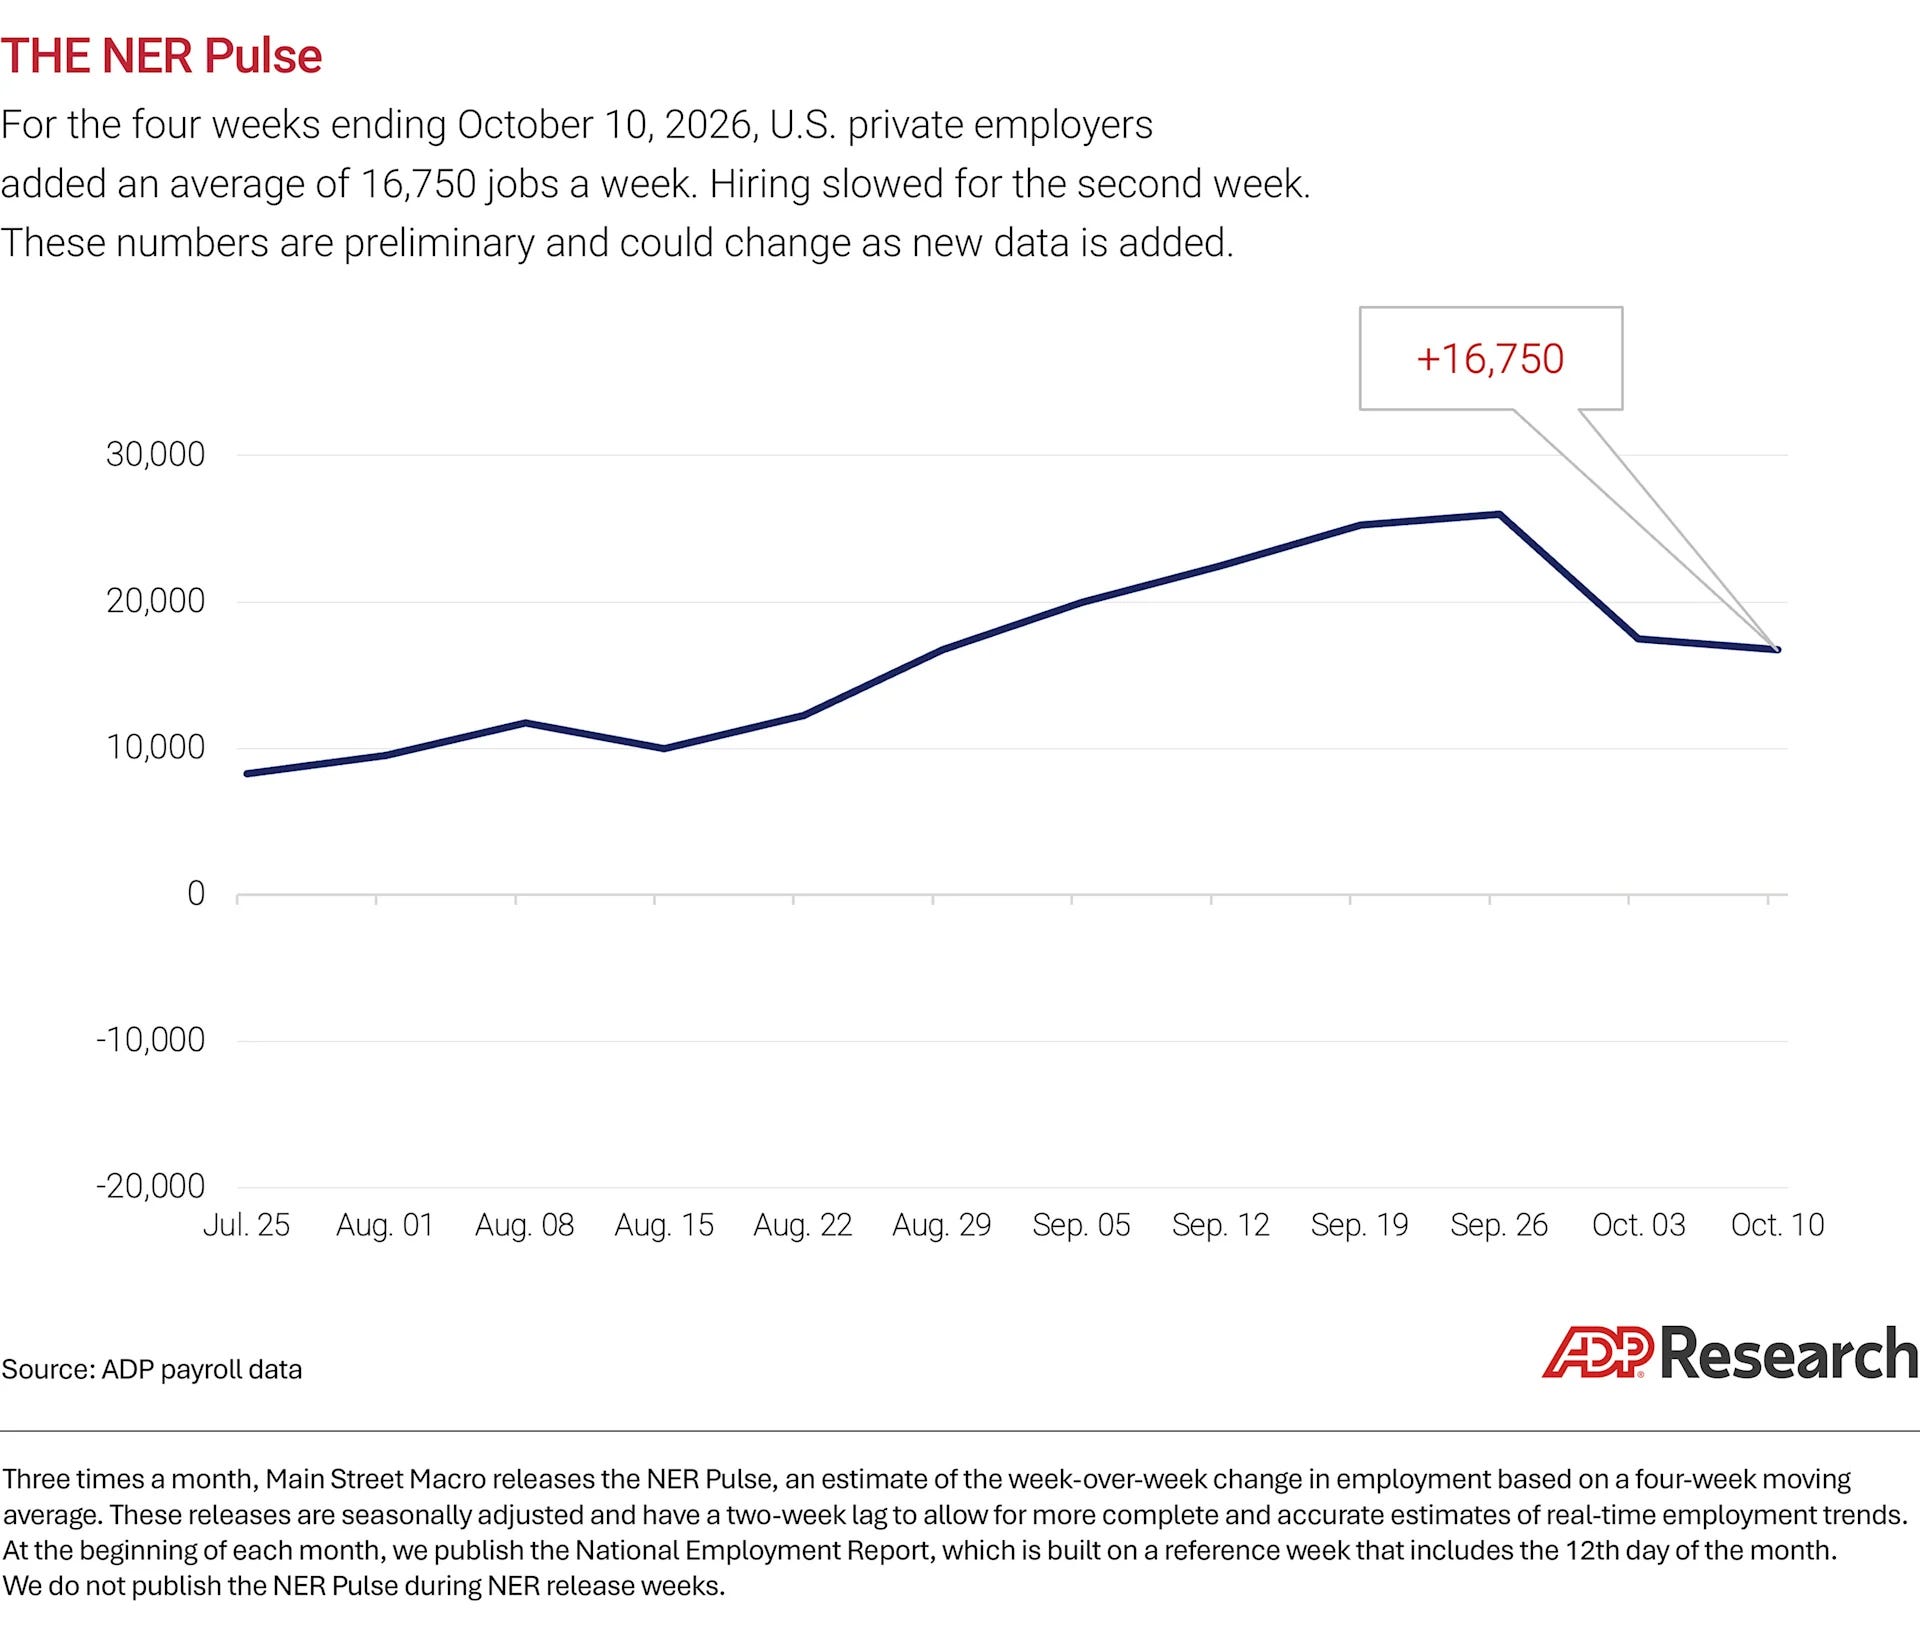
For more on the labor market, read: Things are looking up in the labor market 👍
💵 Key labor costs metric was stable. The employment cost index in Q3 was up 0.8% from the prior quarter.
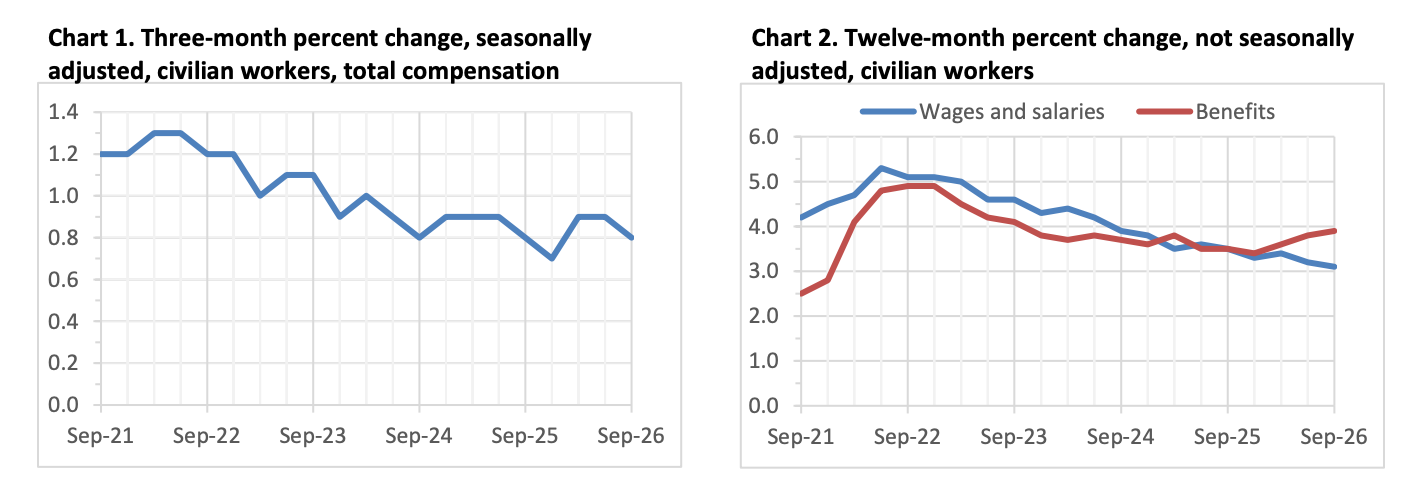
For more on why policymakers are watching wage growth, read: Revisiting the key chart to watch amid the Fed's war on inflation 📈
👎 Consumer vibes tick higher, but remain weak. The Conference Board’s Consumer Confidence Index rose by 7.5 points in October. From the report: “The recovery was in line with retail gasoline prices easing from September to October. Yet, despite the increase in October, consumer confidence remained on the long-term downward trend that’s persisted over the past few years. Consumers planned less spending on services and durable goods over the next six months. This likely reflected higher price levels and persistent inflation, which eroded consumers’ purchasing power.”
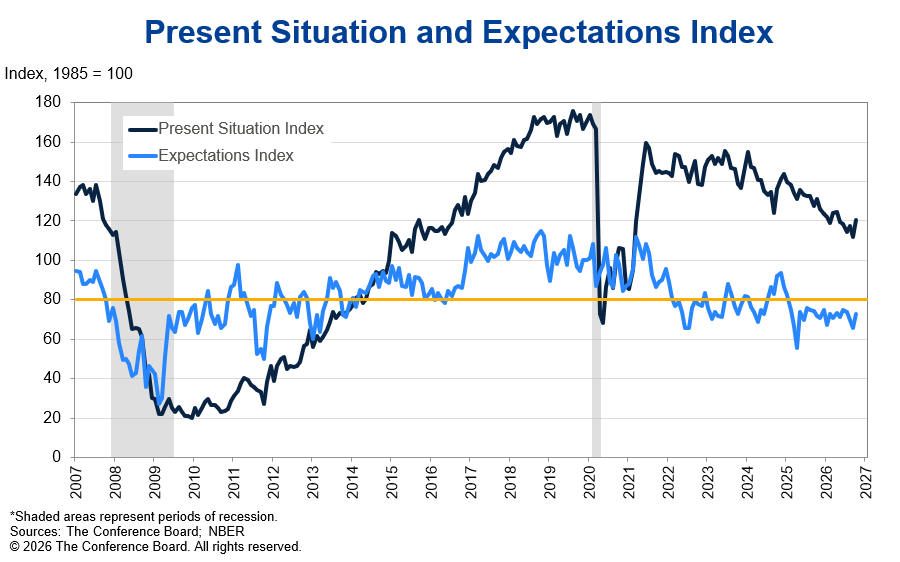
More from the report: “On a six-month moving average basis, only consumers under age 35 and those with a household income of $100k or more expressed an increase in confidence. By generation, confidence amongst Gen X, Baby Boomers, and the Silent Generation continued to trail significantly behind Gen Z and Millennials, widening a sharp generational divide that has emerged over the past two years. In October, confidence improved across all political affiliations—but much more so for Republicans.”
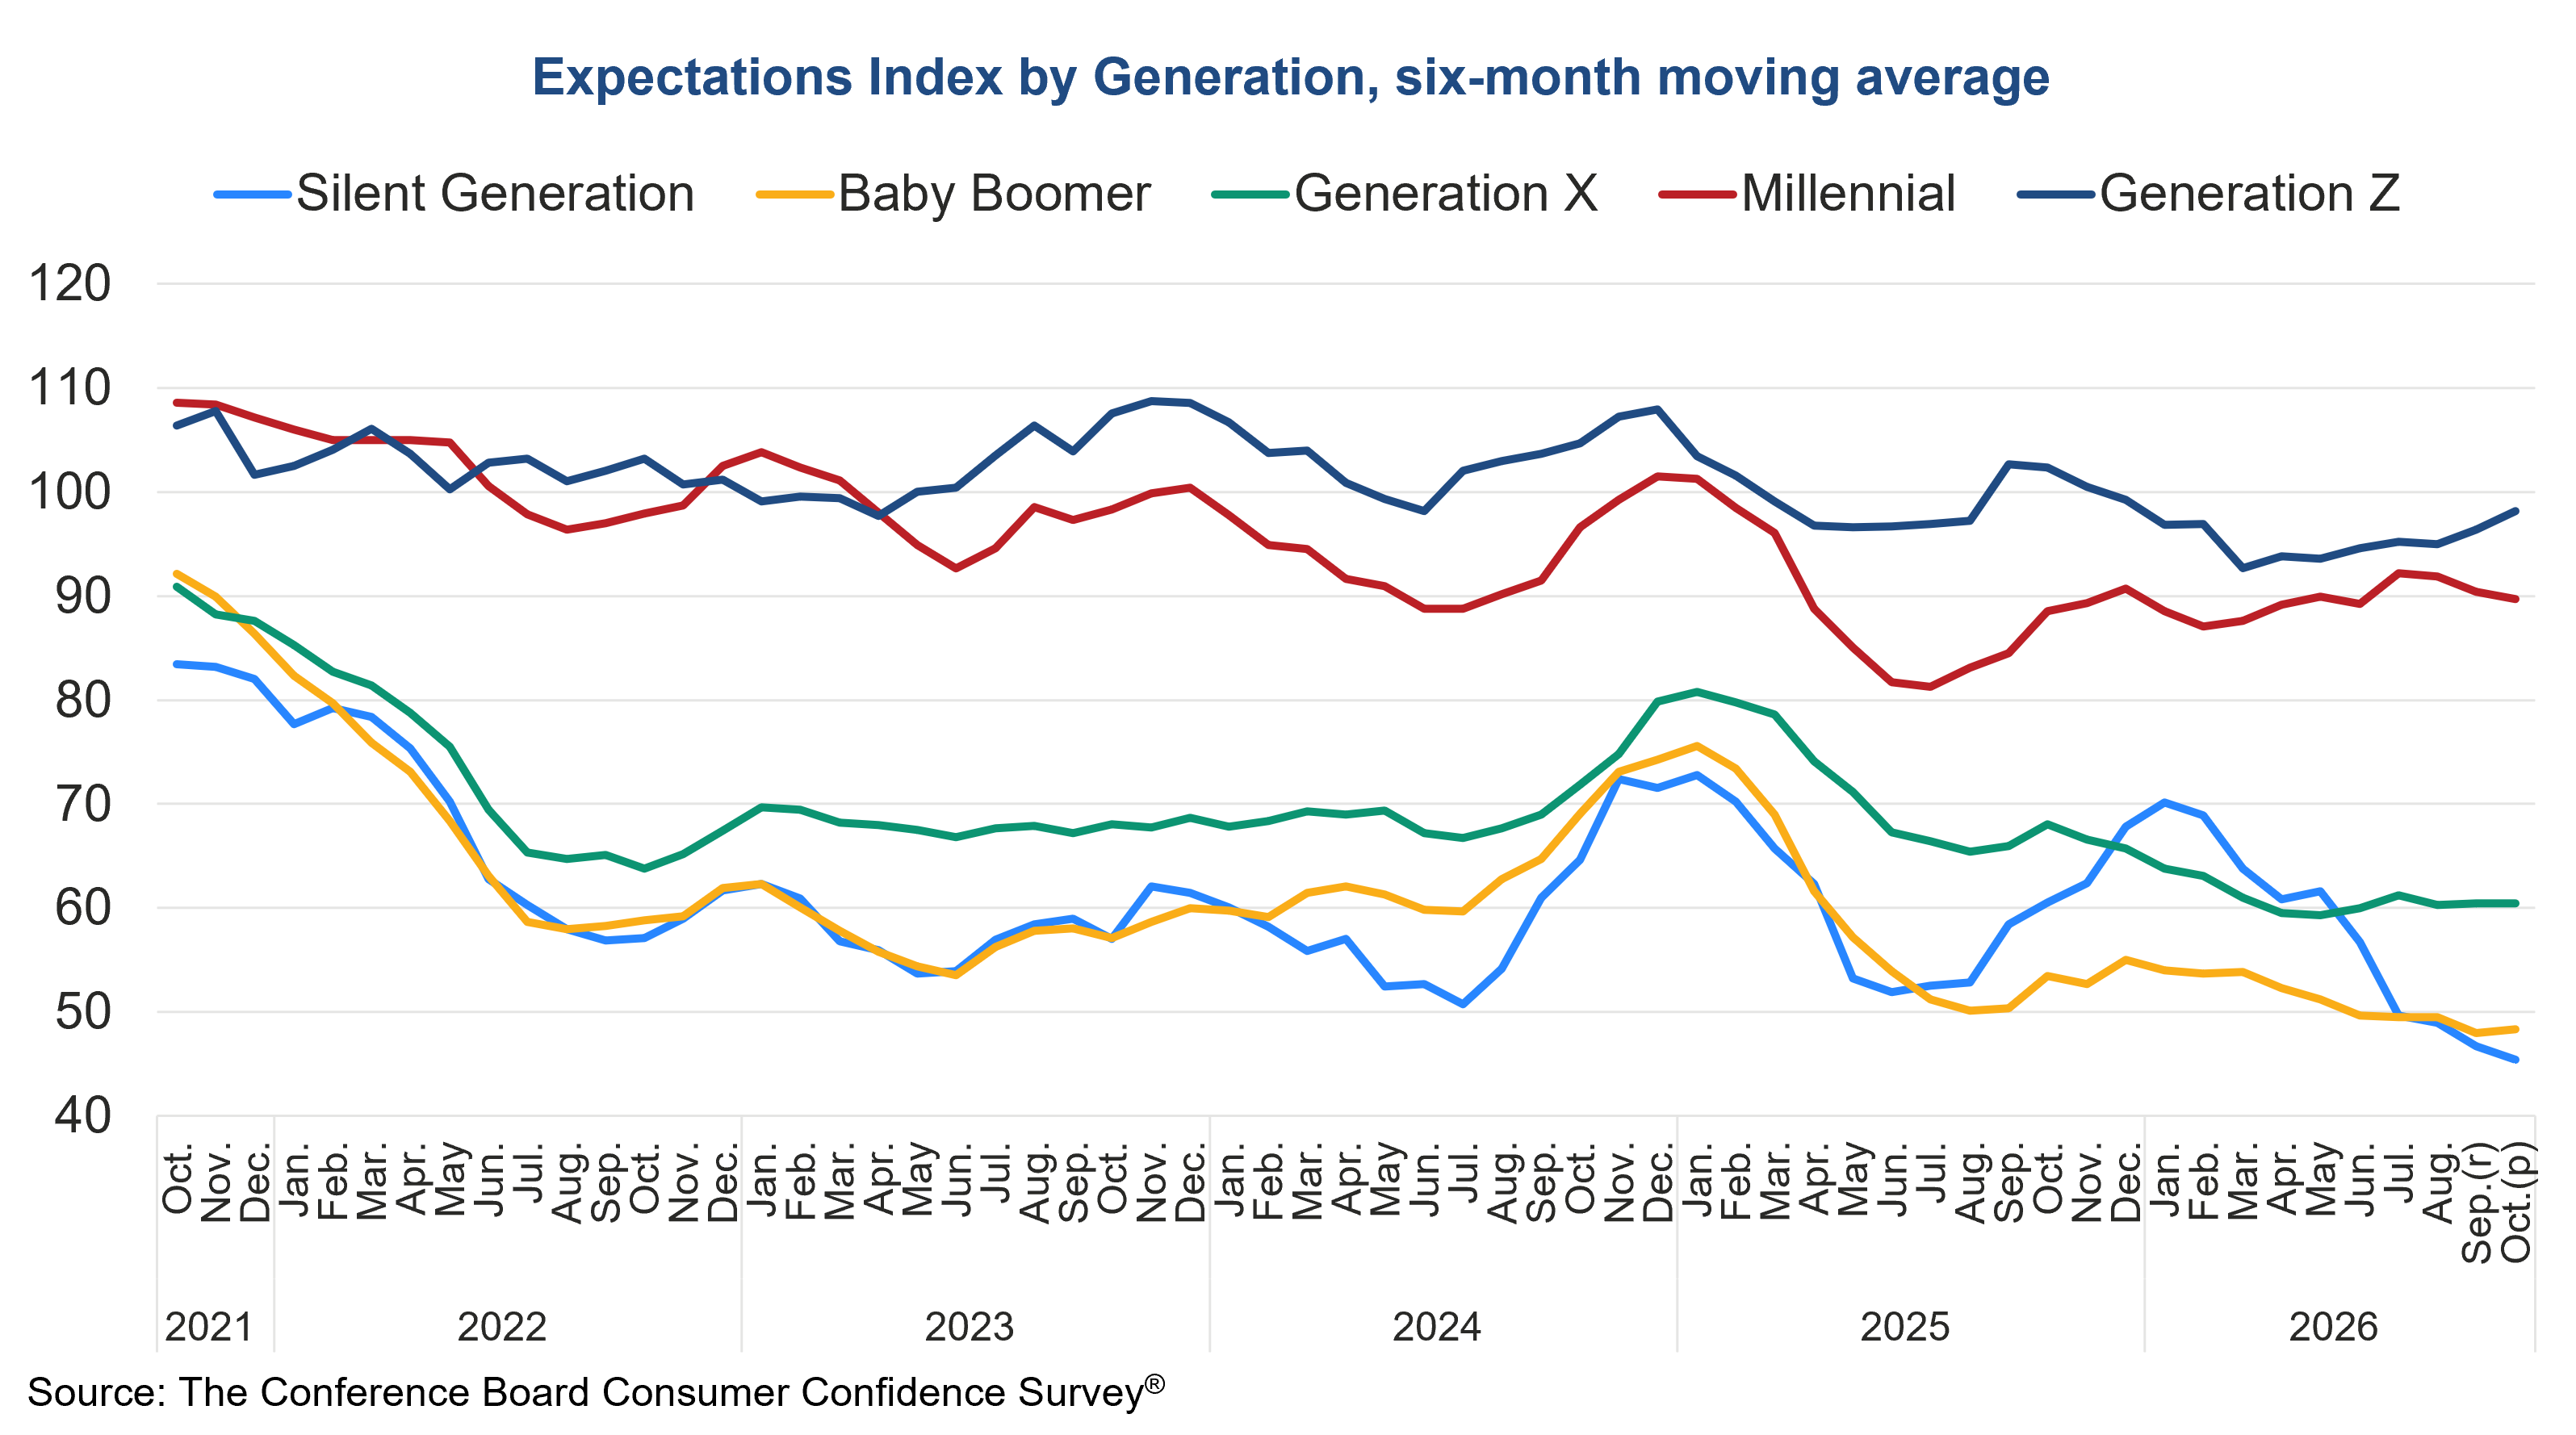
For more on consumer sentiment, read: What consumers do > what consumers say 🙊 and The economy may not be working for everyone right now, but it’s at least working for stock market investors 🎭
👎 Consumers feel only slightly better about the labor market. From The Conference Board: “Consumers’ views of the labor market were more positive in October: 26.7% of consumers said jobs were ‘plentiful,’ up from 24.3% in September. 21.4% of consumers said jobs were ‘hard to get,’ remaining unchanged.”
Many economists monitor the spread between these two percentages (a.k.a., the labor market differential). The direction of the spread reflects a cooling sentiment toward the labor market.
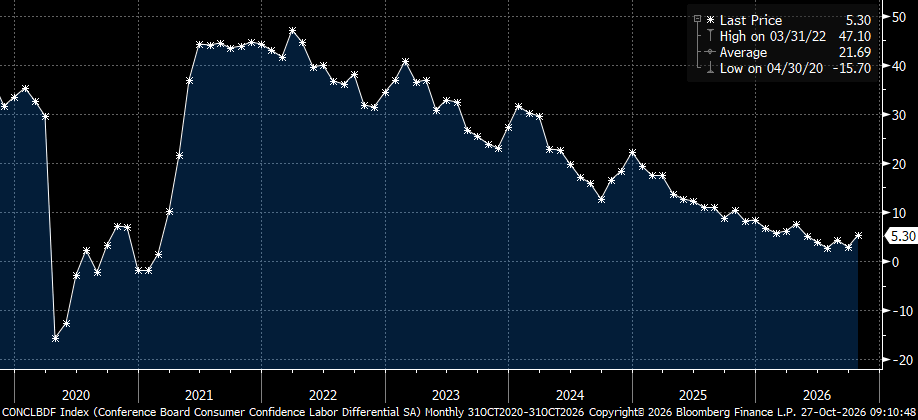
More from The Conference Board: “Consumers were also somewhat less negative about the labor market outlook in October: 15.2% of consumers expected more jobs to be available, up from 14.7% in September. 26.3% expected fewer jobs, down from 27.6%.”
For more on the labor market, read: Things are looking up in the labor market 👍
🏠 Mortgage rates remain elevated. According to Freddie Mac, the average 30-year fixed-rate mortgage ticked down to 7.24%, down from 7.32% last week. It remains near the highest average rate since Nov. 2023.
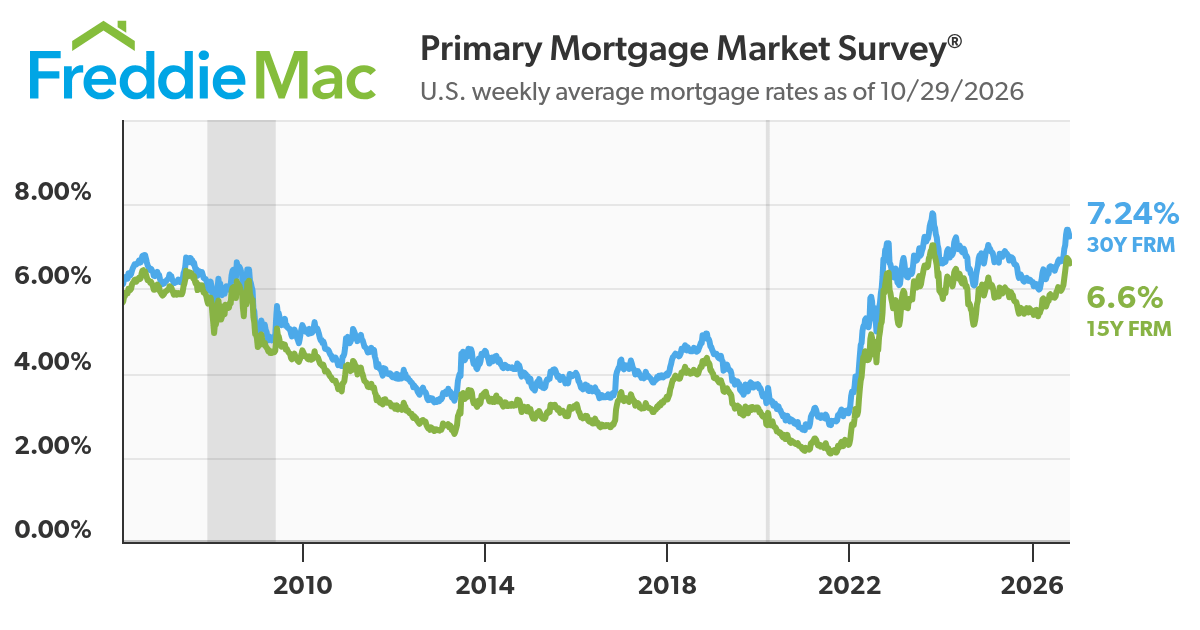
As of Q2, there were 149.5 million housing units in the U.S., of which 87.0 million were owner-occupied and about 40% were mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the weekly movements in home prices or mortgage rates.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
🏘️ New home sales declined. Sales of newly built homes fell 0.6% in September to an annualized rate of 676,000 units.
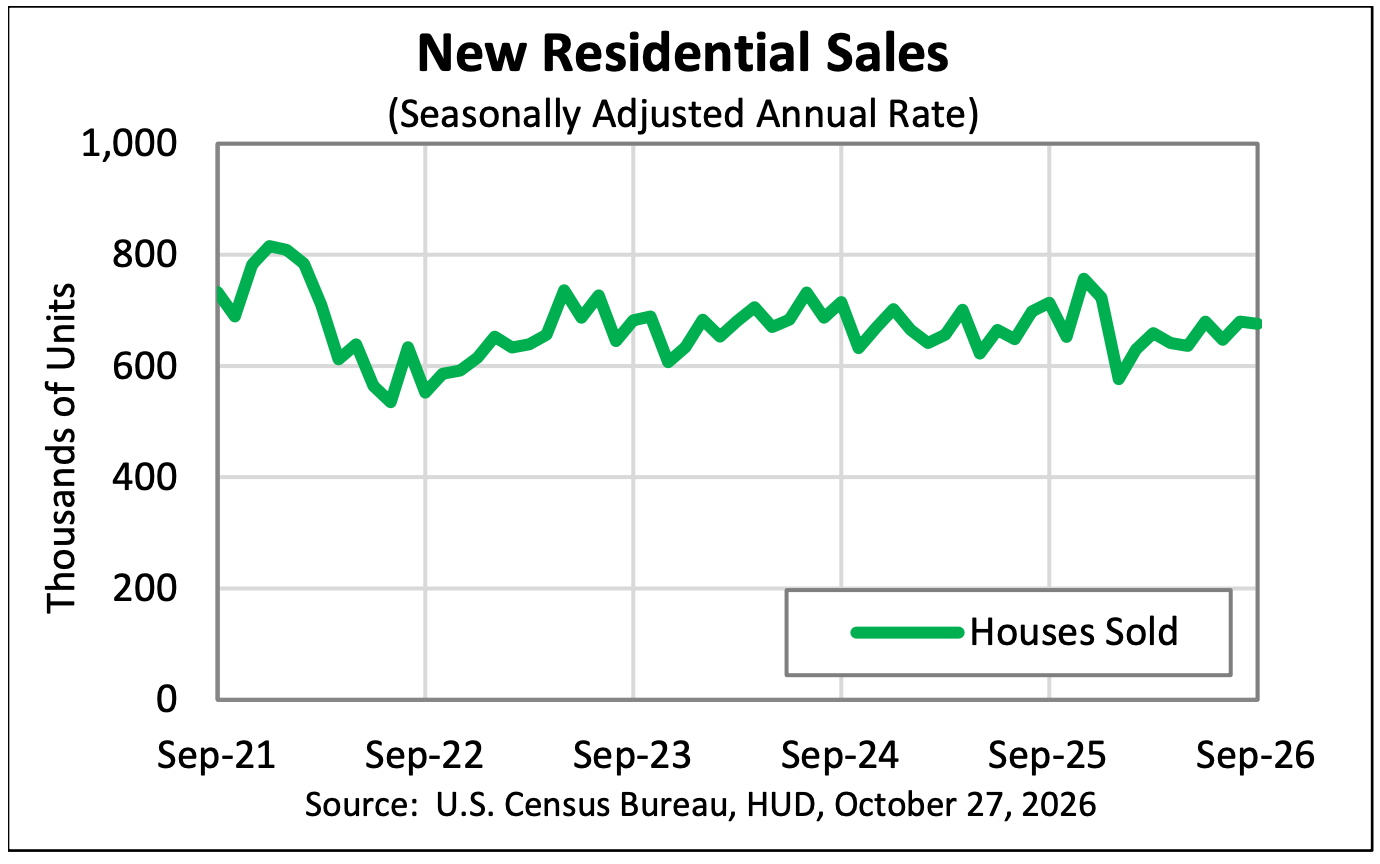
New home sales figures come with a large margin of error. For more on this, read: Mathematical context can totally change the story 🧮
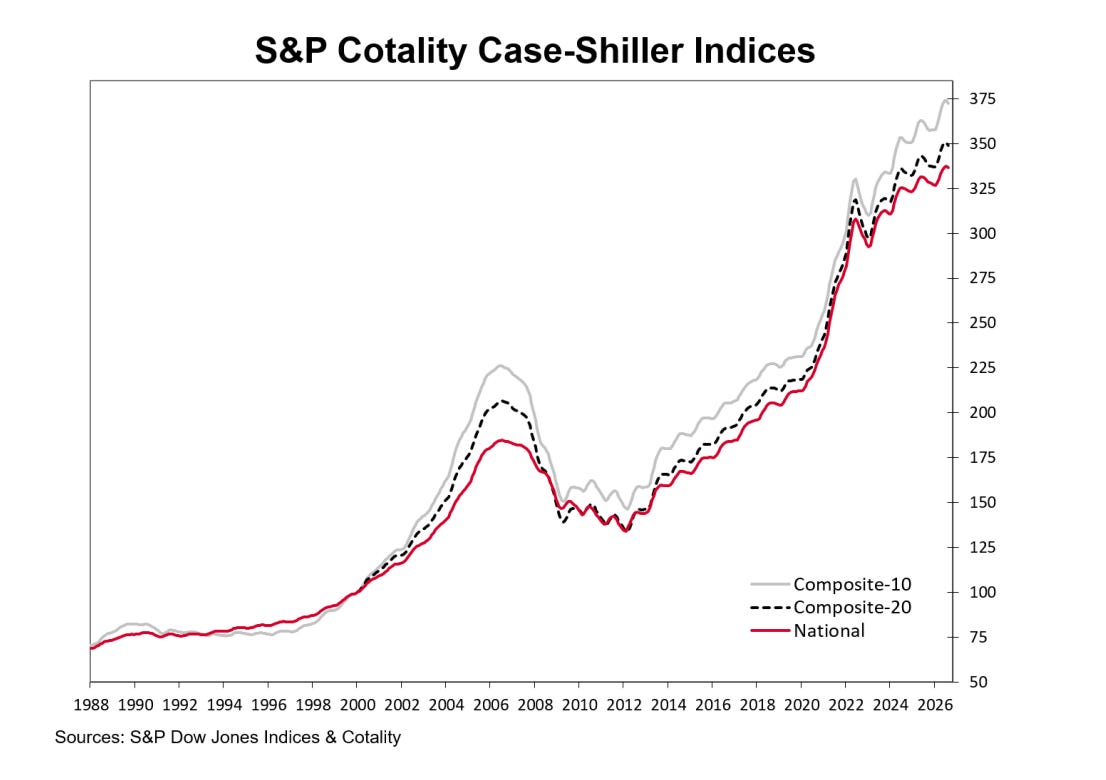
🏠 Home prices rose. According to the S&P CoreLogic Case-Shiller index, home prices were up 2.1% year-over-year in August and 0.3% month-over-month. From S&P Dow Jones Indices’ Rebecca Kaufman: “Affordability, however, remains challenging. With inflation at 3.4%, Brent crude near $100 per barrel and mortgage rates in the mid-to-high 6% range, households continue to face elevated costs alongside persistently high home prices.”
🏭 Business investment activity rose. Orders for nondefense capital goods excluding aircraft — a.k.a. core capex or business investment — increased 0.5% in September to a record $88.0 billion.
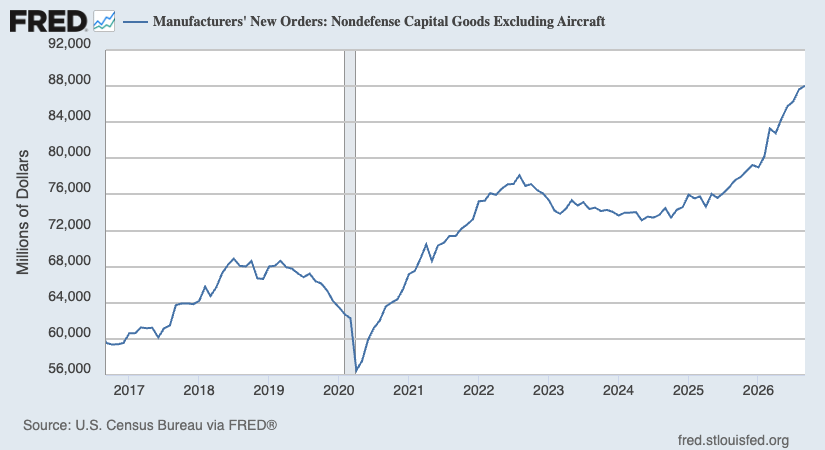
Core capex orders are a leading indicator, meaning they forecast future economic activity.
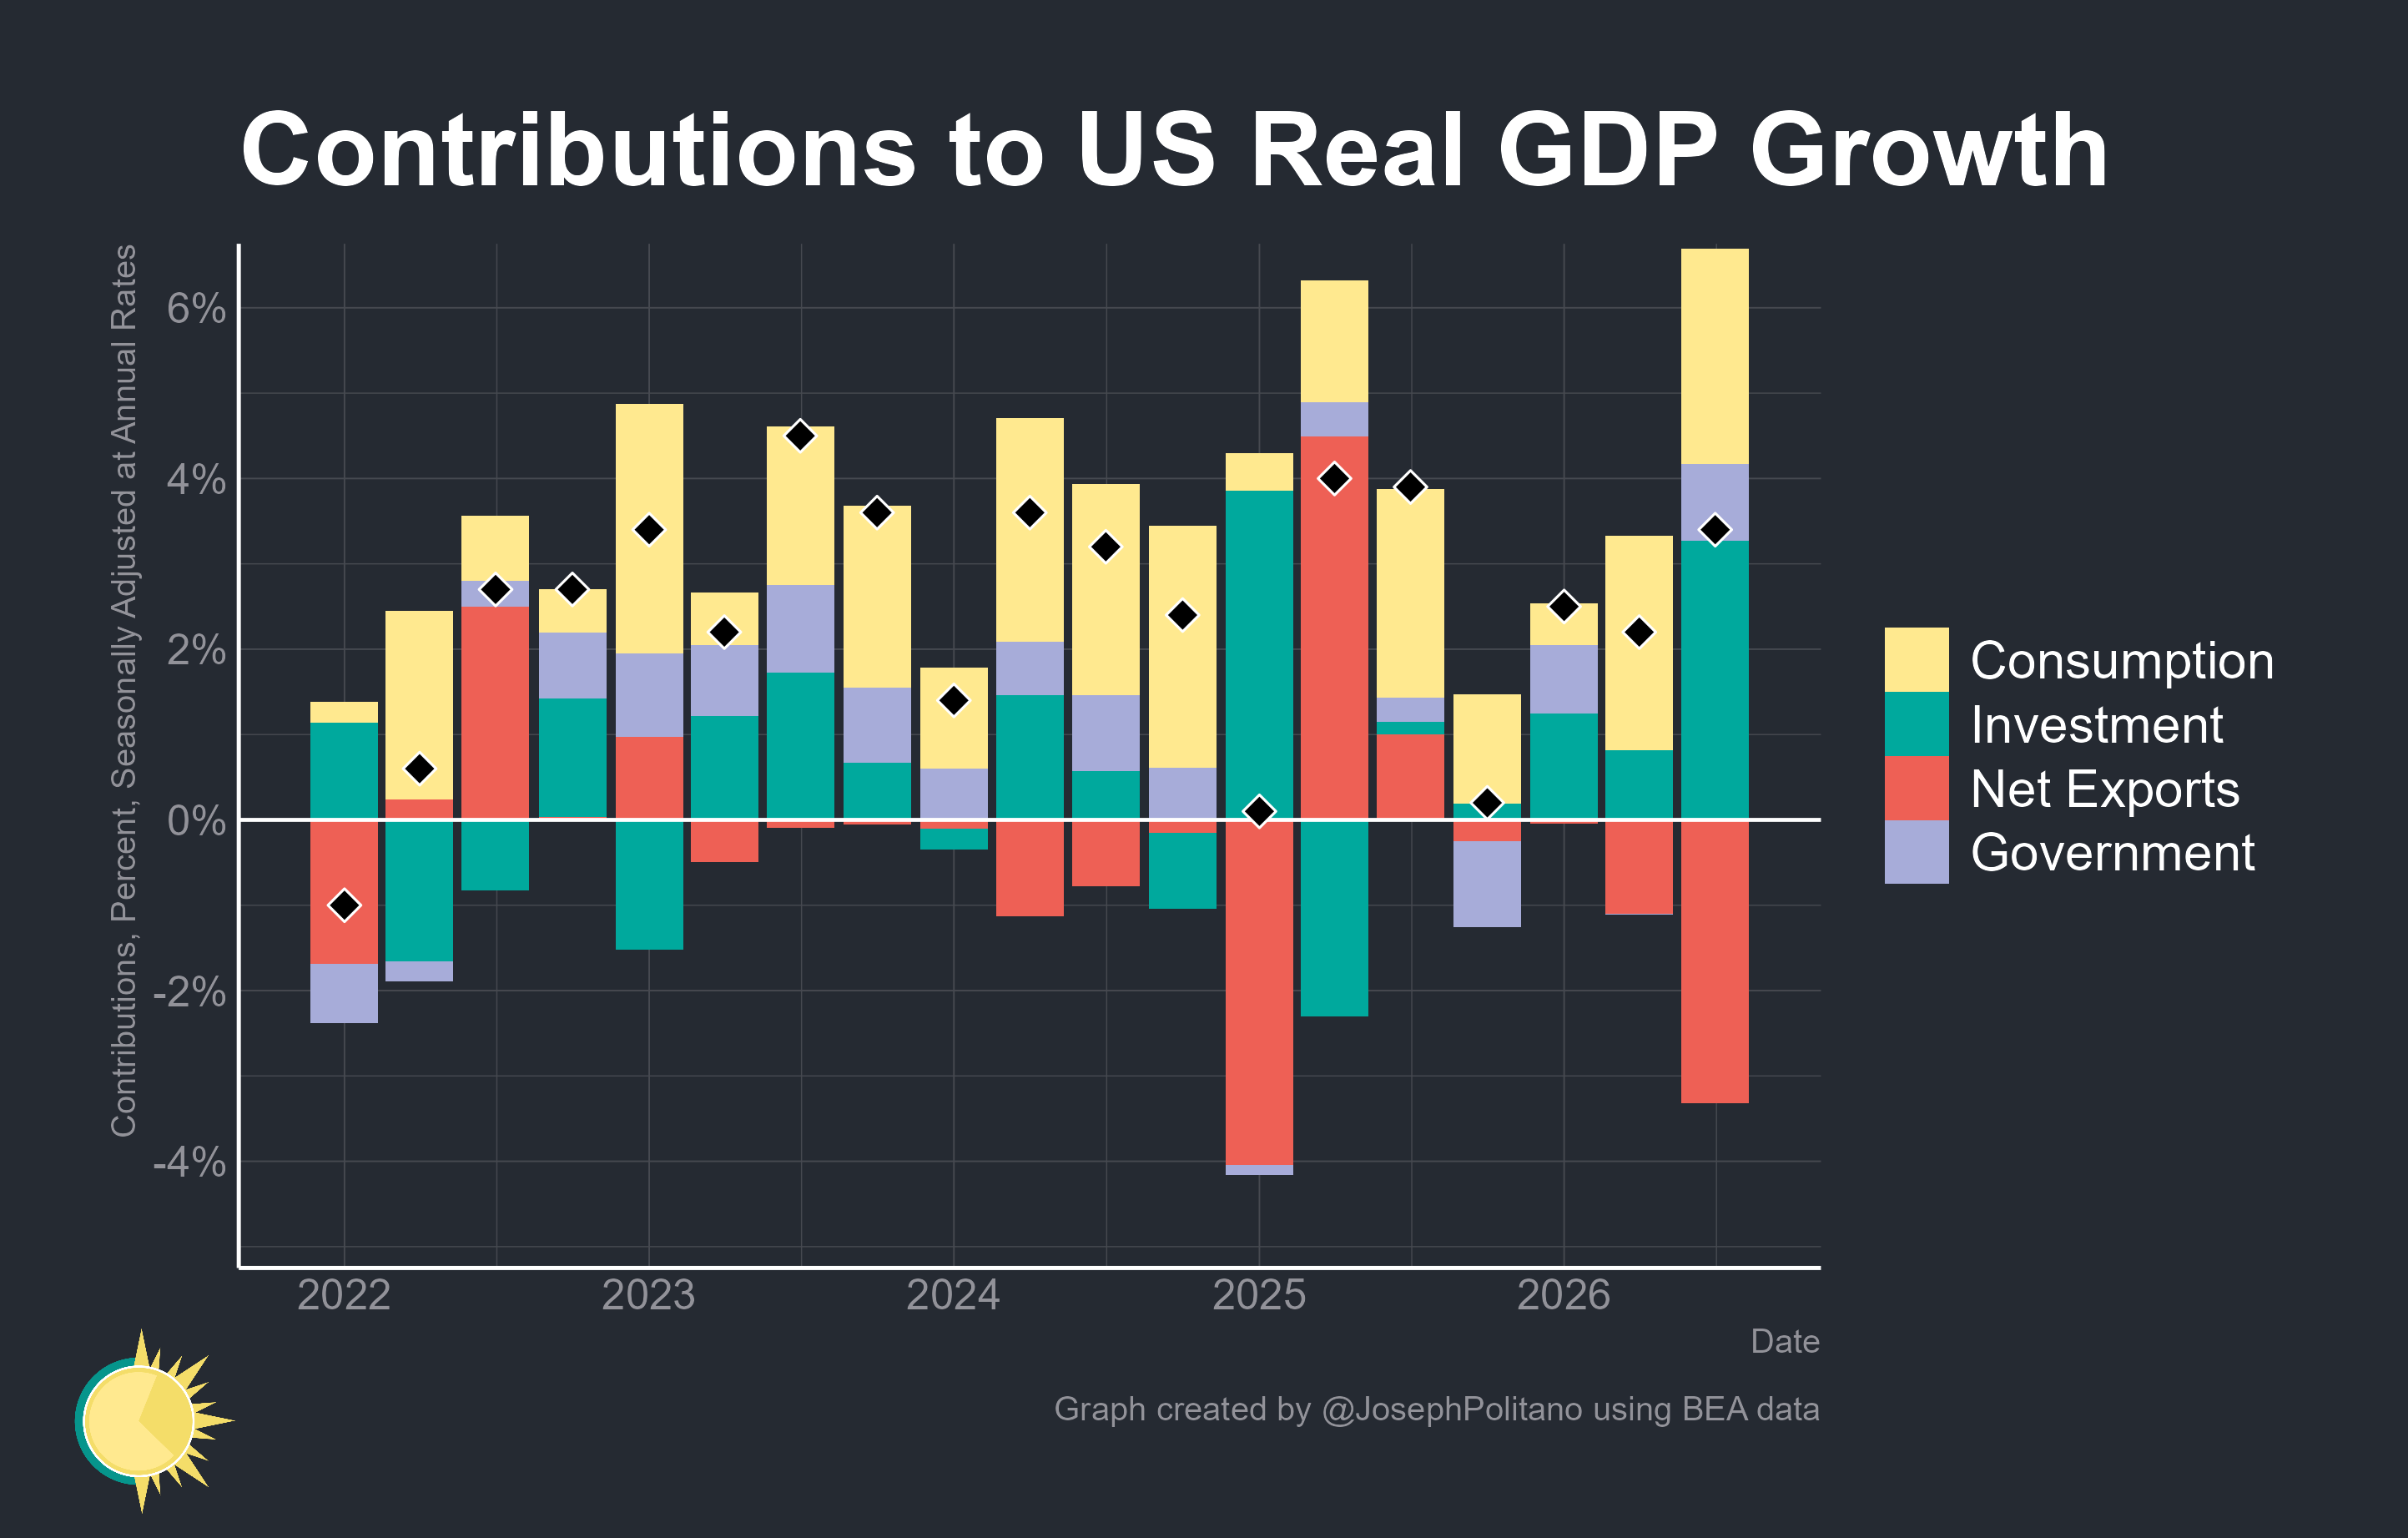
🐇 GDP growth picked up in Q3. U.S. GDP grew at a 3.4% rate in Q3, up from 2.2% in Q2. Consumption and investment led growth, more than offsetting the drag from a wider trade deficit.
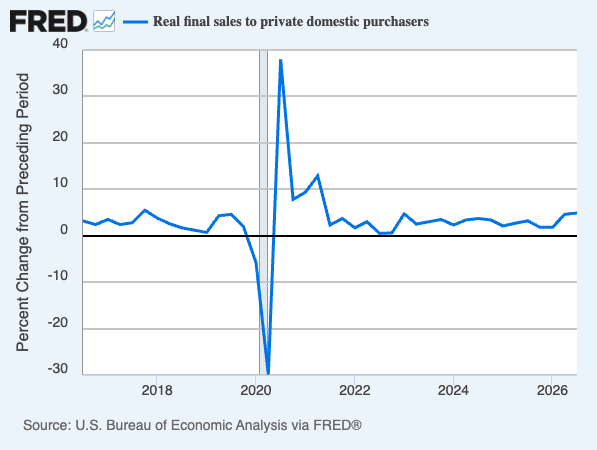
Because the GDP calculation has several quirks, economists often point to “real final sales to private domestic purchasers” to better understand the economy’s underlying health. Sometimes called “core” GDP, this metric excludes net exports, inventory adjustments, and government spending. That metric grew at a 4.9% rate in Q3.
For more on how GDP relates to the economy and the stock market, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and The stock market ≠ the economy ✋
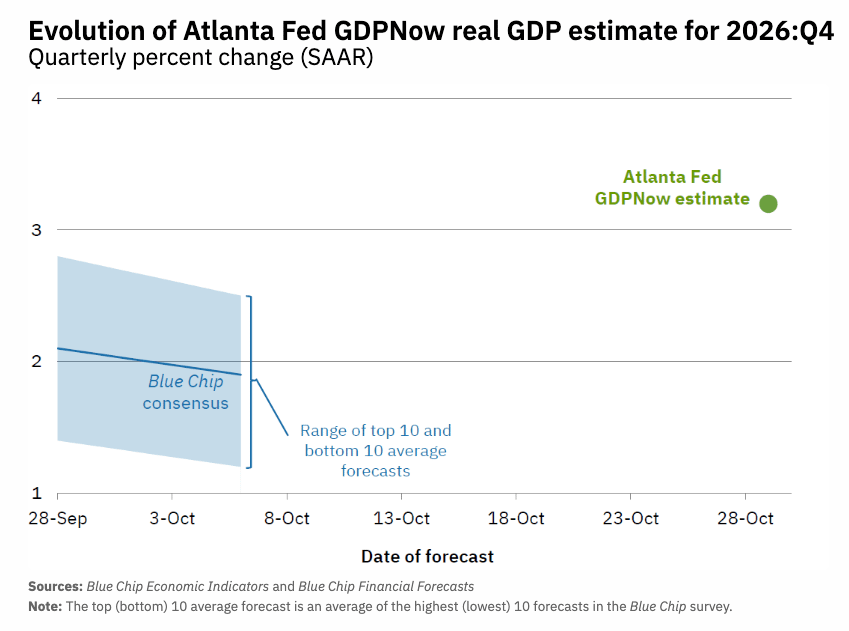
📈 Near-term GDP growth estimates are tracking positively. The Atlanta Fed’s GDPNow model sees real GDP growth rising at a 3.2% rate in Q4.
For more on GDP and the economy, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and Economic data can often be both ‘worse’ and ‘good’ 🌦️
Putting it all together 📋
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Personal spending activity remains at record levels. Core capex orders, which are a leading indicator of business spending, have been trending higher.
Growth rates have cooled: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like job openings and excess savings have faded. Job creation, while positive, is not as hot as it used to be. It has become harder to argue that growth is destiny.
Actions speak louder than words: We are in an odd period, as hard economic data has decoupled from soft, sentiment-driven data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data holds up.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This included strategic layoffs and investment in new equipment, including AI-powered hardware. These moves are driving positive operating leverage, meaning modest sales growth — in the cooling economy — translates into robust earnings growth.
Mind the ever-present risks: We should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyberattacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term market volatility.
Investing is never a smooth ride: Economic recessions and bear markets are harsh realities that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
Think long-term: For now, there’s no reason to believe the economy and the markets will face a challenge they can’t overcome. The long game remains undefeated, and long-term investors can expect that streak to continue.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
Key insights about the stock market 📈
Here’s a roundup of some of TKer’s most talked-about paid and free newsletters about the stock market. All of the headlines are hyperlinked to the archived pieces.
10 truths about the stock market 📈
The stock market can be intimidating: It’s real money on the line, the information is overwhelming, and people can lose fortunes very quickly. But it’s also where thoughtful investors have long accumulated wealth. The main difference between those two outlooks comes down to misconceptions about the stock market that can lead people to make poor investment decisions.
The makeup of the S&P 500 is constantly changing 🔀
Passive investing usually means buying and holding a fund that tracks an index. And no passive investment strategy has attracted as much attention as buying an S&P 500 index fund. However, the S&P 500 — an index of 500 of the largest U.S. companies — is anything but a static set of 500 stocks.

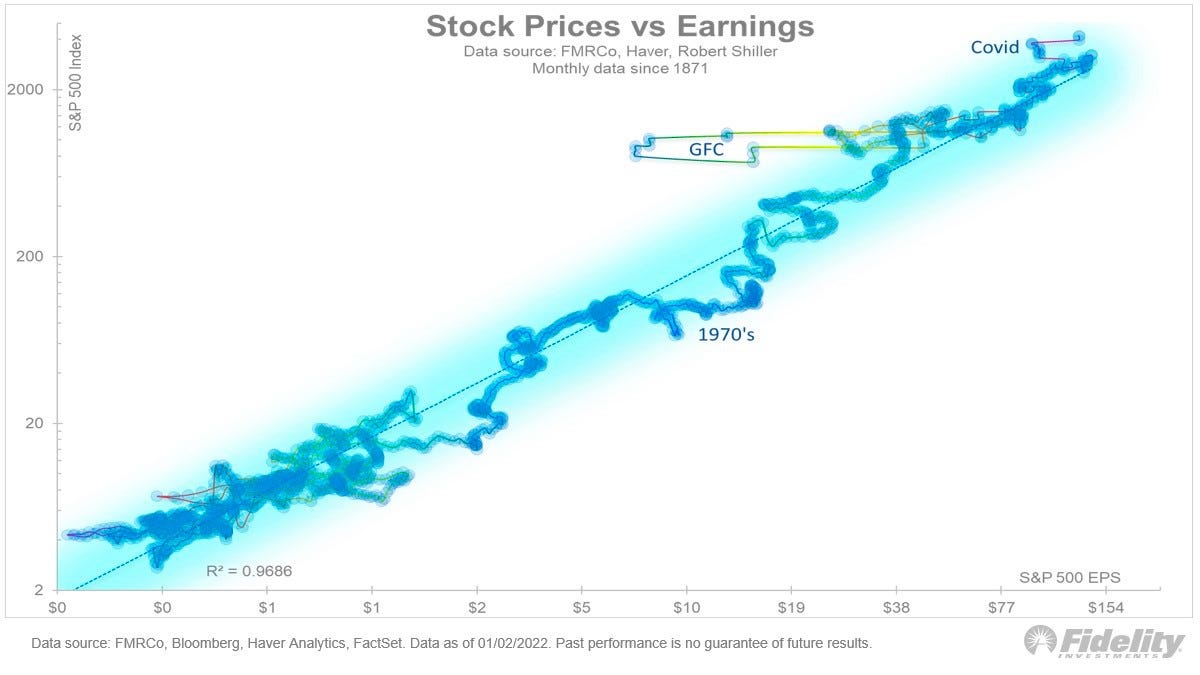
The key driver of stock prices: Earnings💰
For investors, anything you can ever learn about a company matters only if it also tells you something about earnings. That’s because a stock's long-term moves can ultimately be explained by the underlying company’s earnings, earnings expectations, and uncertainty about those expectations. Over time, stock prices and earnings have a very tight statistical relationship.
Stomach-churning stock market sell-offs are normal🎢
Investors should always be mentally prepared for major stock market sell-offs. It’s part of the deal when you invest in an asset class that is sensitive to the constant flow of good and bad news. Since 1950, the S&P 500 has averaged a max annual drawdown (i.e., the biggest intra-year sell-off) of 14%.
How the stock market performed around recessions 📉📈
Every recession in history was different. And stock performance around them varied widely. There are two things worth noting. First, recessions have always been accompanied by a significant drawdown in stock prices. Second, the stock market bottomed and inflected upward long before recessions ended.

In the stock market, time pays ⏳
Since 1928, the S&P 500 has generated a positive total return in more than 89% of five-year periods. Those are pretty good odds. When you extend the timeframe to 20 years, you’ll see that the S&P 500 has never had a period where it didn’t generate a positive return.

What a strong dollar means for stocks 👑
While a strong dollar may be great news for Americans vacationing abroad and U.S. businesses importing goods from overseas, it’s a headwind for multinational U.S.-based corporations doing business in non-U.S. markets.

Stanley Druckenmiller’s No. 1 piece of advice for novice investors 🧐
…you don’t want to buy them when earnings are great, because what are they doing when their earnings are great? They go out and expand capacity. Three or four years later, there’s overcapacity and they’re losing money. What about when they’re losing money? Well, then they’ve stopped building capacity. So three or four years later, capacity will have shrunk and their profit margins will be way up. So, you always have to sort of imagine the world the way it’s going to be in 18 to 24 months as opposed to now. If you buy it now, you’re buying into every single fad every single moment. Whereas if you envision the future, you’re trying to imagine how that might be reflected differently in security prices.
Peter Lynch made a remarkably prescient market observation in 1994 🎯
Some event will come out of left field, and the market will go down, or the market will go up. Volatility will occur. Markets will continue to have these ups and downs. … Basic corporate profits have grown about 8% a year historically. So, corporate profits double about every nine years. The stock market ought to double about every nine years… The next 500 points, the next 600 points — I don’t know which way they’ll go… They’ll double again in eight or nine years after that. Because profits go up 8% a year, and stocks will follow. That’s all there is to it.
Warren Buffett’s ‘fourth law of motion’ 📉
Long ago, Sir Isaac Newton gave us three laws of motion, which were the work of genius. But Sir Isaac’s talents didn’t extend to investing: He lost a bundle in the South Sea Bubble, explaining later, “I can calculate the movement of the stars, but not the madness of men.” If he had not been traumatized by this loss, Sir Isaac might well have gone on to discover the Fourth Law of Motion: For investors as a whole, returns decrease as motion increases.
Most pros can’t beat the market 🥊
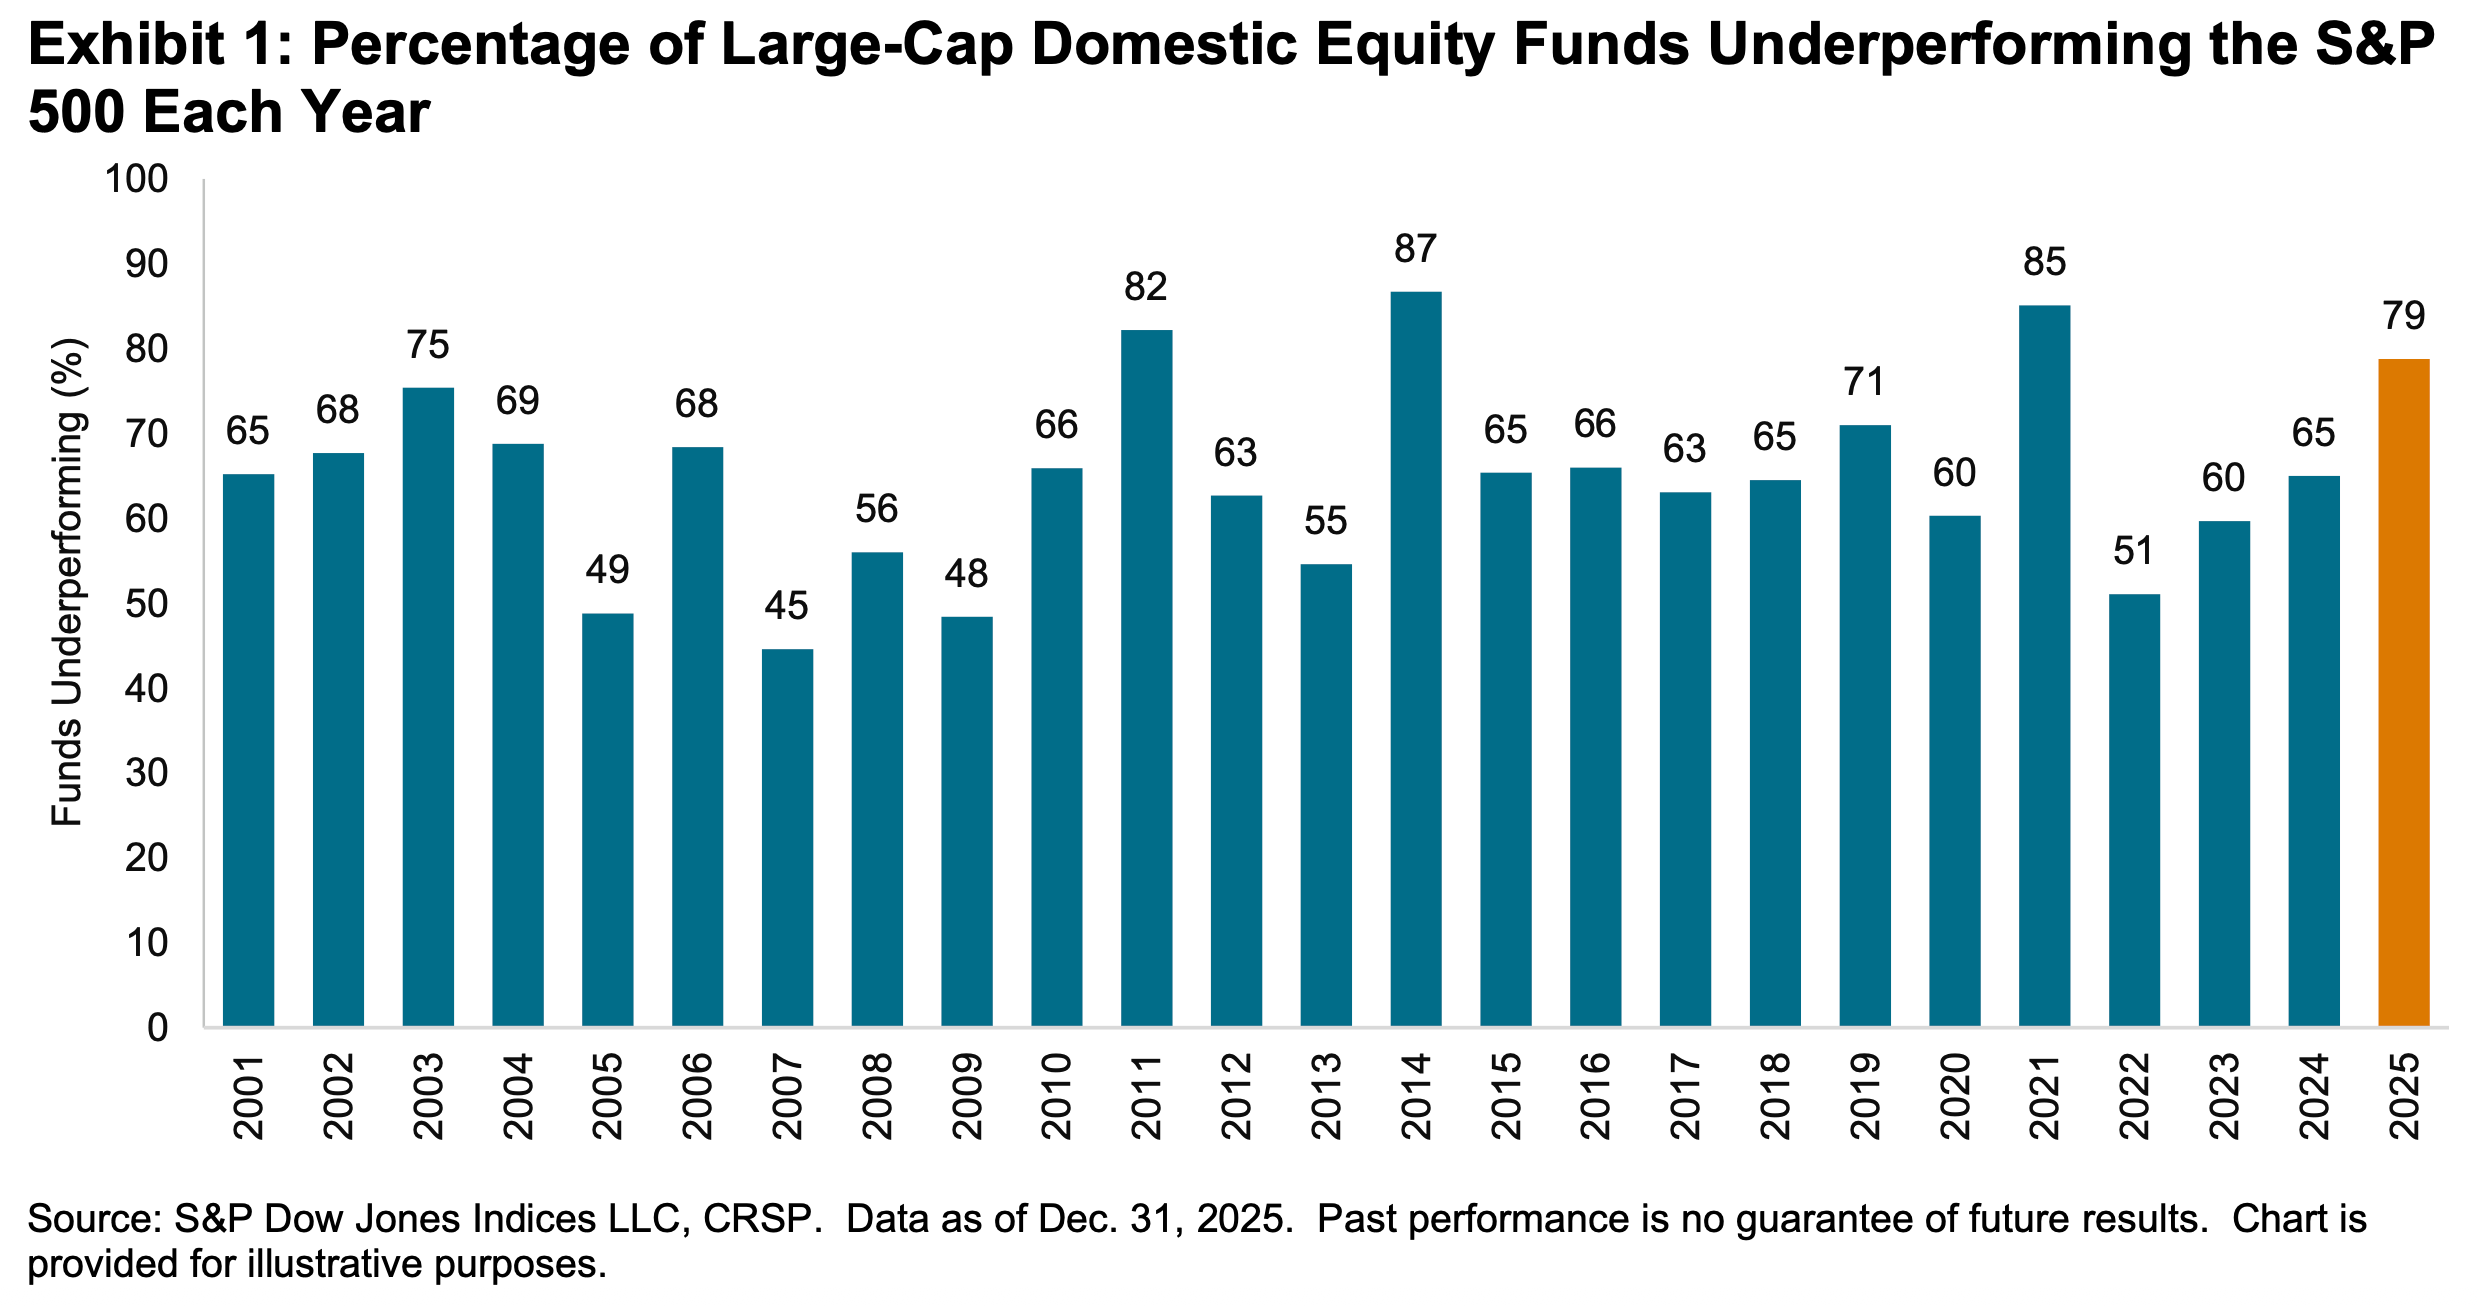
According to S&P Dow Jones Indices (SPDJI), 79% of U.S. large-cap equity fund managers underperformed the S&P 500 in 2025. As you extend the time horizon, the numbers get even worse. Over three years, 67% underperformed. Over 5 years, 89% underperformed. And over 20 years, 93% underperformed. This 2025 performance marked the 16th consecutive year the majority of fund managers in this category have lagged the index.
Proof that ‘past performance is no guarantee of future results’ 📊
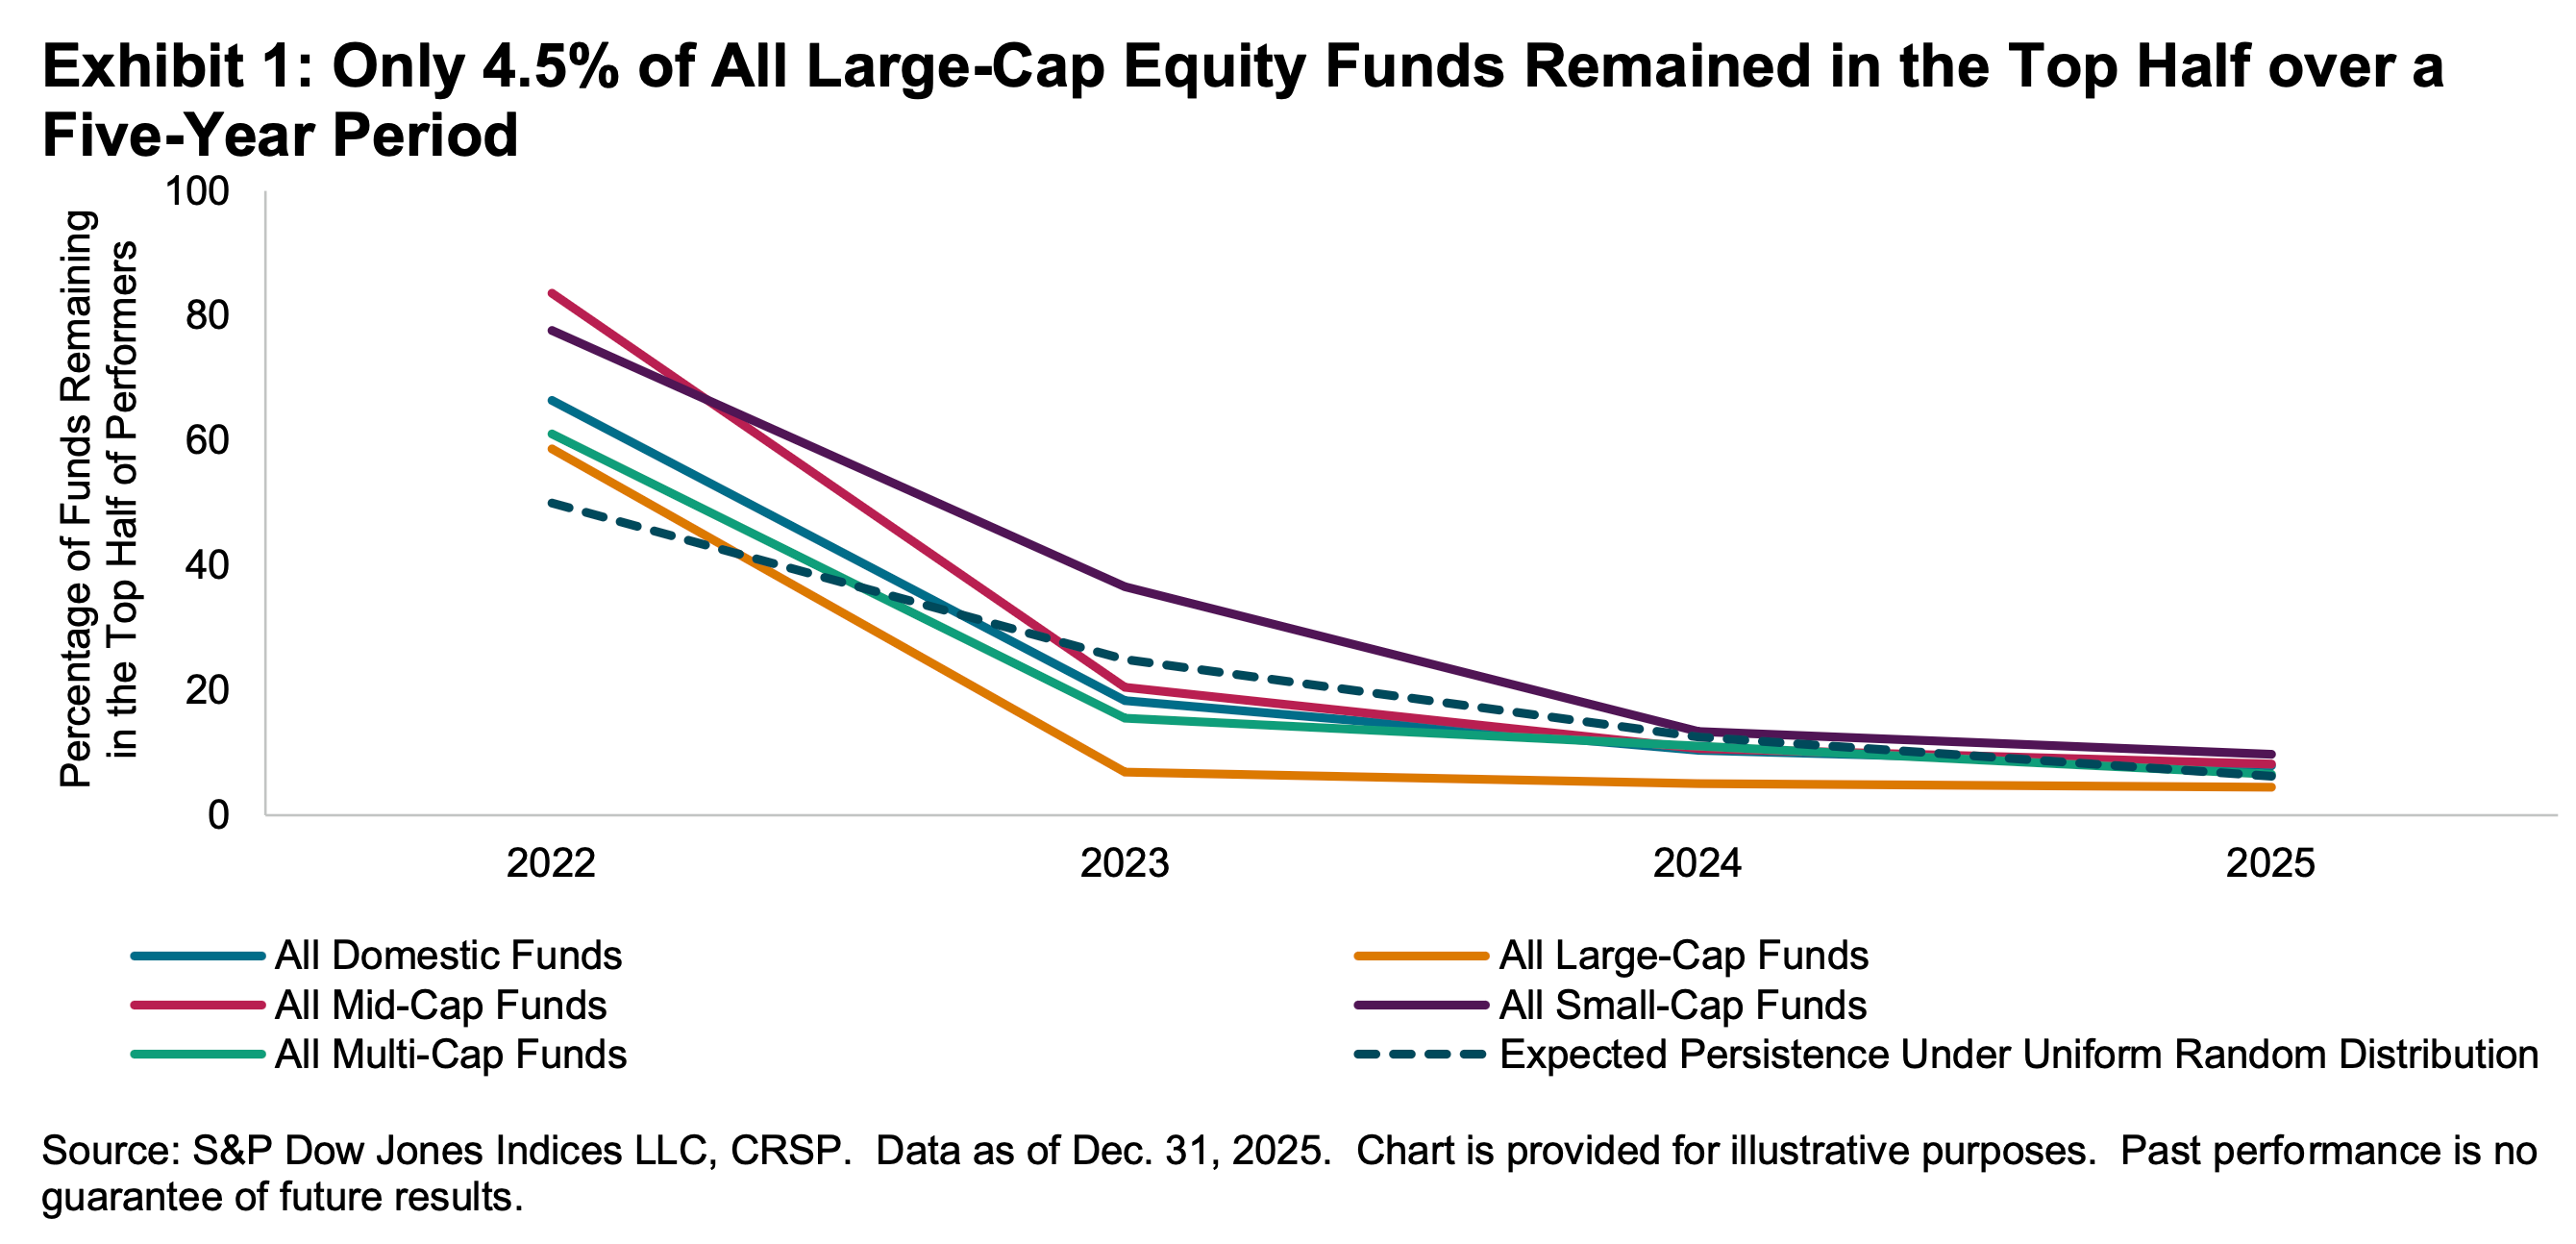
Even if you are a fund manager who generated industry-leading returns in one year, history says it’s an almost insurmountable task to stay on top consistently in subsequent years. According to S&P Dow Jones Indices, of the 334 large-cap equity funds in the top half of performance in 2021, 58.7% remained at the top half in 2022. However, just 6.9% remained on top through 2023. Only 4.5% stayed on top in the five consecutive years through 2025.
It’s much more dismal when you raise the bar. Of the 164 large-cap equity funds in the top quartile in 2021, just 20.1% remained in that category in 2022. That percentage fell to literally 0.0% in 2023.
The odds are stacked against stock pickers 🎲
Picking stocks in an attempt to beat market averages is an incredibly challenging and sometimes money-losing effort. Most professional stock pickers can’t do this consistently. One reason is that most stocks don’t deliver above-average returns. According to S&P Dow Jones Indices, only 19% of S&P 500 stocks outperformed the average stock return from 2001 to 2025. Over this period, the average S&P 500 stock returned 452%, while the median stock returned just 59%.